In this series of articles, we provide an overview of issuers currently on our watchlist, including the latest developments and our commentary on each issuer.
But before that, we have also provided a summary of several issuers that we are keen on:
|
Company |
Latest Developments |
Related article |
Comment |
|
Kenanga Investment Bank |
-In Q1FY2026, Kenanga’s revenue remained stable, with a marginal decline of 0.5% YoY to RM208.6 million. Profit before taxation and zakat declined by 55% YoY, mainly due to higher operating expenses - Kenanga’s credit profile remained solid despite the decline in its CET1 ratio to 14.78%. The decline was primarily driven by higher RWAs. -Kenanga is issuing an AT1 perpetual NC5, with an indicative yield of 6.1%. The issuance size is expected to be RM50 mil, and it is rated ‘A+’ by MARC. (Target book close date: 12 Aug 2026) - Investors should be aware of the inherent risks associated with AT1 perp: 1) Loss absorption feature 2) Non-call risk 3) Coupon deferral |
Idea of the Week: Don't Miss the Opportunity Again – Kenanga's Offering at a 6.1% Indic Yield |
- Kenanga's earnings and credit profile remain resilient at this juncture. -Upcoming AT1 NC5 perpetual offers an attractive investment opportunity for investors, with an indicative yield of 6.1% (representing a yield pick-up of approximately 270bps). |
Moving on to the next segment, here are the latest updates on issuers we are closely monitoring, which is exhibiting elevated credit risk or even under financial distress. We have marked the changes from the previous update in bold.
|
Company |
Latest Developments |
Related article |
Comment |
|
Tan Chong Motor Holdings Berhad |
- In 1Q26, the Group's performance remained under pressure, with revenue declining 17.2% YoY to RM457.8 million and a loss before tax (LBT) of RM8.3 million, despite recognising a RM20.1 million gain from the disposal of an asset classified as held for sale. - Operating cash flow before working capital changes is at negative RM31.1 million during the quarter. - On 12 June 2026, minority shareholders voted overwhelmingly against the proposed mandates for Recurrent Related-Party Transactions (RRRTs) at the AGM. |
- While July’s new RM200,000 CIF shield Tan Chong’s CKD pipeline and its Serendah assembly partnership for the Perodua QV-E, the operational turnaround remains in a monitoring phase, keeping us structurally negative from a bond perspective. -We believe the rejection of the proposed mandates at the AGM was mainly driven by concerns over Tan Chong’s prolonged losses and capital allocation. Independent shareholders appear increasingly dissatisfied and are reluctant to support transactions that could channel cash to sister companies without stronger scrutiny and oversight. |
|
|
Tropicana Corp |
- In 1Q26, revenue increased by 20.5% yoy to RM313mil, driven by higher progress billings arising from the completion of several projects within the Klang Valley and Northern regions. - Bottom line remained in the red, attributable to mark-to-market loss on quoted shares amounting to RM16.7 million, which was a non-cash item. Excluding this, the group would have recorded a profit before tax of RM3.9 million. - Tropicana has been actively deleveraging through asset monetisation and project completions, demonstrating continued commitment to debt reduction. - Possess a sizeable landbank of 1,336.1 acres across Malaysia, with an estimated GDV of RM97 billion as at 31 Dec 2025. |
-Anticipate continued improvement in the group’s profitability and balance sheet, with expansion in Johor serving as a key catalyst for future revenue growth. |
|
|
Serba Dinamik |
- The liquidation process remains ongoing. As of today, there has been no major breakthrough or definitive restructuring outcome announced. - The liquidator of Serba Dinamik has filed a lawsuit against former external auditor KPMG, claiming that KPMG failed to perform sufficient audit procedures and should have identified financial misstatements earlier.
- The liquidator is seeking at least RM1.56 billion in damages + interest.
|
NiL |
-The lawsuit introduces a potential additional source of recovery value for creditors should the liquidator successfully secure compensation from KPMG. -However, given Serba Dinamik’s substantial debt burden relative to its asset base, the overall recovery prospects remain highly uncertain. -Considering the uncertainties surrounding the litigation outcome, asset realisation process and liquidation timeline, potential recovery value remains fuzzy. |
|
Pestec International Berhad (deferred coupon x 2) |
- The group recorded a 13% qoq revenue decline to RM43.8 mil, due to lower revenue recognition within rail division. - Short term borrowing came in at RM358.5 mil, significantly more than cash and short-term deposits (RM71.1 mil) that the group has. - Given the current financial situation, we are of the view that further coupon deferment may continue. - The group’s auditor issued a qualified opinion for account ended 31 March 2026, citing insufficient evidence in terms of recoverability, for a RM50 mil contract asset. |
Nil |
- We are negative on Pestec’s ability to service coupon payments and principal redemption. - We believe that the company will involve perpetual holders in the restructuring plan, though timeline remains unknown. - We will continue to keep investors updated should there be any firm decision or outcome from the issuer. |
|
YNH Property Bhd (deferred coupon x 2) |
- On 8 July 2026, YNH announced the proposed disposal of a freehold commercial development land in Kuala Lumpur to Chin Hin Property (JSI) Sdn. Bhd. for RM455 million. - Cash proceed from the land disposal is primarily earmarked for the redemption of perpetual securities, thereby reducing stepped-up coupon obligations and improving liquidity. - The proposed disposal is subject to the fulfilment of customary conditions, including shareholders' approvals, relevant regulatory approval and more. - On 23 July 2026, YNH announced its second coupon deferral exercise for both outstanding perpetual securities tranches, deferring a combined RM34.41 million in coupon payments to preserve cash reserves for its active development pipeline and operational needs |
YNH Property Quick Update – Defers Perpetual Securities Coupon for a Second Time |
- We view the proposed disposal as positive for YNH's perpetual bondholders. - Despite that, we maintain our negative view on YNH. Tight liquidity, subdued revenue recognition, and continued reliance on asset disposals to meet debt obligations remain key credit concerns. |
|
Evergrande |
- Evergrande has officially entered a forced liquidation, and Alvarez & Marsal is the liquidator to handle the asset disposal. - Capability of liquidator is key to max recovery value for debtholders. Liquidators have experience in Lehman Brother and Luckin Coffee. - Hong Kong regulators fines PwC HKD1.3 billion over Evergrande audit work. |
The court ordered the liquidation of China Evergrande |
-The liquidation process is still ongoing, and we posit that it will take a couple of years to complete due to its scale. |
|
Century Sunshine |
-Trading in CENSUN shares has been suspended since 1 April 2025 due to the company’s failure to release its 2024 Annual Report on time. -No dividend was declared for the second scheme year, as the proceeds from the share disposals were insufficient to cover the scheme costs. -There is still no decision on whether the Zhangzhou Land should continue to be reserved for the bridging loan or be disposed of. -The Luozhuang Government unilaterally terminated the relocation agreement on the ground that Shandong Hongri failed to carry out soil remediation. Shandong Hongri appealed the decision, arguing that the termination is unjustified because no clear remediation standards had been provided. - One of Shandong Hongri’s creditors obtained an enforcement ruling ordering the auction of part of its land-use rights. The land is to be auctioned as “industrial land,” resulting in a significantly depressed valuation. Shandong Hongri has filed objections and applied to revoke the enforcement ruling and to stay the auction proceedings. |
-Listing status may be cancelled if the suspension remains in effect until 30 Sep 2026. Given that there are no other available assets, we hope the land title conversion of the Shandong Land will be successfully completed, as it is likely to unlock higher value when the land is disposed of after the conversion. |
In the next section, we will delve into the insights of the yield curves for Malaysian Government Securities (MGS), US Treasuries (UST), Singapore Government Securities (SGS) and Australia Government Securities (AGS).
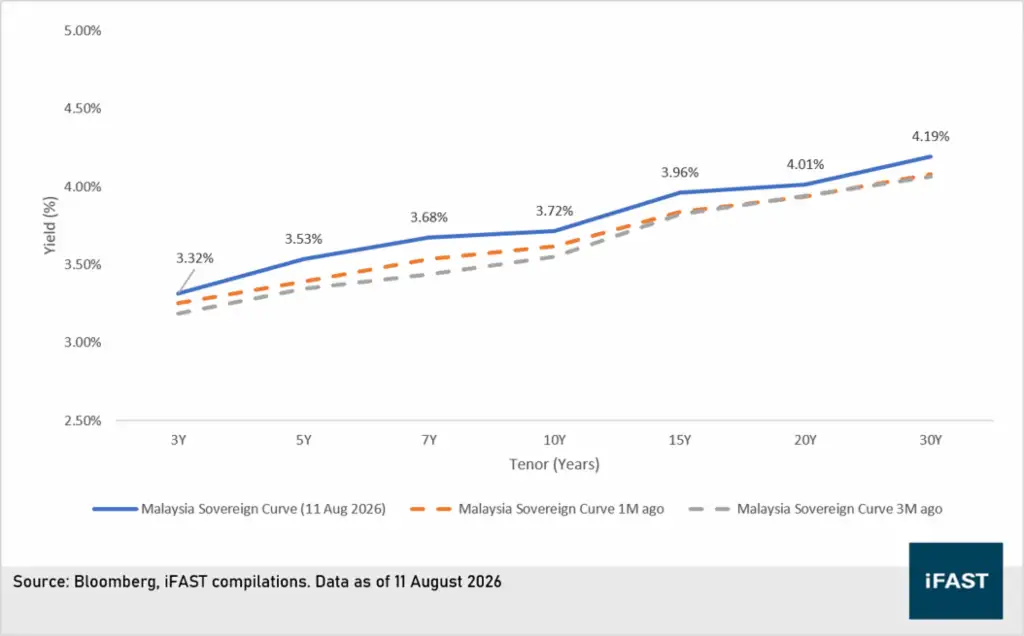
Our view on MGS:
1) Escalating geopolitical tensions between Israel and Iran have lifted global crude oil prices, adding inflationary pressure in near term and reinforcing our expectation of no rate cuts this year.
2) MGS yields are expected to trend slightly higher in 2H26, driven by election-related uncertainty and elevated US Treasury yields.
3) Shift preference from 5-7 year to medium-term 3–5 years
Chart 1: MGS Curve
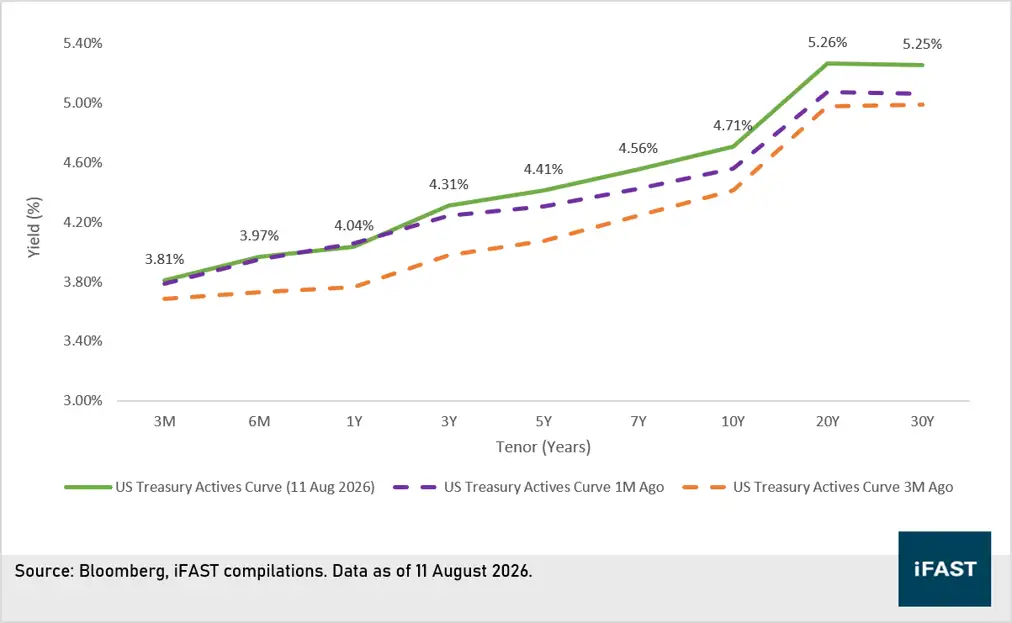
Our view on UST:
1) We see scope for potential rate hikes amid the Middle East conflict, alongside persistent inflationary pressures from tariffs and fiscal stimulus that could drive inflation higher.
2) We favour short and medium-duration bonds:
· Short-term: low sensitivity to interest rate movements.
· Medium-term: On selective basis (focusing on companies with strong balance sheets and good fundamentals)
Chart 2: UST Yield curve
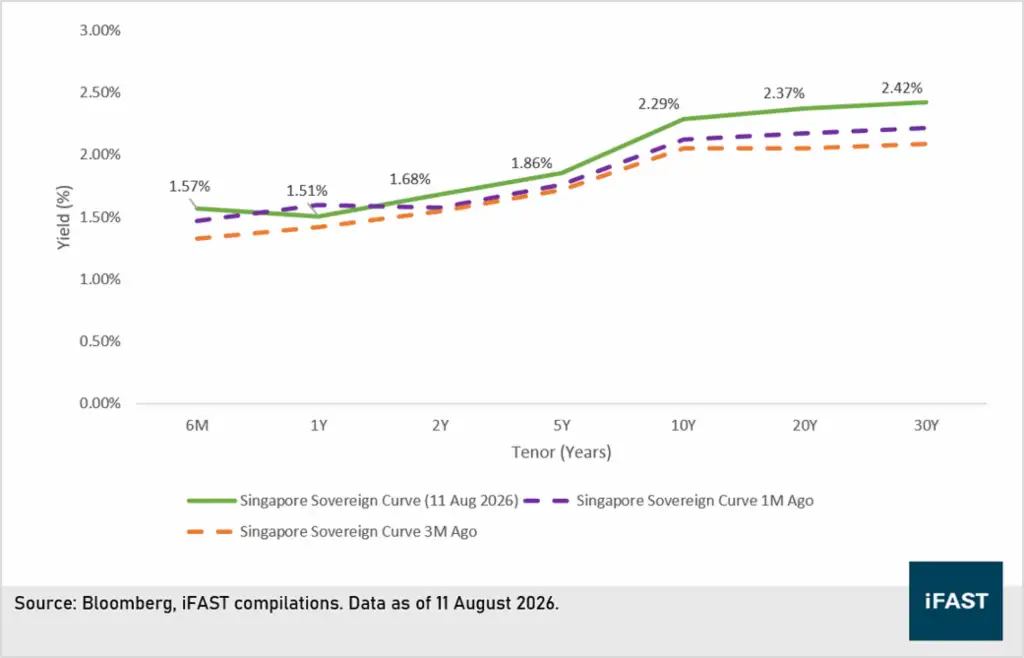
Our view on SGS:
1) Singapore interest rates are expected to remain rangebound with an upward bias, as potential global rate hikes provide upward pressure, while continued safe-haven and wealth inflows help anchor yields.
2) For bond recommendations, we favour:
- Short-term SG T-bills: Rolling 6-month to 1-year T-bills to remain nimble amid the uncertain rate environment.
- SGD financial corporate bonds: Tier 2 bank bonds, particularly investment-grade bonds issued by strong global banks.
- SGD non-financial corporate bonds: Quality issuers, with the 3–5 year tenor being the sweet spot, where the yield pickup is most attractive.
Chart 3: SGS Yield curve
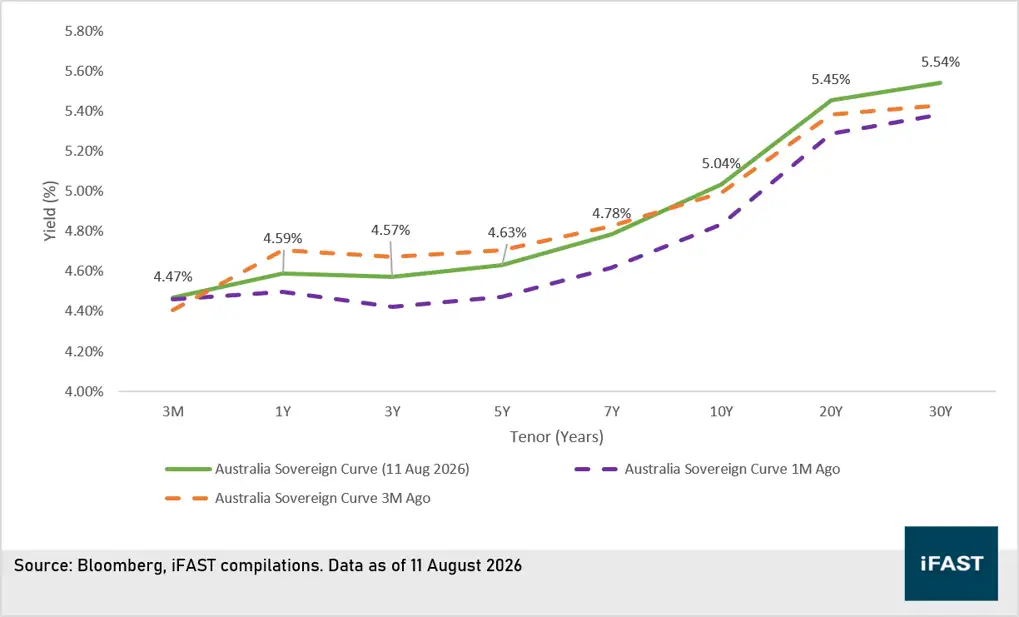
Our view on AGS:
1) June headline CPI eased to 3.8% y-o-y (from 4.0% in May), driven by lower fuel and goods disinflation. However, trimmed mean inflation remained sticky at 3.6% y-o-y, keeping RBA cautious.
2) With tight policy weighing on household balance sheets and property values, we believe RBA is likely near the end of its tightening cycle. We expect an extended pause, with at most one more rate hike if sticky core inflation persists.
3) We reiterate our preference for High-Quality Bonds and Barbell Strategy: We continue to favour barbell strategy, preferring both short (around 1-year) and longer tenors (7 to 10-years) of the yield curve.
Chart 4: AGS Yield curve
Some of the Credit Announcement by RAM & MARC (as of 31 July 2026)
RAM
1) Affirms Cypark Ref’s AA3 sukuk rating
2) Assigns inaugural AAA final rating to Sabah Energy Corporation’s proposed sukuk
3) Affirms Paradigm Capital’s 2025-Issue 1 MTN ratings
4) Affirms AFFIN Group’s AA3 financial institution ratings
5) Zamarad fully redeems Tranche 2 Sukuk; AAA rating withdrawn
6) Affirms Johor Corporation at AAA/Stable/P1
7) Affirms Sabah Credit Corporation’s AA1/Stable/P1 issue ratings
8) Affirms Sabah Development Bank’s AA1 rating, outlook stable
https://www.ram.com.my/news-events/?tab=list-ratingannouncement
MARC
1) Withdraws rating on Ranhill Sabah Energy II’s RM710.0 million IMTN Programme
2) Affirms TNB Western Energy’s AAAIS rating
3) Affirms AAIS(cg) rating on VS Capital Management
4) Affirms AA- rating on 7-Eleven Holdings’ MTN Programme
https://www.marc.com.my/insights/rating-announcements/
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds position in DJCMK 6.100% 31Mar2031 Corp (MYR), DJCMK 6.250% 13Nov2028 Corp (MYR), EVERRE 8.250% 23Mar2022 Corp (USD), EVERRE 7.500% 28Jun2023 Corp (USD) and the analyst who produced this report hold a NIL position in the abovementioned securities.