In this series of articles, we provide an overview of issuers currently on our watchlist, including the latest developments and our commentary on each issuer.
But before that, we have also provided a summary of several issuers that we are keen on:
|
Company |
Latest Developments |
Related article |
Comment |
|
Kenanga Investment Bank |
- In FY25, net income and PBT declined to RM660 million and RM73.6 million, respectively (-17% and -37%), mainly due to lower brokerage income and absence of one-off gain recorded in FY24. - Capital position remains strong, with a CET 1 ratio of 17.34% (vs the 7% minimum requirement) - Given that the bank has diversified its income base, its earnings should be underpinned by the investment banking and asset management divisions. - Kenanga is issuing an AT1 perp NC5 @ ~6.1% (representing about 270bps yield pickup vs 5Y MGS). Issue size: RM 50 million (with option to upsize) - We believe the risk-reward is justified. - Before buying AT1, investors should consider some risks, including: -Coupon Deferral -Non-Call Risk -Loss absorption feature. |
Kenanga’s 6.1% AT1 Perpetual Offers a Compelling Yield Opportunity |
We view that the stockbroking segment may continue to be volatile in the coming years amid intensifying competition within Malaysia’s brokerage industry. However, earnings are expected to be supported by the stable contributions from the investment banking and asset management divisions. Overall, Kenanga’s profitability and credit profile remain resilient at this juncture. |
Moving on to the next segment, here are the latest updates on issuers we are closely monitoring, which is exhibiting elevated credit risk or even under financial distress. We have marked the changes from the previous update in bold.
|
Company |
Latest Developments |
Related article |
Comment |
|
Tan Chong Motor Holdings Berhad |
- In FY25, Tan Chong’s profitability remained in the red, with net loss largely stable at RM200.5 million compared to RM220.8 million in FY24. The slight improvement was mainly due to the recognition of a one-off fair value gain on investment properties. - Liquidity remains weak. The cash position declined to RM286.6 million from RM545.5 million, mainly due to debt repayments. -Perodua is considering buying Tan Chong’s Serendah plant for about RM500 million. -Tan Chong completed a land sale at the end of March for a consideration of RM148.8 million, the proceeds of which are expected to support the group’s liquidity. |
Commentary on Tan Chong Motor |
- On a brighter note, Tan Chong is divesting its non-core assets to strengthen cashflow and its balance sheet. - However, we maintain a negative stance on Tan Chong given weak sales volumes and persistent competitive pressures in the automotive industry. - The situation could improve if Tan Chong manages to introduce more competitive car models. |
|
Pestec International Berhad |
- The issuer has deferred the perpetuals’ coupon payment for the period from 16 April 2025 to 16 October 2025. This marks the second coupon deferral by the group. - Auditors have expressed a material uncertainty relating to going concern for Pestec’s latest financial. - As of 31 Dec 2025, Pestec’s group reported a net profit of RM127.8 million, driven by other operating income of RM204.5 mil. However, this is due to non-cash, one off haircut on part of Pestec’s other creditors. - Cash flow from operating activity for 9 months ended 31 Dec 2025 is still negative at RM60.8 mil. Turnover remains distant. - Given the current financial situation, we are of the view that further coupon deferment may continue. |
Nil |
- We are negative on Pestec’s ability to service coupon payments and principal redemption. - We believe that the company will involve perpetual holders in the restructuring plan, though timeline remains unknown. |
|
YNH Property Bhd |
- On 23 January 2026, YNH announced it would defer upcoming coupon payments under its Perpetual Securities Issuance Programme as part of a strategic cash conservation plan. - The deferral applies to both outstanding perpetual securities tranches: - Tranche 1 –: Coupon originally scheduled for 9 February 2026. - Tranche 2 –: Coupon originally scheduled for 30 January 2026. - YNH announced that its wholly-owned subsidiary, YNH Construction Sdn Bhd, received a winding-up petition from LHDN over unpaid tax liabilities of RM7.2 million. The hearing is scheduled for 16 July 2026. - Management stated there is no immediate material financial or operational impact on the Group, and discussions with LHDN are ongoing with a proposed settlement arrangement already in place. |
YNH Property Quick Update - Exercises Option to Defer Perpetual Securities Coupon |
- YNH continues to actively dispose of its assets in order to repay outstanding borrowings and meet its working capital needs. However, its liquidity position remains weak, with cash and short-term deposits of only RM17 million, compared with RM226 million of debt maturing in short term. - We maintain a negative view on the issuer from an operational perspective. Given its tight liquidity position, they may continue to defer coupon payments on its perpetuals in the near term. |
|
Evergrande |
- Evergrande has officially entered a forced liquidation, and Alvarez & Marsal is the liquidator to handle the asset disposal. - Capability of liquidator is key to max recovery value for debtholders. Liquidators have experience in Lehman Brother and Luckin Coffee. - According to Bloomberg, Hong Kong’s Securities and Futures Commission has reached an agreement with PwC HK under which the firm has agreed to set aside HKD1 billion to compensate eligible independent minority shareholders of Evergrande. - Evergrande’s liquidators will face PwC in court on May 18 to determine if the lawsuit over audit negligence and fund recovery can proceed. |
The court ordered the liquidation of China Evergrande |
- The SFC's legal actions against PwC is a separate lawsuit from the liquidator's. The compensation will bypass the liquidation waterfall and is paid to minority shareholders directly. It may not be positive to creditors as PwC's ability to pay is finite, and this agreement also shows that they want to settle the regulatory front first. -The liquidation process is still ongoing, and we posit that it will take a couple of years to complete due to its scale. |
|
Century Sunshine |
-Trading in CENSUN shares has been suspended since 1 April 2025 due to the company’s failure to release its 2024 Annual Report on time. -No dividend was declared for the second scheme year, as the proceeds from the share disposals were insufficient to cover the scheme costs. -There is still no decision on whether the Zhangzhou Land should continue to be reserved for the bridging loan or be disposed of. -The Luozhuang Government unilaterally terminated the relocation agreement on the ground that Shandong Hongri failed to carry out soil remediation. Shandong Hongri appealed the decision, arguing that the termination is unjustified because no clear remediation standards had been provided. - One of Shandong Hongri’s creditors obtained an enforcement ruling ordering the auction of part of its land-use rights. The land is to be auctioned as “industrial land,” resulting in a significantly depressed valuation. Shandong Hongri has filed objections and applied to revoke the enforcement ruling and to stay the auction proceedings. |
-Listing status may be cancelled if the suspension remains in effect until 30 Sep 2025. Given that there are no other available assets, we hope the land title conversion of the Shandong Land will be successfully completed, as it is likely to unlock higher value when the land is disposed of after the conversion. |
In the next section, we will delve into the insights of the yield curves for Malaysian Government Securities (MGS), US Treasuries (UST), Singapore Government Securities (SGS) and Australia Government Securities (AGS).
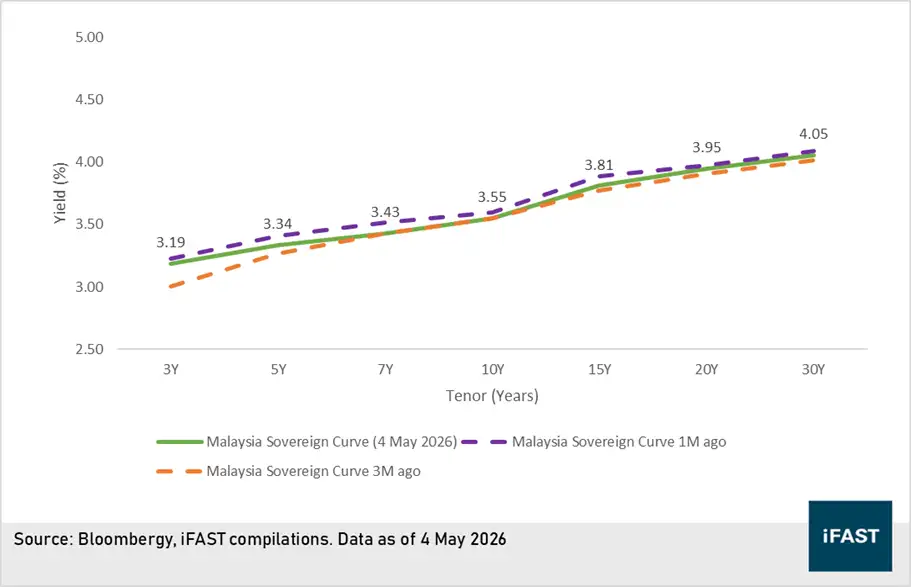
Our view on MGS:
1) Escalating geopolitical tensions between Israel and Iran have lifted global crude oil prices, adding inflationary pressure in near term and reinforcing our expectation of no rate cuts this year.
2) BNM keeps Overnight Policy Rate (OPR) steady at 2.75% in May 2026.
3) Continue to prefer medium-term (5-7 years).
4) Yields across the different tenors are expected to remain range-bound throughout the year.
Chart 1: MGS Curve
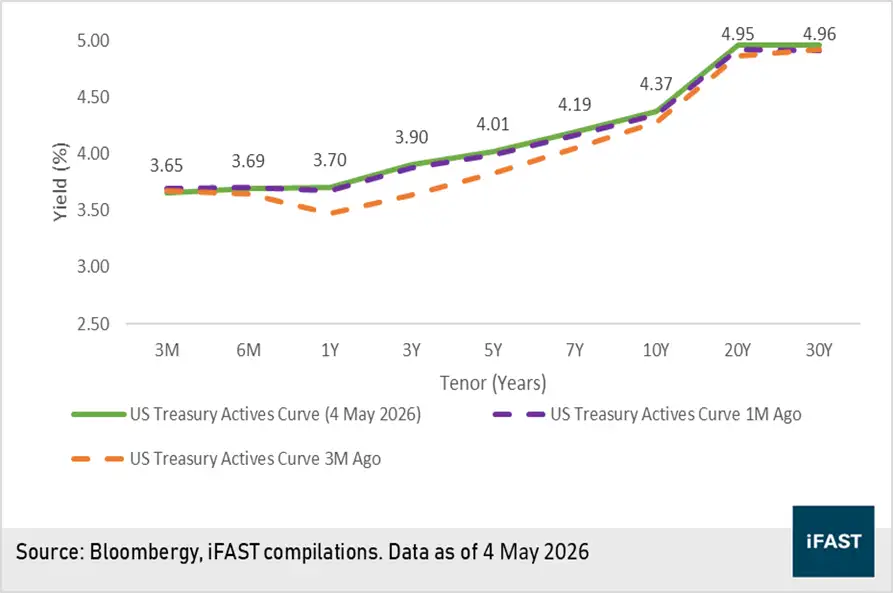
Our view on UST:
1) We see scope for potential rate hikes amid the Middle East conflict, alongside persistent inflationary pressures from tariffs and fiscal stimulus that could drive inflation higher. This marks a shift from our previous expectations of possible rate cuts stated in our Outlook 2026 article in December.
2) We favour short and medium-duration bonds:
Short-term: low sensitivity to interest rate movements.
Medium-term: On selective basis (focusing on companies with strong balance sheets and good fundamentals)
Chart 2: UST Yield curve
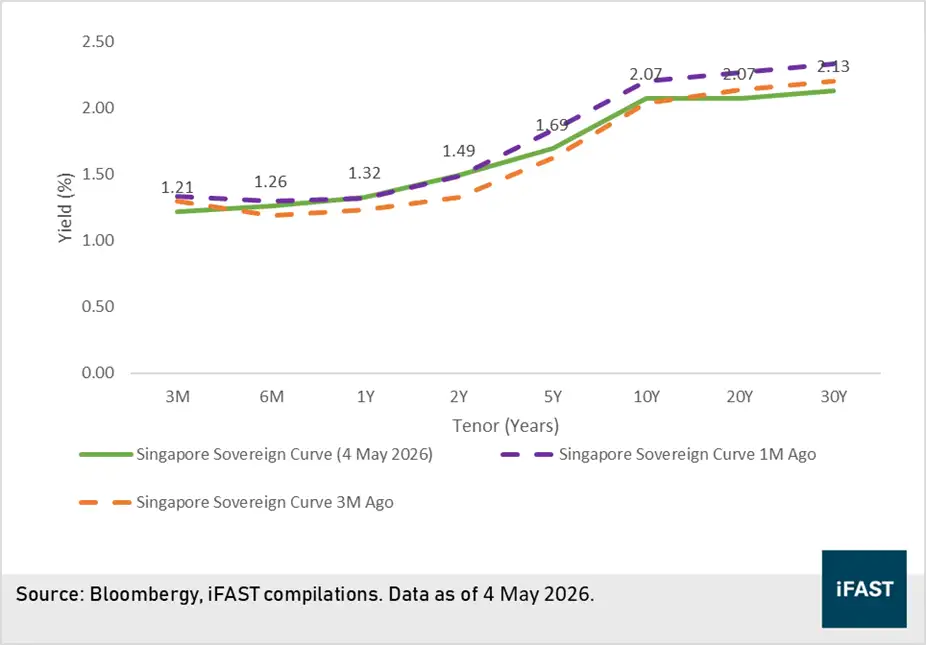
1) Singapore interest rates are expected to remain rangebound with an upward bias, as potential global rate hikes provide upward pressure, while continued safe-haven and wealth inflows help anchor yields.
2) Favour shorter-term bonds (3-5Y); Selectively constructive on medium tenor issues (5-8Y)
Chart 3: SGS Yield curve
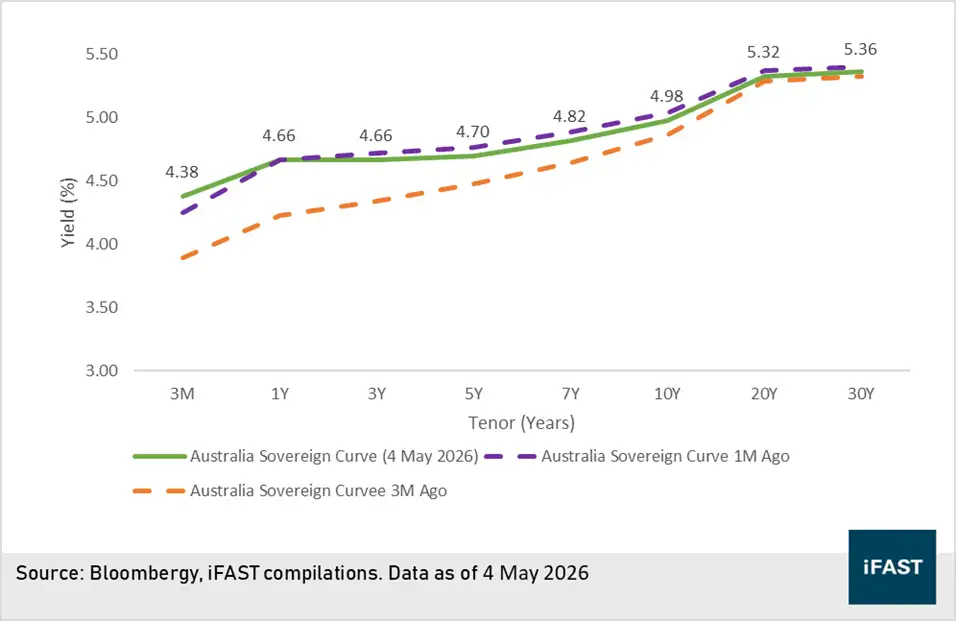
Our view on AGS:
1) The Reserve Bank of Australia has raised the cash rate to 4.35% and could deliver one final hike, although rates now appear close to the terminal rate.
2) Major companies have started passing through higher transport and input costs, pointing to broader and more persistent inflation.
3) We continue to favour a Barbell strategy, allocating exposure to both short-duration bonds (around the 1-year tenor) and longer-duration bonds (7 – 10-years).
Chart 4: AGS Yield curve
Some of the Credit Announcement by RAM & MARC (as of 30 Apr 2026)
RAM
1) RAM Ratings assigns AAA rating to TNB’s RM10 bil IMTN programme
2) RAM Ratings raises outlook on MNRB and Malaysian Re to positive, affirms ratings
3) RAM Ratings assigns preliminary AA3/Stable rating to Exsim Capital’s Tranche 8 IMTN
4) RAM Ratings affirms AAA/Stable rating of sukuk issued by KLCC REIT’s funding conduit Midciti
5) RAM Ratings raises outlook on RHB Group’s AA1 rating to Positive
https://www.ram.com.my/news-events/?tab=list-ratingannouncement
MARC
1) MARC Ratings affirms rating on Cagamas MBS’ asset-backed Sukuk Musyarakah
2) MARC Ratings withdraws ratings on Sunway Treasury Sukuk’s RM10.0 billion ICP/IMTN Programme
3) MARC Ratings affirms OCK’s MARC-1IS and AA-IS ratings
4) MARC Ratings assigns final rating of AA+IS to TNB Kuala Muda Solar’s proposed ASEAN Green SRI Sukuk Wakalah
5) MARC Ratings assigns final rating of AAIS to Evyap Sabun Malaysia’s Sukuk Wakalah Programme of up to RM1.0 billion
https://www.marc.com.my/insights/rating-announcements/