


Agriculture is one of the oldest businesses in history and there is a fundamental need for agricultural products, especially when food demand is high and supplies are low. The need and importance of ensuring food security was recently emphasized during the recent pandemic outbreak.
In addition, a weak US dollar, logistical bottlenecks, poor weather and the tendency to hoard supplies have driven agricultural prices higher. The Bloomberg Agricultural Spot Index has risen close to 50% since the low on 28 Apr 20.
About the new issue
Olam International Limited (“Olam”), a large food and agribusiness supplier of food and food ingredients is looking to refinance its debt through a perpetual note offering. The perps are unrated and issued under the terms of the USD billion Euro Medium Term Note Programme dated 5 May 20.
If the issuer does not redeem the perp after 5.5years on its first call date, the distribution rate on the note resets to the sum of the prevailing 5-year SOR reference rate, initial spread and step-up rate of 200 basis points.
A dividend stopper and distribution deferral clause are also applicable with a look-back period of 3 months. Furthermore, the issuer has the option to redeem the notes if the perpetual securities are no longer recorded as “equity” due to changes in the Singapore Financial Reporting Standards.
About the issuer
Established in 1989 as a division of the Kewalram Chanrai Group and incorporated in Singapore around July 1995, Olam has an operating presence in over 60 countries supplying agricultural products to over 25,000 customers.
The group is one of the biggest 30 companies on the Singapore Exchange by market capitalization (11 Jan 21: S$4.94 billion). As at May 2020, Temasek Holdings (Private) Limited is a 53.4% shareholder of the company and Mitsubishi Corporation, one of the largest trading companies in Japan, has an approximate 17.4% stake in the firm.
Olam’s operations is mainly segregated into two groups — Olam Food Ingredients (“OFI”) and Olam Global Agri (“OGA”) — both of which are held by the parent firm Olam International Limited. OFI’s portfolio includes Cocoa, Coffee, Edible Nuts, Spices and Dairy, and other natural food products. On the other hand, OGA is made up of Grains and Animal Feed & Protein, Edible Oils, Rice, Cotton and Commodity Financial Services.
Credit highlights
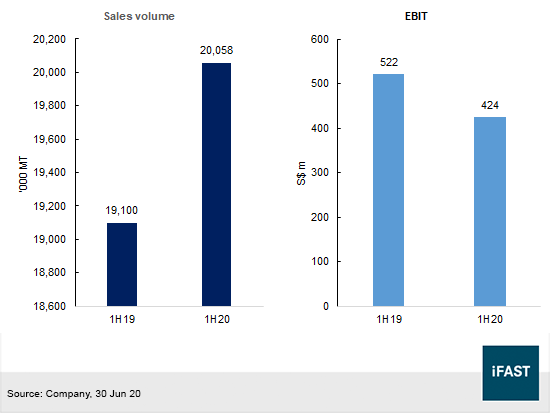
Olam reported top- and bottom-line gains in the half-year ending 30 Jun 20 (“1H20”). Revenue grew by 7.1% YoY and profit after tax increased 42.2% YoY to S$295.4m. Sales volume grew 5.0% to 20.1m metric tonnes mostly due to higher volume in Olam Global Agri’s Origination and Merchandising segment.
EBIT decreased 18.8% to S$424m on the back of a S$176m fall in the Olam Food Ingredient division. Almonds & Dairy saw lower demand due to the lockdown in China during 1H20, but the overall demand for food staples was quite resilient.
From a longer-term perspective, EBIT trends have been broadly positive across segments. Olam generated S$947m, S$843m and S$1,057m of EBIT in 2017, 2018 and 2019 respectively. Even though the group experienced recent headwinds due to COVID-19, we believe that Olam still has a healthy cash-flow generating ability.
Figure 1: Group sales volume and EBIT
In addition, the company revealed that 80-85% of its food revenue is less susceptible to an economic downturn. EBIT is projected to recover in 2H20 but due to a one-off impairment charge from its investment in Olam Palm Gabon, the group will report a net loss in 2H20. Nonetheless, following its recent guidance, the company still expects net profit to remain positive in 2020.
Olam invested in a large drip irrigation project in Gabon but the project had been delayed by 12 to 18 months due to the pandemic. Subsequently, a periodic year-end review and reduction in the carrying value of the asset will lead to a possible USD350m impairment in its 2H20 income statement.
Operating cash flow before reinvestment in working capital contracted from S$770.0m in 1H19 to S$683.9m in 1H20. After accounting for changes in working capital, interest and taxes, net cash flow generated from operating activities decreased from S$1.22 billion to S$934.6m.
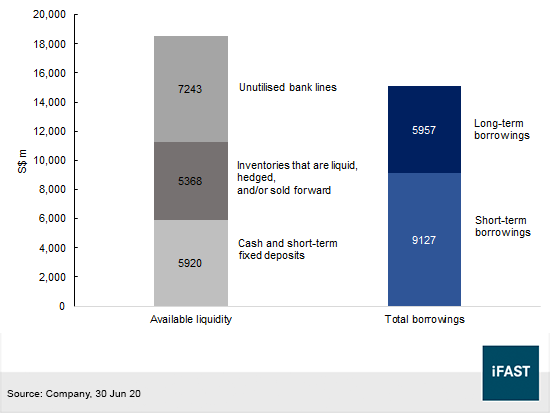
Cash and deposits increased by S$2.74 billion in 1H20 to S$5.92 billion. With S$19.9 billion of available liquidity, we think the agribusiness conglomerate has strong financial capacity to meet its financial obligations. Notably, there were S$7.24 billion of undrawn bank lines available to the firm at the end of June. Since then, the company’s liquidity profile may have improved as it managed to raise at least SGD700m in the third quarter and upsized its flagship debt facility by USD300m to USD1,975m.
Figure 2: Sources of liquidity
Olam’s credit metrics weakened in 1H20 but still remained at a comfortable level. EBIT over interest expense declined to 1.4x in 1H20 from 1.6x in 1H19. Gearing, defined as net debt over equity, was almost unchanged at around 1.29x in the same period (1H19: 1.28x).
Our comments on the note’s pricing
Olam International Limited’s new perpetual security is attractively priced at an initial price guidance (“IPG”) of 5.5%. This is equivalent to 500 basis points (“bps”) above the current 5-year Swap Offer Rate, or 508bps above the 5-year Singapore Overnight Rate Average (“SORA”) benchmark. The discontinuation of LIBOR has prompted MAS to launch several initiatives to support the use of SORA as a financial pricing benchmark. There is a possibility that SORA will replace the SOR in the near future as other countries have transitioned away from the use of LIBOR.
As mentioned in its pricing supplement, Olam is using the proceeds from this offering to refinance short term indebtedness. Olam raised JPY7 billion in December through the OLAMSP 2.05% 2025’s, which may be used to repay the JPY5.5 billion OLAMSP 1.427% 2021’s due in May 2021. Within its near term maturities, we note that the OLAMSP 4.500% 12Apr2021 Corp (USD) is maturing in April this year with an outstanding amount of USD 450m.
Compared to other perpetual securities, the 5.5% price guidance represents one of the highest yielding notes among SGD notes of similar call dates (Figure 3).
Figure 3: Relative valuation among SGD perps with similar call dates
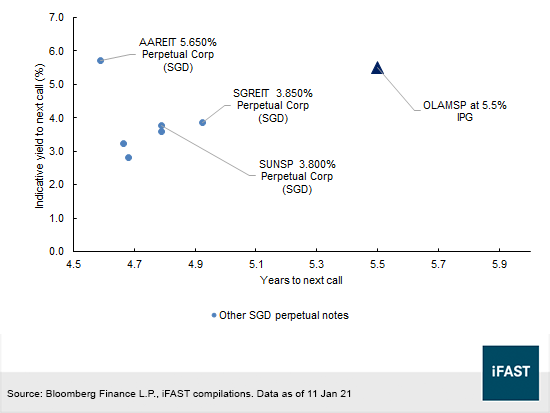
The AAREIT 5.650% Perpetual Corp (SGD) may be trading at a higher yield to next call at 5.71%, but we believe that the issuer does not have a comparable level of institutional support as Olam. The company also operates as a real estate investment trust that has a different business dynamic and less favorable outlook than agribusinesses. AIMS APAC REIT, or AAREIT is an industrial REIT with a real estate portfolio within the Asia Pacific region with a smaller revenue base and market capitalization of S$897m.
That aside, Olam’s new note has a higher yield than the SGREIT 3.850% Perpetual Corp (SGD) and SUNSP 3.800% Perpetual Corp (SGD). Given its easy access to liquidity and good cash-flow generating ability, we think Olam’s new note is attractively priced among SGD perpetual securities.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in OLAMSP 6.000% 25Oct2022 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!


