Singapore Press Holdings is restructuring its media assets in view of declining revenue from print subscriptions and advertisements.
Even though the proposed transaction would weigh on earnings and increase the gearing of the company in the short term, SPH guided that operating profits would improve after its restructuring.
We maintain our positive view on the issuer and its outstanding fixed income issues.
After conducting its Strategic Review early this year, Singapore Press Holdings Limited (“SPH”) announced that it will transfer its media business to a new not-for-profit entity. The proposed restructuring is a first step in a series of options to create more value for all SPH stakeholders.
As part of the proposed transaction, SPH will transfer its media assets to a company limited by guarantee (“CLG”) – a public entity with no share capital that is prohibited from paying profits or dividends to its members. The liability of the CLG members is restricted to the amount of their contributions. However, a CLG may apply for charity status, which allows it to claim tax deductions. Further details on the CLG will be provided in future and SPH has announced that it will assist in the operation and maintenance of the new entity.
A holding company will be set up to procure the assets from SPH. More specifically, SPH will transfer (1) SGD 80m in cash, (2) 23,446,659 of SPH REIT shares (market value on 6 May 2021: SGD 20.5m), (3) 6,868,132 of SPH shares (6 May 2021: SGD 12.3m), (4) issued share capital of its media companies (with a net asset value on 28 Feb 2021: SGD 88.8m) and (5) leases of the properties at 1000 Toa Payoh North and 2 Jurong Port Road (net asset value at 28 Feb 2021: ~SGD 48.0m).
SPH expects to complete the transaction by the end of this year, or possibly by the start of 2022. But before that, the company has to first obtain (a) the approval of JTC Corporation for the assignment of the property leases; (b) the approval from the Minister for Communications and Information and/or the Info-communications Media Development Authority for the termination of the relevant publication permits and broadcasting rights at SPH, and the granting of equivalent permits and rights to the new CLG; and (c) the approval of shareholders at the upcoming extraordinary general meeting.
Recent financial performance
Group financial performance improved in the half-year period ended 28 Feb 2021 (“1HFY2021”). Total revenue fell by 4.2% YoY to SGD 460.3m from SGD 480.3m in 1HFY2020. This was due to a 11.5% fall in operating revenue and poor advertisement sales. The group would have recorded lower total revenue had it not been for the income from the Jobs Support Scheme (SGD 15m), SGD 6.2m divestment gain of its exhibitions business and SGD 9.4m income from the Student Castle portfolio acquisition.
After factoring SGD 340.5m of total costs, SGD 8.4m of fair value property impairments, SGD 4.5m of results from its associates, and SGD 20.9m of investment income, group profit after taxation increased to SGD 124.2m in 1HFY2021, up from SGD 101.7m in 1HFY2020.
The group’s credit ratios also registered gains. As at 28 Feb 20221, SPH recorded a cash position of SGD 959.5m and this is more than adequate to cover its SGD 913.2m of current borrowings. According to the company, its net debt to asset ratio dropped from 32.7% at 31 Aug 2020 to 30.9% at 28 Feb 2021. Interest coverage was also healthy at 5.7x in 1HFY2021, up from 3.8x in 2HFY2020.
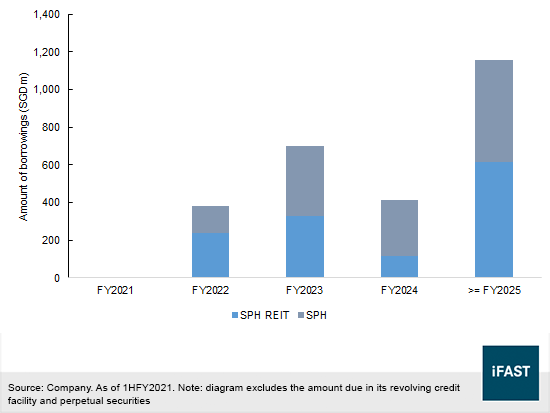
According to the debt maturity profile of its non-current borrowings, the company is obligated to pay down ~SGD380m of borrowings due in FY2022 and ~SGD699m in FY2023. In FY2024, SPH has the option to redeem SGD 150m of SPHSP 4.000% Perpetual Corp (SGD) while SPH REIT may also redeem SGD 300m of SPHRSP 4.100% Perpetual Corp (SGD) on its first call dates. However, we are still comfortable with its refinancing ability as the company managed to refinance its SGD 300m term loan for the Seletar Mall due in June 2021 and SGD 215m loans at SPH REIT.
Figure 1: Debt maturity profile
Pro-forma financial impact
With the restructuring of the media arm, SPH will effectively become an investment and property company. Its remaining portfolio assets include the retail and commercial properties held at SPH REIT, the Seletar Mall, condominium units at the Woodleigh Residence, Purpose-Built Student Accommodations in the UK, Aged Care portfolio in Singapore and Japan, and 40% stake in data centre facilities at Genting Lane.
Additionally, the provisions of the Newspaper and Printing Presses Act may not be applicable to SPH upon the completion of the proposed transaction. This means that potential strategic investors/partners could acquire more than 5% of SPH shares without first obtaining the approval of the Minister.
Pursuant to the transfer of the abovementioned items (1) to (5), the 1HFY2021 pro-forma financial net tangible asset value for SPH is projected to fall 6.8% to SGD 3,243m after the restructuring. Net assets meanwhile will drop to SGD 3,364m.
As we understand, the restructuring of the media business is short term negative but long term positive for the company’s earnings. According to the company’s presentation, profit after tax and minority interest (excluding job support grants) or, “adjusted PATMI” for 1HFY2021 is forecasted to fall from a profit of SGD 85m to a loss of SGD 122m (including restructuring adjustments). These restructuring adjustments are one-time effects so excluding these adjustments, adjusted PATMI would increase to SGD 95m.
SPH is effectively separating a poor performing unit from its business. Media accounted for SGD 193.1m of operating revenue in 1HFY2021 so pro-forma revenue will fall significantly. Following its guidance, operating revenue will decrease from SGD 417m to SGD 224m.
However, operating profit (excluding job support grants) is projected to increase from SGD 107m to SGD 117m in 1HFY2021. When expressed as a multiple of interest expense (including distributions to perpetual holders), operating profit would be around ~2.8x of interest costs – which is still a fairly healthy level.
Operating profit will improve in the long term as the company focuses its effort on its other assets to unlock value for stakeholders. In our opinion, the company’s move to streamline operations and reduce cost would be credit positive for noteholders.
SPH would take a hit on its earnings and gearing in the short term. The company will inject SGD 351.3m in the form of cash, shares, issued capital and property leases to the new entity. If we consider the net asset value instead of market value of the leases, then the contribution from SPH would amount to SGD 252.3m.
The group’s cash injection of SGD 80m is relatively small compared to the cash balance of 959.5m at February 2021. Pro-forma gearing as at 1HFY2021, defined as net debt over total assets is projected to increase from 30.9% to 32.4%.
Relative valuation
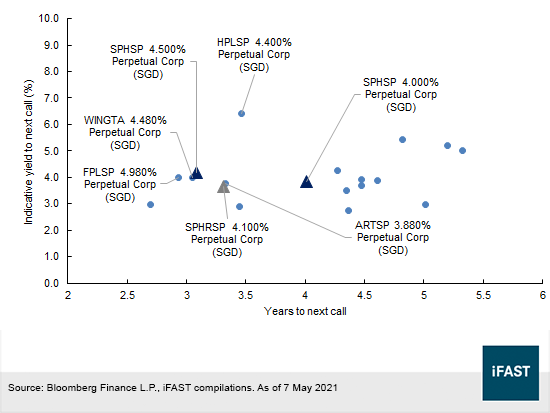
Prices of the SPHSP 4.5% perps have plunged materially since the company’s restructuring announcement yesterday. As seen in Figure 2, the valuation of the notes has reached a point where the yields have exceeded some perps that have longer call dates. This may be a reflection of investor concerns about the group’s elevated gearing, earnings pressure and material drop in revenue.
Keeping with our earlier view in “Earn 4.2% from this SPH perp while you wait for the vaccine”, we continue to keep a positive outlook on the SPHSP 4.500% Perpetual Corp (SGD). We believe that the company still has enough liquidity to service its bond obligations. As such, we maintain our constructive view on the issuer. The perps traded at an indicative yield to call (“YTC”) of 4.17% on 7 May 2021, and is the most attractively priced security along the SPHSP and SPHRSP curve (Figure 2).
Figure 2: Relative valuation among SGD non-bank perpetual notes
The SPHSP 4.5% perps have a first call date on 7 Jun 2024 and are callable every six months thereafter. If the issuer does not redeem the note in June 2024, the distribution rate on the perps would reset to the sum of the prevailing five-year SGD swap offer rate, the initial spread of 261.2 basis points (“bps”) and a step-up margin of 100 bps. In addition, the perps include terms such as a cessation put, a dividend stopper and dividend pusher with a six-month look-back period.
Apart from the SPHSP 4.5% perp, we also like the WINGTA 4.480% Perpetual Corp (SGD) and FPLSP 4.980% Perpetual Corp (SGD) at their indicative YTCs of 3.98% and 3.99% respectively. Between these two notes, the FPLSP 4.98% perps would have a more attractive valuation given its earlier call date.
WINGTA, or Wing Tai Holdings Ltd is a property developer and retail operator. The company reported strong operating results recently thanks on the back of higher property sales with operating profits increasing by 83%. The group also has a healthy balance sheet and low gearing ratio. Kindly refer to “Perpetual notes of Wing Tai Holdings can be one of the next best things to condo investments” for more information.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in ARTSP 3.070% Perpetual Corp (SGD), FPLSP 4.980% Perpetual Corp (SGD), SPHSP 4.500% Perpetual Corp (SGD) and WINGTA 4.080% Perpetual Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities. SPH is a substantial shareholder of iFAST Corporation Ltd (parent of IFPL), holding a 14.63% deemed interest (as at 5 Mar 21) through its wholly-owned subsidiary, SPH Invest Ltd.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!