


After issuing the SINTEC 4.100% Perpetual Corp (SGD) last year, Singapore Technologies Telemedia Pte Ltd (“ST Telemedia”) is looking to raise more capital through a new SGD perpetual note offering. The new perps are callable in May 2029 and they have an initial price guidance (“IPG”) of 4.5%.
About the perpetual notes
Priced under the terms of its SGD 2b Multicurrency Debt Issuance Programme, the notes are unsecured and subordinated obligations of the issuer. Coupon deferrals are cumulative and a dividend stopper clause is applicable with a 12-months look back period.
The perps are first callable in May 2029. If not called on its first call date, the distribution rate on the notes will reset to the prevailing 7-year SGD SORA-OIS + initial spread + 100 basis points (i.e. the step-up margin).
In addition, the issuer has the right to redeem the notes for taxation, accounting or tax deductibility reasons. Notes may also be redeemed if the outstanding amount falls below 20% of its original issued principal amount.
Net proceeds of the issuance of the perpetual notes will be used for financing the general corporate funding requirements or investments of ST Telemedia and its subsidiaries.
About the issuer
ST Telemedia is a subsidiary of Temasek and is an active investor within the Communications, Media and Technology industry. It adopts a long-term investment approach and has a long track record of growing businesses into market leaders within their respective sectors.
Some of its investee companies include StarHub Ltd (indirect interest: ~55.8%), GDS Holdings Limited (~31.9%, which is indirectly held via STT GDC Pte. Ltd.), Datameer, Inc. and Armor Defence Inc. StarHub and GDS have an approximate market capitalization of SGD 2.16b and USD 11.29b respectively. Collectively, the combined market value of these 2 firms already exceed the book equity value of ST Telemedia of SGD 5.25b (as at 30 June 2021).
Temasek Holdings (Private) Limited is a sovereign wealth fund and wholly owned by the Government of Singapore through the Ministry of Finance. Temasek does not directly manage the operations or commercial affairs of the ST Telemedia group.
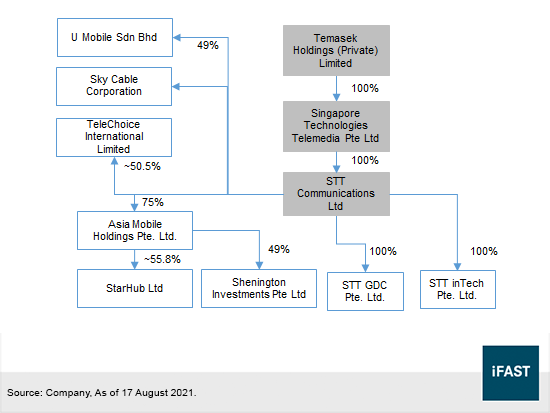
The group recognizes revenue from 3 business segments, namely (1) Communications and Media Services, (2) Data Centres and (3) Infrastructure Technologies. Communications and Media Services comprises of Asia Mobile Holdings Pte Ltd, TeleChoice International Limited, Sky Cable Corporation and U Mobile Sdn Bhd. Data Centres are operated by STT GDC Pte. Ltd., while STT inTech Pte. Ltd oversees Infrastructure Technologies. A simplified corporate structure of the ST Telemedia group is shown in Figure 1.
Figure 1: Simplified corporate structure of the ST Telemedia group
In more recent corporate developments, ST Telemedia acquired a majority stake in CloudCover, a cloud-native product and services company in January 2020. GDS Holdings was listed on the public exchanges in October 2020 and this year, the group formed a joint venture with Hyosung Heavy Industries to operate a data centre in Korea. It also announced a partnership with Triputra Group to establish a data centre in Indonesia.
Financial highlights
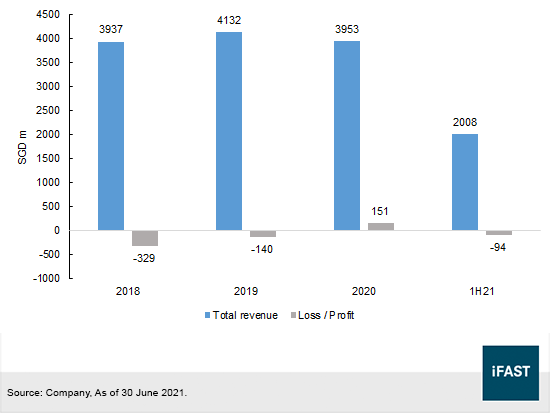
Revenue growth was rather mediocre and flat since 2018, rising slightly to SGD 4,132m in 2019 before falling to SGD 3,953m in 2020. Revenue totalled to SGD 2,008m during the 6-month period ended 30 June 2021 (“1H21”), and may reach ~SGD 4b by the end of the year but the group made a loss of SGD 94m in 1H21. However, annual profitability had been improving since three years ago, having reversed its loss of SGD 329m in 2018 to registering a net profit of SGD 151m in 2020.
Figure 2: Group revenue and net profit since 2018
Mobile revenue accounts for 36.9% of 1H21 total revenue. Data centres and co-location services account for 19.4%, whilst enterprise fixed revenue represents approximately 16.6% of total 1H21 revenue.
Among its subsidiaries, we observed that StarHub (SGD 2029m), TeleChoice (SGD 213m), STT GDC (SGD 633m) and U Mobile (SGD 1045m) were the largest contributors to total revenue in 2020. With regard to their performance since 2018, StarHub has been consistently profitable with profits before tax of SGD 245m (2018), SGD 219m (2019) and SGD 193m (2020) respectively.
In contrast, U Mobile made losses of SGD 166m, SGD 70m and SGD 130m respectively in those 3 years. Profitability of STT GDC had improved over the years, as it turned from a loss of SGD 244m in 2018 to a net profit of SGD 28m in 2020.
According to our estimates, group EBIT amounted to ~SGD 93m in 2020 and ~SGD 61m in 1H21. EBITDA, which excludes depreciation, amortisation and impairment charges was ~SGD 961m in 2020 and ~SGD 470m in 1H21. When divided by interest expenses, estimated EBITDA/Interest is around ~3.3x – which is a fairly comfortable level in our opinion. In the first 6-months of this year, operating cash flow before working capital changes added to SGD 536m whereas net cash from operating activities was SGD 378m.
Group liquidity is abundant with SGD 2079m of cash and cash equivalents as at 30 June 2021. The amount of cash exceeds its SGD 362m of current borrowings by a significant amount implying that the company is in a strong liquidity position.
However, group gearing is high with SGD 6247m of non-current borrowings and SGD 6609m of total debt. Gearing – defined as total debt over total assets is 45.3% in 1H21 with net debt over equity at 86.4%. Treating perpetual securities as debt, gearing would increase to 50.4% and 116.8% respectively.
Relative valuation
We think that the initial price guidance of 4.5% (305 basis points above the SORA-OIS curve) for the new ST Telemedia perpetual notes is attractive although we would prefer a higher guidance as the group’s credit performance weakened in 2020.
When the SINTEC 4.100% Perpetual Corp (SGD) was announced at an IPG of 4.375% last year, the group’s EBITDA/Interest multiple was 4.4x in 2019. Gearing (total debt over total assets) was 43.4% in 2019.
With a lower EBITDA/Interest of 3.3x in 2020 and a higher group gearing of 44.1% in 2020, we would arguably expect a higher IPG. Even though 4.5% is higher than 4.375%, we think investors should receive higher compensation for the 1.1x drop in interest servicing ability and mild increase in gearing.
Investors have to note that ST Telemedia, albeit a Temasek subsidiary, remains a private issuer. Thus, there is no obligation to report financials on a frequent basis and there will be lower earnings visibility compared to publicly listed issuers. To illustrate this point, ST Telemedia published its 2019 financial statements only in June 2020.
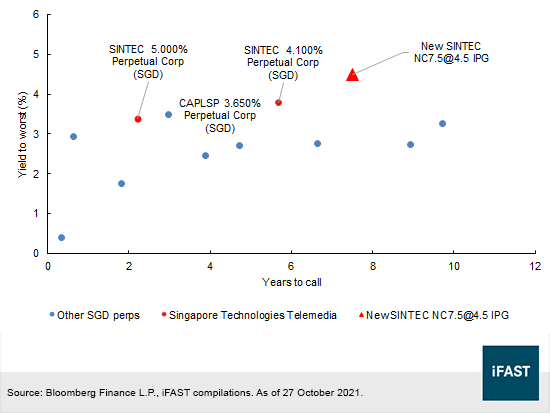
Having said that, the new SINTEC 4.5% IPG is attractively priced as it provides the highest potential yield when compared to other SGD perpetual bonds (Figure 3) issued by Temasek-linked companies. The new IPG has a 70 basis point pickup over the SINTEC 4.100% Perpetual Corp (SGD), which has a yield-to-worst (“YTW”) of 3.79% on 27 October 2021. It is also comparatively more attractive when compared to the SINTEC 5.000% Perpetual Corp (SGD), with a YTW of 3.39% and CAPLSP 3.650% Perpetual Corp (SGD) (YTW: 3.48%). CAPLSP 3.650% Perpetual Corp (SGD) is guaranteed by CapitaLand Limited, a company that is majority owned by Temasek Holdings.
Figure 3: Relative valuation among other comparable SGD perpetual bonds
Declaration: For or specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









