Singapore Technologies Telemedia Pte Ltd (“SINTEC”) is returning to the SGD bond market after issuing the SINTEC 5.000% Perpetual Corp (SGD) in January last year. The new perpetual note will be riding on SINTEC’s S$2 billion multicurrency debt issuance program dated 28 Jul 17. The order book for the new perps added to more than S$500m as of 11am today.
The new perpetual security pays noteholders on a semi-annual basis at the indicative rate of 4.375% (initial price guidance). The perp is first callable seven years later in 2027. If the issuer does not redeem the security on the first call date, the distribution rate would reset to the sum of the prevailing SGD Swap Offer Rate, the initial spread and a step-up margin of 1.00%. Other terms and conditions include a dividend stopper and a dividend pusher with a twelve-month look-back period.
Proceeds from the notes will used for SINTEC’s general corporate funding purposes or investments. These include acquisitions, refinancing of existing borrowings, capital expenditures and other general requirements.
About Singapore Technologies Telemedia Pte Ltd
With Temasek Holdings as its immediate and ultimate parent, SINTEC is an investment holding firm that is broadly focused in the provision of info-communications services. The group holds a number of subsidiaries, associates and joint ventures that deliver a diverse range of communications and information services to customers, including mobile telecommunications and networks, cable television streaming, data center co-locations, enterprise cloud and managed hosting services.
SINTEC has an indirect 41.8% stake in StarHub through its subsidiaries STT Communications Ltd (“STTC”), Asia Mobile Holding Company Pte Ltd and Asia Mobile Holdings Pte Ltd. STTC, a wholly owned subsidiary of SINTEC, owns STT GDC Pte Ltd (“STTGDC”), a data center operator that has a stake in GDS Holdings Limited. GDS is a Chinese data center solutions provider listed on the NASDAQ exchange, with a market capitalization of more than USD 12 billion.
Financials
Total revenue increased 5% YoY to S$4,132m in 2019, led by gains in enterprise fixed revenue and sales from data center co-location services (Table 1). Top-line contribution from its pay TV segment dropped 20% to S$248m.
Profit from operations, which took into account total revenue and operating expenses, jumped 283% to S$203m. But higher finance costs and lower results from its associates and joint ventures resulted in a net loss of S$140m in 2019. This was an improvement from 2018, when the company reported net loss of S$329m.
Table 1: Selected financials
|
|
2019 (S$ m) |
2018 (S$ m) |
Percentage change (%) |
|
Sale of equipment |
775 |
751 |
+3% |
|
Mobile revenue |
1,734 |
1,725 |
+1% |
|
Pay TV revenue |
248 |
311 |
-20% |
|
Broadband revenue |
176 |
186 |
-5% |
|
Enterprise fixed revenue |
574 |
509 |
+13% |
|
Data centres co-location services |
512 |
383 |
+34% |
|
e-Business solutions and consulting services |
23 |
||
|
Maintenance and installation services |
90 |
72 |
+25% |
|
Total revenue |
4,132 |
3,937 |
+5% |
|
Profit from operations |
203 |
53 |
+283% |
|
Finance costs |
-252 |
-168 |
|
|
Share of results of associates and joint ventures, net of tax |
-62 |
-39 |
|
|
Loss / profit for the year |
-140 |
-329 |
|
|
Source: Company, iFAST compilations |
|||
SINTEC recorded positive cash flows in 2018 and 2019. Cash flows from operating activities before changes in working capital increased from S$618m in 2018 to S$978m in 2019. Net cash from operating activities carried forward nearly doubled from S$497m to S$954m in the same period. However, after factoring in PPE purchases and payments for investments in associates and joint ventures, free cash flows would be negative S$520m in 2018 and negative S$505m in 2019.
The group has a manageable liquidity profile. Cash and cash equivalents of S$1,649m exceeded S$875m of current bank and other borrowings. Current assets over current liabilities were nearly 1.1x, which was a decent level as cash constituted nearly 60% of current assets.
SINTEC’s total debt load, defined as the value of perpetual securities, bank and other borrowings increased 55% YoY to S$5,674m. When expressed as percentage of total assets, the debt-to-total-asset ratio expanded from 35% in 2018 to 46% in 2019.
Approximately one-third of the group’s borrowings are secured by underlying assets, with unsecured and secured borrowings at S$2,704m and S$1,392m respectively. The secured borrowings are secured over certain assets including S$1,697m of property, plant and equipment, S$164m of cash, S$190m of receivables, S$43m of right-of-use assets and shares of certain subsidiaries.
Interest expense coverage ratios are low but improving. We estimated that EBIT, or earnings before taxes, finance costs and other expenses, nearly tripled from S$65m in 2018 to S$183m last year. SINTEC’s interest-servicing ability, calculated as EBIT over interest expense, improved from 0.6x to 1.3x over the same period.
Bond valuation
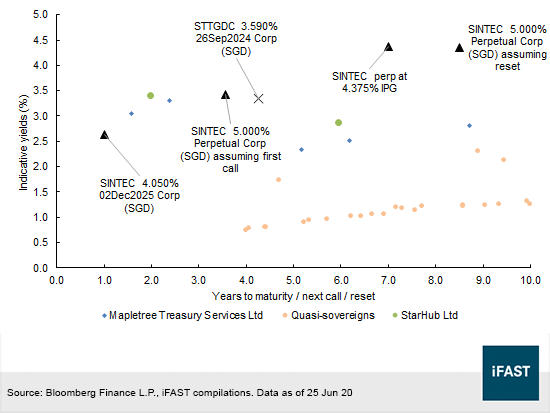
At the initial price guidance (“IPG”) of 4.375%, the new perpetual note is attractively priced as it would provide the highest yield among comparable notes (Figure 2). The pricing guidance surpasses that of the current yield to reset and yield to next call of the SINTEC 5% perp, and offers a generous yield pick-up over the SINTEC 4.050% 02Dec2025 Corp (SGD) and STTGDC 3.590% 26Sep2024 Corp (SGD). We commented on the STTGDC 3.59% ‘24s when they were launched last year.
Figure 2: Relative valuation (yields)
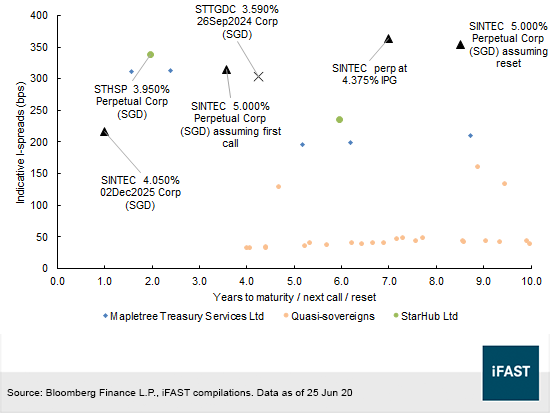
The valuation is also attractive from the perspective of I-spreads (credit spread over interpolated SGD swap rates). At ~363-basis point (“bps”) premium over the swap benchmark, the SINTEC 4.375% IPG perp is close to the STHSP 3.950% Perpetual Corp (SGD) (I-spread: 338bps) (Figure 3). STHSP or StarHub Ltd is an associate firm of SINTEC but we would prefer the latter’s credit profile for its larger revenue base and stronger institutional support.
Figure 3: Relative valuation (spreads)
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.