


- Suntec REIT (“SUNSP”) is an office and retail REIT managed by ARA Trust Management (Suntec) Limited.
- For the financial year ended 31 December 2021 (“FY21”), SUNSP saw gross revenues increasing 13.5% year-on-year (“YOY”) to SGD 358.1m.
- SUNSP’s retail performance was strong in the 2H21 with tenant sales and shopper traffic picking up especially towards the fourth quarter of 2021.
- We think SUNSP’s debt profile is decent with a weighted average debt maturity of 2.92 years.
After the acquisition of ARA Asset Management by ESR Cayman, Suntec REIT’s manager, ARA Trust Management (Suntec) Limited, a wholly-owned subsidiary of ARA Asset Management Limited, became part of APAC’s largest real asset manager.
About Suntec REIT
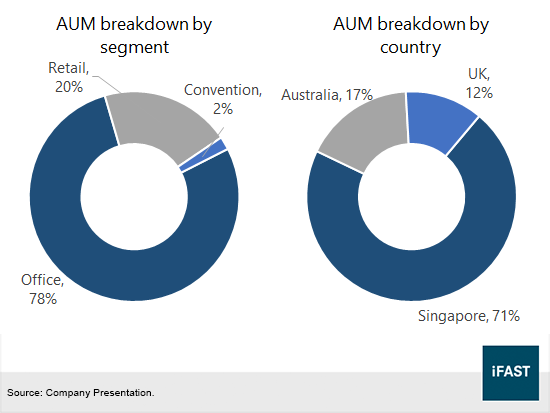
Suntec REIT (“SUNSP”) is an office and retail REIT managed by ARA Trust Management (Suntec) Limited, a wholly-owned subsidiary of ARA Asset Management Limited (“ARA”). After the merger with acquisition by ESR, ARA is part of the ESR Cayman Group, APAC’s largest real asset manager. SUNSP was listed on SGX-ST on 9 December 2004 and has a market capitalisation of SGD 4.6b as of 18 February 2022. Its portfolio consists of retail and office properties in Singapore, Australia and the UK.
Figure 1: SUNSP’s assets under management as at end December 2021
FY21 financial highlights
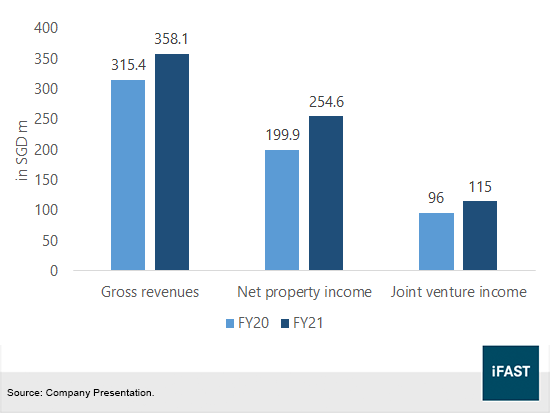
For the financial year ended 31 December 2021 (“FY21”), SUNSP saw gross revenues increasing 13.5% year-on-year (“YOY”) to SGD 358.1m. The increase in gross revenues was due to new contributions from The Minster Building acquired on 28 July 2021. SUNSP also reported higher contributions from 477 Collins Street and 21 Harris Street increased in FY21.
As a result, Net property income (“NPI”) increased by 27.4% YOY to SGD 254.6m in FY21, largely due to higher revenues from 377 Collins Street, 21 Harris Street, The Minster Building and as well as Suntec City Mall. NPI for SUNSP’s convention segment continues to report negative NPI, reporting a loss of SGD 5.35m in FY21.
The Meetings, Incentives, Conventions and Exhibitions (“MICE”) industry continues to be impacted by weak international business and leisure travel. The lack of events will continue into 2022 and is dependent on the further easing of restrictions on large-scale consumer and corporate events for its recovery. The management expects income from Suntec Convention segment to remain impacted for 2022.
Joint venture income for FY21 increased by 19.8% YOY to SGD 115.0m from new contribution from Nova Properties, partially offset by the divestment of 9 Penang Road. SUNSP holds a 50% stake in Nova Properties.
Figure 2: SUNSP FY 21 financial performance
Retail sales rebounded in 2H21
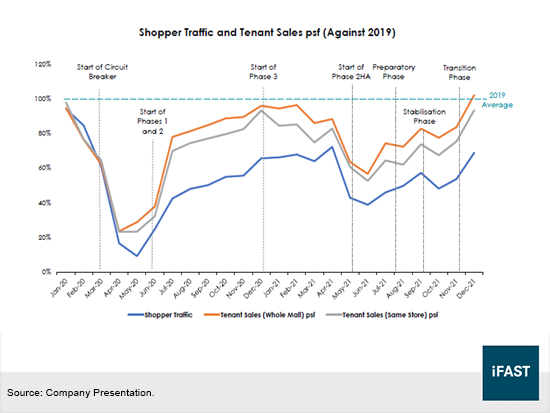
SUNSP’s retail performance was strong in 2H21 with tenant sales and shopper traffic picking up especially towards the fourth quarter of 2021. From Figure 3, shopper traffic in Suntec City Mall fell during Singapore’s Phase 2HA and during the Stabilisation Phase as dining in restaurants was only restricted to 2 persons. Retail traffic picked up at the end of 2021 as restrictions eased in Singapore as well as the holiday seasonality for retail during the festive Christmas period. In Figure 3, tenant sales psf are near 2019 averages during December 2021 as retail performance improved due to the easing of restrictions in Singapore.
Figure 3: Suntec City Mall shopper traffic and tenant sales
Overall portfolio occupancy rate at Suntec City Mall remained stable at 94.7% at the end of 2021, above the market occupancy rate of 94.0%. Rental reversions were negative throughout FY21, as Suntec City Mall lease renewals experienced a negative rental reversion of -14.4% in FY21.
SUNSP expects footfall and tenant sales at Suntec City mall to continue their recovery in 2022. While occupancy is expected to remain stable, rent reversion is likely to remain weak as retailers remain cautious due to the uncertain operating environment. Revenue recovery will be supported by higher occupancy and higher gross turnover rents.
Office segment remained strong
Office segment for SUNSP remained relatively strong. Total overall Singapore committed portfolio occupancy increased to 97.5%, higher than Singapore’s core CBD occupancy rate of 93.3%. Overall rent reversion for Singapore office segment was positive at 3.2%. SUNSP’s overseas office properties also remained strong. SUNSP’s Australia office portfolio occupancy rate of 94.2% was also higher than Australia’s CBD office average occupancy rate of 85.9%. In the UK, overall office occupancy rate was 98.3% comparing top Central London’s office occupancy rate of 92.0%.
Liquidity and credit profile
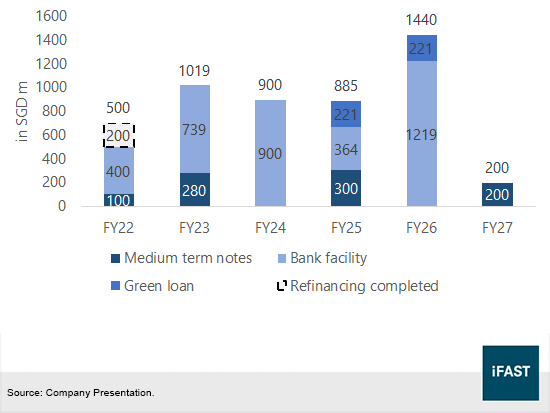
At the end of FY21, SUNSP had SGD 268.3m of cash and cash equivalents. Total borrowings for the trust was SGD 4.92b, of which SGD 499.8m are short term borrowings. The short term borrowings as at 31 December 2021 consists of SGD100m notes and outstanding amounts from SGD 600m loan facilities due in the next 12 months, of which, SGD 200m of borrowings had already been refinanced in November 2021.
SUNSP’s aggregate leverage ratio (taken as total borrowings and deferred payments to the value of the deposited property) for FY21 was 43.7%, a slight decrease from FY20 of 44.3%. Adjusted interest coverage ratio (calculated by dividing the trailing 12 months earnings before interest, tax, sinking fund contribution, depreciation and amortization by the trailing 12 months interest expense, borrowing-related fees and distributions on hybrid securities) was 2.6x.
We think SUNSP’s debt profile is decent with a weighted average debt maturity of 2.92 years. From Figure 4, SUNSP have about SGD 100m in medium term notes which they can pay off using the sufficient cash and cash equivalents on hand. The remaining SGD 400m can be refinanced using bank loans.
Figure 4: SUNSP’s debt maturity profile
Relative valuation
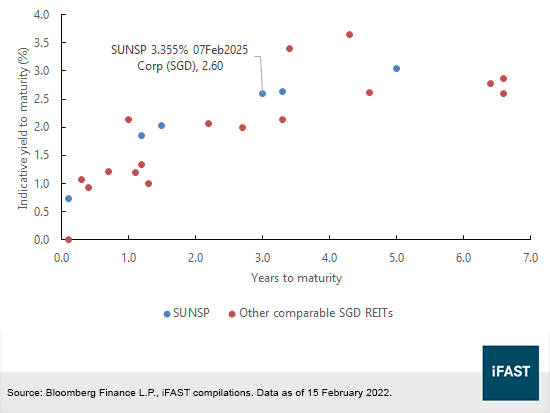
Comparing SUNSP’s fixed rate notes with other SGD fixed rate notes from other office and retail REIT issuers in Singapore (Figure 5), SUNSP’s notes are still trading above par and we think the SUNSP 3.355% 07Feb2025 Corp (SGD) offers more value against other SGD office and retail issuers. It has an indicative yield to maturity of 2.60% and matures on 7 February 2025.
Figure 5: Relative valuation of SUNSP fixed maturity notes against other SGD issues
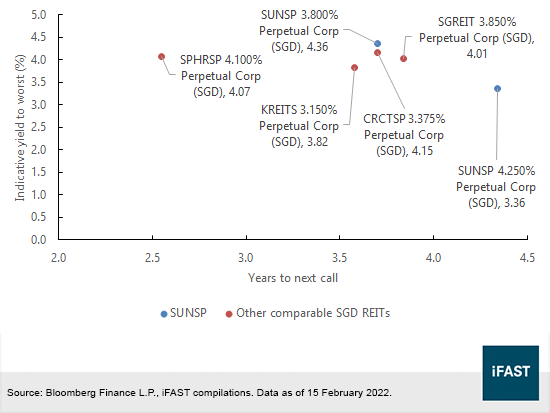
In terms of perpetual notes, most SGD REIT perps are trading below par, largely due to their sensitivity to interest rate changes. Among other SGD retail and office REIT perps, the SUNSP 3.800% Perpetual Corp (SGD) has an indicative yield to worst of 4.36% with about 3.7 years to its next call date. The 3.8% perps resets on 27 Oct 2025 and every 5 years thereafter at the prevailing SGD 5Y SOR (or the Successor Rate or Alternative Reference Rate) plus the initial spread of 3.295%. Investors should also note that future rate hikes may affect the yields on perps. This perpetual bond is also available on Bond Express, meaning qualified investors may purchase the perp in smaller lot sizes.
Figure 6: Relative valuation of SUNSP perpetual notes against other SGD issuers
Conclusion
SUNSP’s retail sales and traffic have largely improved especially in Suntec City Mall. Although rental reversions are expected to be weak, overall occupancy rate still remained stable and higher retail traffic will support revenue from gross turnover rents. One headwind for SUNSP would be its conventions segment as the MICE industry will continue to be impacted by the lack of business events and travel.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in SUNSP 3.800% Perpetual Corp (SGD), SPHSP 4.500% Perpetual Corp (SGD), KEPSP 2.900% Perpetual Corp (SGD) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









