Up to Date with Rates
- In the February meeting, the Reserve Bank of Australia (“RBA”) decided to leave the cash rate target unchanged at 4.35%. This decision marks the second time it opted to leave the key benchmark rate unchanged since November’s meeting. While inflation had eased, it remained high at 4.1% across 4Q23. Meanwhile, the Board’s priority continues to be taming inflation, back to the target range.
- In the recent February meeting, the Bank of Indonesia (“BI”) kept the benchmark interest rate at 6% for the fourth consecutive time. The Board indicated that the decision remains consistent with their current focus, which is to strengthen and stabilise the rupiah while maintaining inflation within their target range. The Indonesian Rupiah has outperformed the South Korean Won, Malaysian Ringgit and Thai Baht year-to-date, and moving forward, BI will continue to focus on rupiah stability.
- Across the past three weeks, the 2-year Singapore Overnight Rate Average-Overnight Index Swap (“SORA-OIS”) increased by 29 basis points to 3.200%, the 5-year SORA-OIS increased by 35 bps to 3.070% and the 10-year SORA-OIS increased by 32 bps to 3.065%.
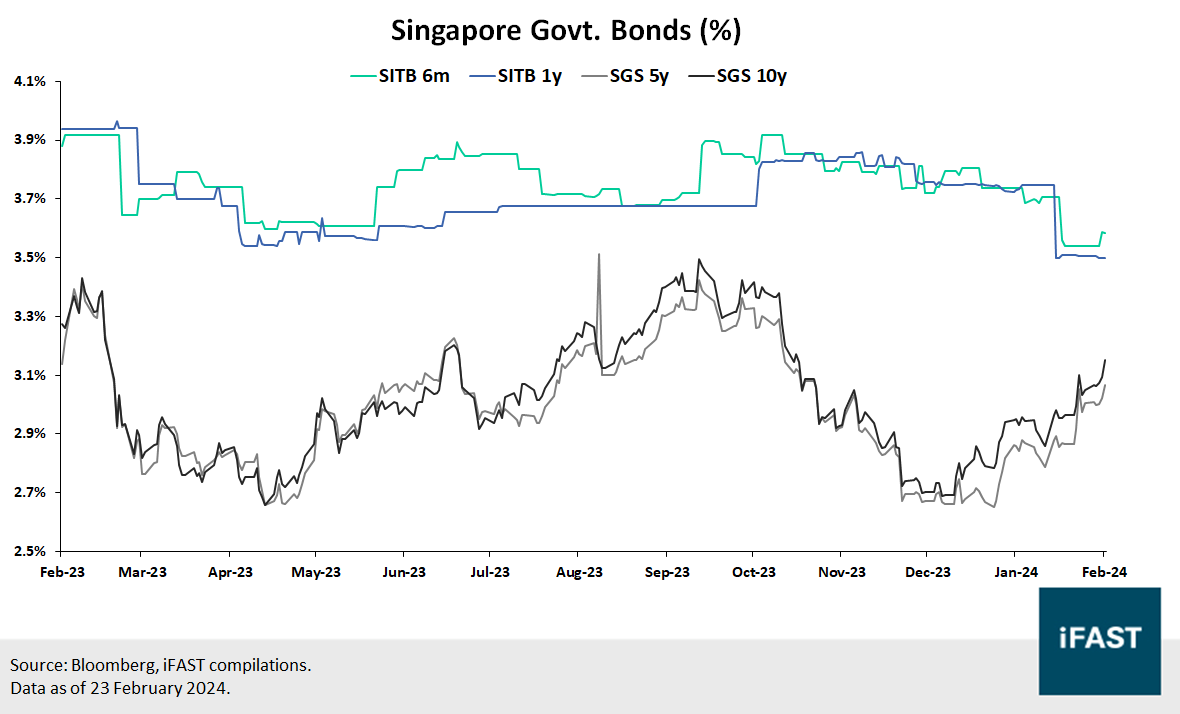
- Singapore treasury curve steepened over the same period. Benchmark yields
for the 6-month SGD T-bill fell by 12 basis points to 3.58%, while the 1-year
SGD T-bill fell by 25 basis points to 3.50%. The 5-year SGS rose by 28 basis
points to 3.07%, while the 10-year SGS rose by 29 basis points to 3.15%. For
the latest 6-month SGD T-bill auction, we saw a recovery of the cut-off yield
back to 3.66% alongside a drop in the bid-to-cover ratio to 2.05 times.


Favourite Bond Investment Ideas
- The Astrea VI Class A-1 bonds stand out among retail bond options for its relatively higher yield. We like the bond for its strong credit rating, which recently was upgraded by Fitch from ‘A+sf’ to ‘AA-sf’. Additionally, the bond is highly likely to be redeemed earlier on its mandatory call date of 18 March 2026, considering the current progress on the Reserve Account. With a bonus redemption premium of 0.5%, we think the bond will be a sweet deal for retail investors.
- STRTR 3.750% 29Oct2025 Corp (SGD) and STRTR 4.100% 04May2026 Corp (SGD) – Attractive yield and short-duration: the best of both worldsThe two highlighted bonds are our preferred picks for their attractive yields of above 4% while boasting short years to maturity. We find yields of both bonds as one of the highest within the short-duration SGD credit space. We expect STC to remain profitable and earnings to gradually rebound on the back of an improving macro backdrop. While STC might have seen a moderation in credit profile, it remains healthy due to a prudent leverage profile, strong liquidity and generally stable cash flow.
- We find the bond attractive, given a high yield to maturity of 4.92% at the ask price of 96.63 (as of 26 Feb 24). We expect an improvement in OUE Limited’s (“OUE”) earnings outlook with revenue projected to come from beyond real estate while the management of REITs should add to income stability. We also think OUE’s credit profile will stay decent in the short term, and the Group is unlikely to face any issues refinancing its debt.
- Olam Group Limited (“Olam”) recently released an announcement indicating that no evidence was found in the investigation of the alleged fraud case. Following this, we see opportunities in Olam’s 2026 paper which is backed by our previous positive view on the Group’s credit profile and earnings outlook. Beyond the near term, we expect earnings to recover and for the credit profile to gradually improve from here.
Hot New Issues
Table 1
New
issuances over the past three weeks
|
Issue |
Issuer |
Issuance Date |
New Issue View |
|
BNP Paribas SA |
15 February 2024 |
BNP Paribas announces 10NC5 SGD Tier 2 subordinated bond at IPG of 5.10% |
|
|
UBS Group AG |
21 February 2024 |
||
|
Singapore Exchange Limited |
26 February 2024 |
Singapore Exchange announces new 3Y senior unsecured SGD notes at the IPG of 3.60% |
|
|
Sources: Bondsupermart, iFAST Compilations. |
|||
Corporate Updates You Should Know
- 7 February – City Development Limited (“CDL”) announced the acquisition of Yardhouse, its first Private Rented Sector (“PRS”) development in Central London, United Kingdom. The acquisition is valued at approximately SGD 148.6m. CDL will forward-fund this project and is expected complete in 2026.CDL expects to further expand on its UK living sector portfolio, in various cities and leverage on the rising demand for rental accommodation. On top of the PRS projects, CDL has close to 2,400 beds in the Purpose-Built Student Accommodation Sector. Beyond the UK market, CDL sees opportunities in Japan and Australia. Previously in September 2023, it had invested JPY 35b into a residential rental portfolio in Tokyo, Japan.
- 8 February – Oxley Holdings Limited (“Oxley”) released the financial results for the half year ended 31 December 2023 (“1H24”) and our comments on results can be found here. With the continued loss in 1H24, we see a slight deterioration in its credit profile. However, with Oxley’s ability to tap into secured borrowings and some cash inflow from projects sold in FY24, we believe a default on OHLSP 6.900% 08Jul2024 Corp (SGD) remains unlikely.
- 14 February – Azalea Investment Management (“Azalea”) announced that Fitch Ratings have upgraded the ratings of several Astrea bonds. Among the bonds, Astrea V Class B bonds have been upgraded to ‘A+sf’; Astrea VI Class A-1 and Class B bonds have been upgraded to ‘AA-sf’ and ‘Asf’ respectively; and Astrea 7 Class B bonds have been upgraded to ‘A-sf’.Fitch highlighted that the upgrades of Astrea V and VI Class B bonds were due to their current Loan-to-Value (“LTV”) ratios, which allows for a larger decline in the respective NAVs without affecting their ratings. For Astrea VI Class A-1 bonds, the upgrade was due to the accumulated reserves amount, which has exceeded the outstanding principal amount. For Astrea 7 Class B bonds, the upgrade was also due to the prevailing LTV levels, helping the bonds pass Fitch’s cash flow scenarios.
- 15 February – Singapore Airlines Limited (“SIA”) announced an improvement in operating figures for January 2024. The Group’s passenger capacity has increased by 16.5% YoY, while passenger traffic grew by 14.4% YoY. Overall, it carried a combined 3.2 million passengers in January, an increase of 23.1% YoY. Meanwhile, SIA’s 3Q23 results (for the quarter ended 31 December 2023) showed that revenue continues to come in stronger QoQ. Despite significantly higher operating expenses due to higher fuel and non-fuel costs, results for the first nine months still came in strong. With stellar financial performance across 9M23, we expect a record profit for FY23.
- 19 February – Olam Group Limited (“Olam”) announced that it has completed the investigation concerning Olam Nigeria and its subsidiaries and reported no evidence that establishes the allegations (Previously in September 2023, Olam Nigeria was accused of its alleged involvement in a foreign exchange fraud case). Given the positive news, we maintain our optimistic view about the Group and see the Olam 2026 paper as a good opportunity amidst current market conditions. For more information, we have provided a short commentary on Olam’s current situation, which may be found here.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in STRTR 3.750% 29Oct2025 Corp (SGD) and STRTR 4.100% 04May2026 Corp (SGD), and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!