UOL Treasury Services Pte. Ltd., a subsidiary of UOL Group Limited (“UOL”) is proposing to issue new bonds under its SGD 2 billion multicurrency Medium Term Note (“MTN”) Programme. The bonds have an initial price guidance (“IPG”) of 2.5% and will mature in August 2028.
About the senior unsecured bonds
According to the terms of the offering, UOL Treasury Services Pte. Ltd. (the issuer) may redeem the bonds in whole and not in part for taxation reasons. Additionally, bondholders have the option to sell back their holdings to the issuer and guarantor if UOL ceases to be listed on the Singapore Exchange.
Under the covenants of the MTN programmes, the group is required to maintain a gearing ratio of not exceeding 200% (i.e. total borrowings to tangible net worth less than 200%). Additionally, the group’s consolidated tangible net worth should not fall below SGD 1.8 billion at any point in time.
About the guarantor
UOL is the guarantor of the bonds. All sums payable in respect of the notes are unconditionally and irrevocably guaranteed by UOL Group Limited. Dr Wee Cho Yaw is the Chairman of UOL, United Industrial Corporation and United Overseas Bank, Singapore’s third largest bank by assets.
Since its incorporation in 1963 and public listing in 1964, UOL has created a property development and hotel operation track record of more than 50 years. Its subsidiary, Pan Pacific Hotels Group Limited operates three well-known hospitality brands - Pan Pacific, PARKROYAL COLLECTION and PARKROYAL.
Geographically, the group covers a footprint that stretches across 14 countries including China, the United States and Canada. Under its hospitality arm, UOL owns and/or manages over 30 hotels with more than 10,000 rooms. A Straits Times Index constituent, the group has a market capitalization of close to SGD 6 billion on 24 August 2021 and recorded SGD 20.7 billion of total assets as at 30 June 2021.
The group’s property portfolio is made up of investment properties, development properties and hotel properties.
Investment properties comprise of commercial buildings and serviced suites in Singapore, Malaysia, Australia, China and London. UOL is presently in the midst of constructing the PARKROYAL Serviced Suites Jakarta and PARKROYAL COLLECTION Kuala Lumpur.
Through its 50.37% interest in Singapore Land Group Limited, the company has an interest in a number of commercial properties in Singapore including Singapore Land Tower, Marina Square shopping mall, West Mall and SGX Centre 2.
As of 30 June 2021, the ongoing residential development projects in Singapore consist of The Tre Ver, MEYER HOUSE, Avenue South Residence, Clavon and The Watergardens at Canberra. UOL also has a project site at Ang Mo Kio Avenue 1 and unsold units at V on Shenton and Mon Jervois.
Hotels are mostly wholly-owned by the group with the exception of Pan Pacific Singapore (60.56%), PARKROYAL COLLECTION Marina Bay (71.17%), The Westin Tianjin (25.69%), Tianjin Yanyuan International Grand Hotel (18.13%), Pan Pacific Hanoi (75%), Mandarin Oriental (30.78%), Sofitel Saigon Plaza (25.58%) and Pan Pacific Yangon (40%).
Financial highlights and credit discussion
Group revenue is recognized through 6 different segments – property development, property investments, hotel operations, technology operations, management services and investments.
Figure 1: Revenue by business segment
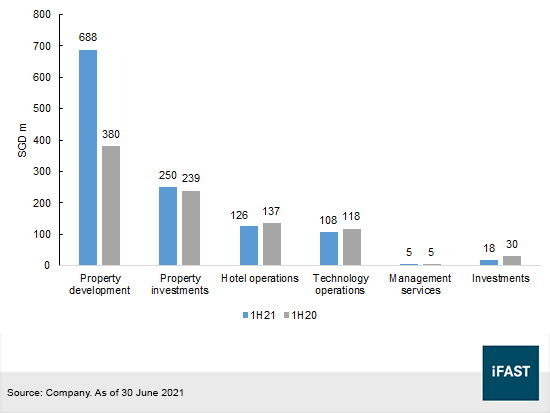
As seen in Figure 1 and considering the 6-month period ended 30 June 2021 (“1H21”), revenue from property development increased by 81% on higher progressive recognition of revenue from Avenue South Residence, The Tre Ver and Clavon offset by lower revenue from Amber45, V on Shenton and Park Eleven, Shanghai.
Property investment revenue improved slightly by 5% as lower rental rebates were granted to tenants during 1H21. Revenue from hotel operations dropped by SGD 10.8m in 1H21 as the hospitality sector is still reeling from the pandemic. Contributions from the Singapore Government Quarantine Facility contracts have dropped but the company said that the hotels in China are seeing recovering tourism activity.
As a result of higher revenue and lower finance expenses, UOL made a profit of SGD 154.1m in 1H21 as opposed to a SGD 94.8m loss in 1H20.
The group has a healthy liquidity profile with SGD 1.17 billion of cash and SGD 2.6 billion of unutilized credit facilities, which it may use to cover its SGD 2.39 billion of current bank loans. Total debt added to SGD 5.28 billion with SGD 3.70 billion of debt maturing within the next two years. With just SGD 38m of debt maturing in more than three years, UOL has an average debt maturity of 1.2 years. However with the completion of this bond offering, the average debt maturity should be extended.
UOL has a strong ability to service interest expense and maintains a comfortable gearing position. Its gearing ratio, defined as net debt over total equity was 29% in June. Our debt to total asset estimate approximates to ~24.5% as at 1H21 and that is close to the ~24.3% ratio in 1H20. Furthermore, UOL has a healthy interest cover (including capitalized interest) of 12x. With an estimated EBITDA of ~SGD 301.2m, we think its EBITDA/Interest multiple excluding capitalized borrowing costs) is around ~8.7x in 1H21 and ~5.5x in 1H20.
Pricing comments
Notwithstanding its healthy credit metrics and good liquidity indicators, we do not think that the new 7Y SGD bonds from UOL are attractively priced. With an IPG of 2.5%, the bonds are priced at 130 basis points (“bps”) above the 7-year SGD Swap Offer Rate (“I-spread”). As of 24 August 2021, the UOLSP 3.000% 23May2024 Corp (SGD) have an I-spread of 117.2bps at 103.2 cents on the dollar. We feel that the minuscule credit spread difference of 12.8bps do not adequately compensate investors for the 4.2 years difference in bond tenors.
Figure 2: Relative valuation of non-bank SGD bonds with comparable maturities
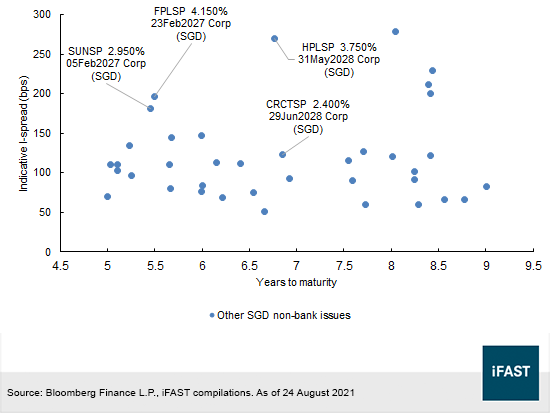
Among the other alternatives for investors, we think that the CRCTSP 2.400% 29Jun2028 Corp (SGD) issued by CapitaLand China Trust would be more attractive at its I-spread of 123.7bps. The SUNSP 2.950% 05Feb2027 Corp (SGD) and FPLSP 4.150% 23Feb2027 Corp (SGD) also have higher credit spreads with shorter maturities compared to the 7-year IPG from UOL. For more information on these issuers, kindly refer to “Suntec REIT launches new SGD NC5 perps at 4.45% IPG” on SUNSP (Suntec REIT) and “Frasers Property’s perps look attractive within real estate space” on FPLSP (Frasers Property Limited).
Investors with a higher risk appetite may consider the HPLSP 3.750% 31May2028 Corp (SGD). Hotel Properties reported better than expected results on 12 August 2021. Revenue increased from SGD 144.8m in 1H20 to SGD 169.6m in 1H21 while loss after tax narrowed from SGD 79.0m to SGD 19.1m in the same period. The issuer’s cash position of SGD 78.9m adequately covers its short-term debt of SGD 60.9m so group liquidity remains satisfactory. If required, we assume that Hotel Properties will divest its SGD 681.3m of investment properties and part of its SGD 1.60 billion of property, plant and equipment to repay borrowings.
Declaration: For or specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in SUNSP 3.800% Perpetual Corp (SGD) and FPLSP 4.980% Perpetual Corp (SGD). The analyst who produced this report is a unitholder of CapitaLand China Trust.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!