Announced on 31 December 2021, MCT will acquire all the issued and paid-up units in MNACT for a total scheme consideration of SGD 4.215b.
When completed, the new merged entity will be renamed to Mapletree Pan Asia Commercial Trust (“MPACT”). The merger will leapfrog the REIT into the top 10 REITs in Asia by market capitalisation.
MPACT would have a total of 18 commercial properties across 5 countries in Asia with a total assets under management (“AUM”) of SGD 17.1b.
In view of an enlarged REIT and lower single asset exposure by AUM and NPI, we continue to maintain our recommendation on the MAGIC 3.500% Perpetual Corp (SGD) with an indicative yield to worst (“YTW”) of 3.96%.
Mapletree Commercial Trust (“MCT”) and Mapletree North Asia Commercial Trust (“MNACT”) ended 2021 with a surprise by announcing a proposed merger with MCT acquiring all of MNACT’s units.
This announcement is one of the major acquisitions that was announced in 2021, along with the announcement of ESR’s acquisition of ARA Asset Management for USD 5.2b. We will take a dive into the announcement and provide our recommendations for bondholders on the proposed merger.
About the proposed merger
MCT is proposing to merge with its sister REIT, MNACT, by way of a trust scheme arrangement. Announced on 31 December 2021, MCT will acquire all the issued and paid-up units in MNACT for a total scheme consideration of SGD 4.215b. The total cash consideration will not make up more than SGD 417.3m in cash (~9.9% of the total scheme consideration).
MCT proposed to offer two scheme consideration options for MNACT unitholders – a) a scrip-only consideration where 0.5963 new units in MCT will be exchanged for every unit of MNACT; or, b) a cash-and-scrip consideration where a combination of 0.5009 MCT Units and SGD 0.1912 in cash will be paid for every unit of MNACT.
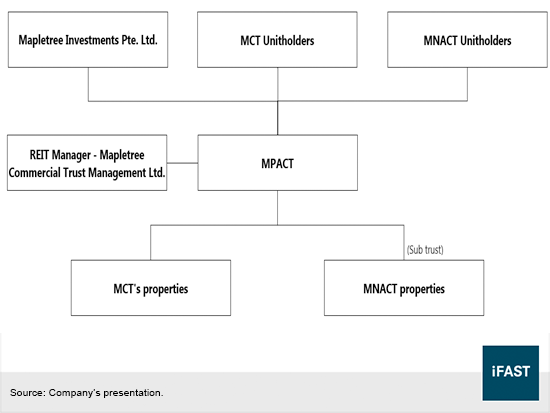
When completed, the new merged entity will be renamed to Mapletree Pan Asia Commercial Trust (“MPACT”). The merger will leapfrog the REIT into the top 10 REITs in Asia by market capitalisation. MNACT will be a sub-trust under the merged entity’s structure as seen in Figure 1.
The merger is expected to be completed by June 2022 and payment of scheme consideration to MNACT unitholders by early June 2022. The timeline however is indicative and is subject to changes.
Figure 1: Merged entity's structure
Combined property assets
When completed, MPACT would have a total of 18 commercial properties across 5 countries in Asia with total assets under management (“AUM”) of SGD 17.1b. As seen in Figure 2, Singapore assets will make up 51.4% by AUM while Hong Kong SAR, China, Japan and South Korea will represent 26.0%, 10.8%, 10.2% and 1.6% respectively.
MCT has 5 assets in Singapore with an AUM of SGD 8.8b. Its properties are situated mainly within the Greater Southern Waterfront region such as VivoCity, Mapletree Business City 1 & 2, mTower and Bank of America Merrill Lynch Harbourfront. Mapletree Anson is located within the central business district of Singapore.
MNACT has 13 assets across the north Asia region and has an AUM of SGD 8.3b. Examples of some of its properties include Festival Walk in Hong Kong SAR, Gateway Plaza in China and The Pinnacle Gangnam in South Korea.
Mapletree Investments Pte. Ltd. (“MIPL”) is the sponsor for both REITs, holding 32.6% interest (including indirect interest) in MCT and 38.1% interest (including indirect interest) in MNACT. MIPL is a real estate development, investment, capital and property management company in Singapore. It is 100% indirectly owned by Temasek Holdings Limited via its wholly-owned subsidiary Fullerton Management Pte Ltd. MIPL will opt-in to receive a script-only consideration for the merger.
Figure 2: Merged entity's AUM
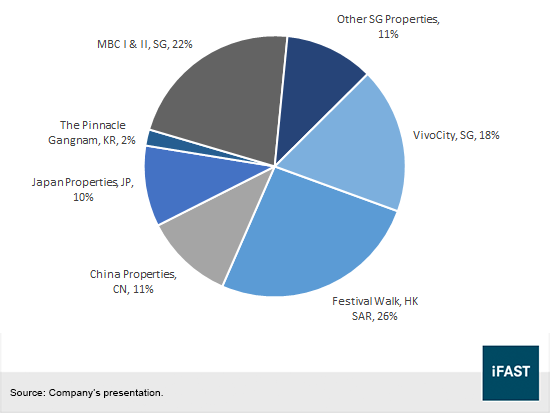
The enlarged portfolio will reduce single asset concentration risk within the REIT’s asset portfolio. Currently, MCT’s exposure to MBC I & II is 43.4% of its AUM while MNACT has a 53.5% exposure to Festival Walk by AUM. After the merger, MBC I & II exposure will reduce to 22% (see Figure 2) while also reducing Festival Walk’s exposure to 26% (Figure 2). As a result, the combined entity will not have more than 26% exposure by AUM to any single asset.
Additionally, single asset contribution by pro forma net property income (“NPI”) will reduce to 24.3% as compared to MCT’s current 46.0% exposure to MBC I & II and MNACT’s 47.6% exposure to Festival Walk.
Overall, the enlarged portfolio is generally positive for both MCT and MNACT as their NPI exposure will significantly be reduced, lowering its exposure risk to a single asset in their portfolio. The combined entity should be able to diversify some of the single country risks although Singapore assets still make up more than 50% in AUM.
However, pro forma aggregate leverage as at 30 September 2021 is expected to increase after the merger. Pro forma aggregate leverage was 33.7% before the merger, but will increase to 39.2% assuming all unitholders receive a cash-and-scrip consideration. On the other hand, pro forma aggregate leverage will increase to 38.0% if unitholders choose a scrip-only payout.
9M21 Financial Results
For the 9 months financial results ended 31 December 2021 (“9M21”), MCT reported gross revenues of SGD 374.0m, an increase of 7.3% from 9M20. NPI also increased 5.6% to SGD 291.3m. This was due to lower rental rebates given to tenants and as well as higher compensation received from lease pre-terminations.
MNACT reported SGD 328.0m of gross revenue for 9M21, a 12.8% increase from 9M20. NPI saw 14.9% increase to 247.4m in 9M21. The increase in NPI was due to lower rental reliefs for Festival Walk and also contribution from the Hewlett-Packard Japan Headquarters which was acquired on 18 June 2021. Although NPI increased in 9M21, average rental reversion for Festival Walk and Gateway Plaza saw a 32% decrease for 49 retail leases and 25% decrease for 18 leases respectively.
Liquidity and credit profile
For 9M21, MCT reported cash and cash equivalents of SGD 48.8m as well as SGD 3.0b of borrowings. Gearing ratio (total borrowings divided by total assets) was 34.1%.
MNACT had SGD 224.3m in cash and cash equivalents, and SGD 3.5b in total borrowings. Aggregate leverage for MNACT, measured in accordance with the Property Funds Guidelines, was 42.1%.
As mentioned, the merged entity will have a gearing of 39.2% in a cash-and-scrip scenario. The merger will be credit negative for MCT as it takes on a more leveraged REIT while credit positive for MNACT as the merger will allow MNACT to lower its gearing.
The debt funding capacity for the combined entity will increase to SGD 3.8b which will allow MPACT to take on more debt for future acquisitions and unlock more value for MCT in the North Asia region. We think even though the transaction is expected to increase MCT’s leverage, the merger will allow MCT to explore acquisitions outside of Singapore and continue to grow the REIT through acquisitions in the North Asia region.
Recommendation
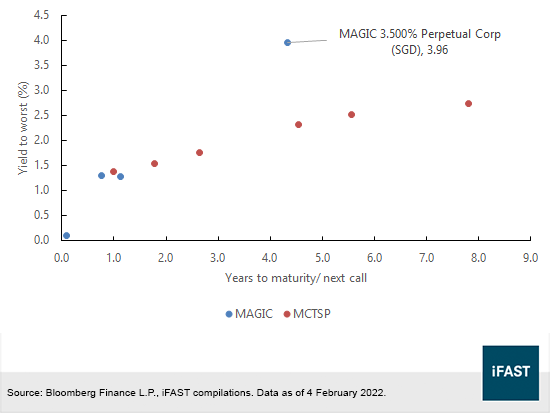
In view of an enlarged REIT and lower single asset exposure by AUM and NPI, we continue to maintain our recommendation in MAGIC 3.500% Perpetual Corp (SGD) with an indicative yield to worst (“YTW”) of 3.96%.
Additionally, MNACT will be less leveraged when merged with MCT as well as increasing the REIT’s exposure to Singapore assets, while diversifying from the North Asia region. Among other fixed rate notes from MNACT and MCT, as seen from Figure 3, the spreads between MAGIC and MCTSP have largely converged and are trading within the same yield curve.
Figure 3: MCT and MNACT bonds
Conclusion
All in all, we think the merger will be beneficial to both MCT and MNACT, the merger allows both REITs to tap into the markets of each respective REIT, allowing for more NPI growth through future acquisitions. We continue to maintain our recommendation in MAGIC 3.500% Perpetual Corp (SGD) as leverage for MNACT will be reduced significantly after the proposed merger.
Declaration:For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in MLTSP 3.725% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!