Henderson Land Development Company Limited (hereinafter referred to as "Henderson Land") is one of Hong Kong's major property developers. It is primarily held by a family trust established by the late former chairman, Mr. Lee Shau-Kee, holding approximately 72.8% of the shares. Currently, its two sons, Martin Lee and Peter Lee, serve as joint chairmen of the board. Henderson Land's business is highly diversified, including property development and leasing, hotels, and retail. We previously analysed Henderson Land's bond investments; for details, please see "IOTW: With Henderson Land's Major Projects Nearing Completion, is its 4.7% yield Bond a Good Choice?". Henderson Land recently announced its interim results for 2026, which will be analysed in this article.
Thanks to government land acquisitions, Henderson Land's revenue and profit excelled
Henderson Land Development's revenue for the first half of 2026 was strong, surging 64.4% YoY to HKD 17.2 billion. Driven by the government's acquisition of agricultural land in the New Territories, Henderson's property development segment recorded HKD 12.9 billion, more than doubling YoY. Total contracted sales amounted to HKD 18.5 billion, up 145% YoY. While the mainland segment only reached HKD 340 million (a 73% YoY decrease in HKD terms), the Hong Kong segment recorded HKD 18.1 billion (a 188% YoY increase), becoming the growth driver. In terms of profit, the Group's pre-tax profit more than doubled to HKD 5.4 billion; net profit also increased significantly by 41% YoY to HKD 4.1 billion. Even though the net profit margin declined, we believe this was due to the high base effect caused by the Group's land sales. After overcoming the challenges of the pandemic, Henderson Land is accelerating its recovery by converting its land resources into actual revenue.
Chart 1: Henderson Land's Revenue Performance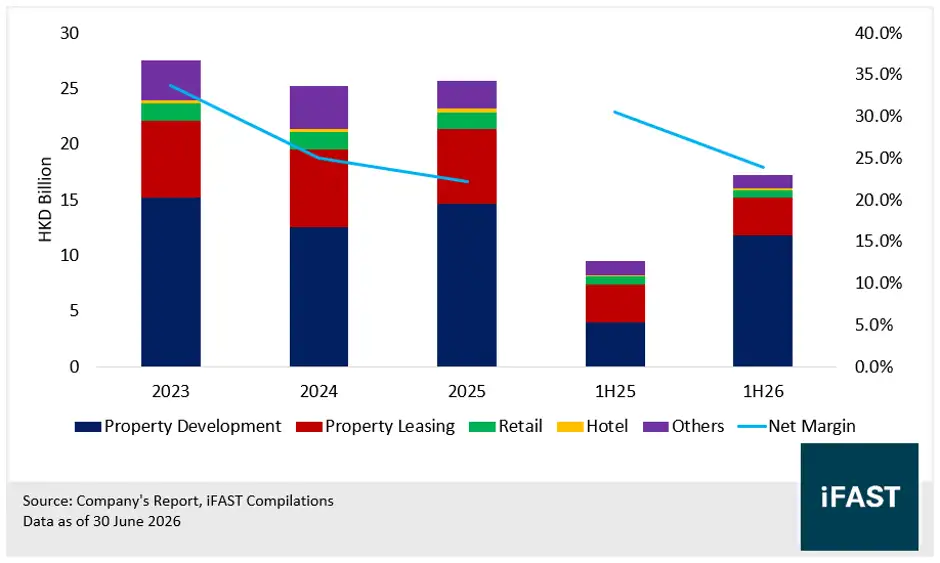
Henderson Land's adequate land reserves keeps generating revenue for the group
Henderson Land's unsold units have a saleable area of 1.3 million square feet, a 15.2% decrease compared to the end of 2025. It plans to launch eight new projects in the second half of the year, bringing the total to approximately 3,400 residential units in inventory. Looking at leasing, Henderson Land's supply remains sufficient. The Central Yards project, a prime location on the Central waterfront, has a total gross floor area of approximately 1.6 million square feet. Phase 1, approximately 750,000 square feet, is expected to be completed in the fourth quarter of this year. Jane Street has already leased over 223,000 square feet, accounting for around 70% of the office and supporting facilities in Phase 1. Phase 2, about 860,000 square feet, is targeted for completion by 2032. Upon completion of Phase 1, the total leasable area of properties in Hong Kong is expected to expand to approximately 11.5 million square feet.
As of the second quarter of 2026, Henderson Land's agricultural land reserves in the New Territories amounted to approximately 38.4 million square feet, a slight decrease of 5.2% compared to the end of 2025. About 90% of these reserves are located in the Northern Metropolis, with a book value of approximately HKD 9.5 billion and an average cost of approximately HKD 246 per square foot. In the first half of the year, approximately 2.2 million square feet of land in San Tin were reclaimed, generating approximately HKD 2.2 billion in revenue. We believe the value of agricultural land lies in two pathways: "replenishing land reserves" and "cash from government land acquisitions," rather than immediately saleable floor area. As the government continues to vigorously promote the "Northern Metropolis" plan, we believe Henderson Land will have more land reclaimed in the future, thus generating more revenue.
Henderson Land's credit remains robust, providing a guarantee for its bonds
As of June 2026, Henderson Land's net debt was approximately HKD 58.4 billion, a 3.0% decrease from the end of 2025 (see Table 1). Short-term debt was approximately HKD 7 billion, and while cash reserves slightly decreased to HKD 21.5 billion, they remained sufficient to cover its needs. Furthermore, the weighted average debt maturity was approximately 3.8 years, avoiding excessive concentration of debt. Contracted equity capital commitments amounted to approximately HKD 8.2 billion, and bank credit lines were sufficient to cover these commitments.
Table 1: Henderson Land Credit Metrics
HKD Billion | 2H25 | 1H26 |
Cash Reserve | 22.2 | 21.5 |
Net Debt* | 60.2 | 58.4 |
Net Gearing* (%) | 18.4 | 17.9 |
Interest Coverage Ratio (x) | 3.0 | 3.2 |
* Excluding the borrowing from Li family trust fund Data Source: Company’s Report, iFAST compilations Data As Of 30 June 2026 | ||
As we mentioned before, Henderson Land had a debt of up to HKD 80.6 billion owed to its major shareholder, the Li family trust fund, for the acquisition of land in Central Yards. As of the first half of 2026, this debt had decreased by 4.5% to HKD 77.0 billion. This demonstrates that Henderson Land Development is still making efforts to reduce its debt and is not overly reliant on the Lee family.
Bond Investments
Henderson Land does not have public issuer ratings from S&P or Fitch; therefore, asset quality and cash flow are crucial. We believe that the net yields to maturity of the two bonds, one in US dollars and the other in Hong Kong dollars, are competitive among their peers and worth continued attention for investors seeking stable returns. The yields on both bonds have risen by 10 to 20 basis points in the past month, allowing investors to lock in returns through further strengthening of the group's profitability and credit.
Tabel 2: Henderson Land Bonds
Bond | Tenor | Net Ask YTM |
2.5 | 5.2% | |
6.7 | 4.5% | |
Data Source: FSM Global Data As Of 14 September 2026 | ||
Related Risks
Property sales confirmation progress is influenced by Hong Kong property prices and transaction volume. The HKD 7 billion in signed but not yet booked sales must be successfully completed and handed over in the second half of the year before it can be recognized. If sales are slower than expected, the core profit base will decline.
Office vacancy and rents in mainland China remain sources of pressure. The occupancy rate of the Beijing World Financial Centre office building is only around 60%. The operating profit margin of mainland property development business in the first half of 2026 is expected to be negative 42%, and mainland land reserves are also shrinking YoY.
Fluctuating interest rate paths will lead to a rise in refinancing costs. Although loans from affiliated subsidiaries do not have fixed repayment periods, they are interest-bearing liabilities, and interest expenses will still erode cash flow. The second phase of Central Yards will not be completed until 2032, and rental growth is not linear.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold NIL positions in the abovementioned securities. This research report was prepared with the assistance of artificial intelligence (AI) tools. iFAST Financial Pte Ltd does not rely exclusively on AI for content generation; the content of this report – including all investment theses, ratings, price targets and conclusions – has been independently reviewed and verified by the research analyst(s) to ensure accuracy and professional integrity.