High yield issuers such as Tuan Sing Holdings and Oxley Holdings have been issuing new notes following their debt tender offers this year. Chip Eng Seng (“CHIPEN”) has asked its 2022 bondholders to exchange their holdings for new bonds maturing in 2024. This morning, the company announced its intent to increase the issuance size of the CHIPEN 6.500% 06Dec2024 Corp (SGD).
About the additional notes
Additional notes from this bond offering will be consolidated with the CHIPEN 6.500% 06Dec2024 Corp (SGD). As of yesterday, the CHIPEN 6.5% 2024’s had an issue size of SGD 71.25m. This was a result of the tender offer, where bondholders representing SGD 10.25m of the CHIPEN 4.900% 19May2022 Corp (SGD), and SGD 61.00m of the CHIPEN 6.000% 15Mar2022 Corp (SGD) had offered to exchange their holdings.
Accordingly, the offered notes maturing in 2022 will be cancelled on their settlement date, leaving the CHIPEN 4.900% 19May2022 Corp (SGD) with an outstanding amount of SGD 15.00m, and CHIPEN 6.000% 15Mar2022 Corp (SGD) with an outstanding amount of SGD 39.00m.
Concurrently, nearly 44.60% of the SGD 71.25m new bonds - CHIPEN 6.500% 06Dec2024 Corp (SGD) have been allocated to certain directors and controlling shareholders of the company. These insider holdings increases the repayment likelihood of the new bonds.
According to the terms of the SGD 750m Multicurrency Debt Issuance Programme, the bonds may be redeemed at par for taxation reasons, or if the company’s shares have stopped or suspended trading. Additionally, the bonds may be redeemed in a change of control event where the controlling shareholders cease to own at least 20% of the company, or if more than 30% of the shares are acquired by third parties.
About the guarantor
The CHIPEN 6.500% 06Dec2024 Corp (SGD) are guaranteed by Chip Eng Seng and issued by CES Treasury Pte. Ltd, which provides financial and treasury services to the CHIPEN group.
CHIPEN is mainly involved in (i) property development, (ii) construction, (iii) hospitality, (iv) property investment and (v) education. The group’s operations are geographically diversified in the Asia Pacific region, with a key focus on Singapore, and they hold strategic presences in Australia, Maldives, Hong Kong SAR, Malaysia, Vietnam, New Zealand and Cambodia.
Financial and credit discussion
Referring to the 6-month period ended 30 June 2021 (“1H21”), CHIPEN more than doubled its revenue to SGD 622.42m in 1H21 from SGD 289.97 in 1H20. The company made a profit after tax of SGD 9.18m, up from a loss of SGD 25.68m in 1H20. Following its recent guidance, the group is on track to make a net loss for the financial year ending 31 December 2021. However, the net loss this year will be significantly smaller compared to the preceding year ended 31 December 2020 (“FY2020”).
Within its property development division, CHIPEN recorded brisk sales from its three residential Singapore projects – Park Colonial, Parc Komo and Kopar at Newton, which have achieved a sales rate of 100%, 80.1% and 58.2% respectively. Looking ahead, the group is cautious about acquiring land plots but did announce its plan to redevelop the Maxwell House into a commercial and residential mixed development. As of 30 June 2021, the developer has SGD 788.50m of development properties that are designated as current assets. (Tuan Sing: SGD 260.59m; Oxley: SGD 1953.90m)
Construction also performed better this year in spite of the lengthy and intermittent work stoppages due to Covid-19, resulting in a construction order book of SGD 1.49b as at 30 September 2021. HDB awarded CHIPEN to build Pasir Ris Neighbourhood 5 Contract 26 & 27, and replaced the contractor for the BTO project at Marsiling Grove in Woodlands.
In July 2021, the People’s Republic of China imposed new regulatory measures on the tuition industry. As such, CHIPEN’s investment in Yuanda Information Development Co. Ltd (“Yuanda”) was affected due to Yuanda’s key business segment in online and onsite tuition. CHIPEN’s other education ventures in China are not involved in tuition but have been negatively impacted due to the uncertainty surrounding China’s regulatory measures in the education sector. However, CHIPEN’s revenue from education in China only make up approximately 0.1% of its total revenue, and thus does not have a large impact on CHIPEN’s financial results.
Estimated group EBITDA was ~SGD 44.81m in 1H21, and that is ~2.76x its interest expense, which means that CHIPEN has a healthy interest servicing ability. This was probably higher than its peers in 1H21 (Tuan Sing: ~1.79x, Oxley: ~2.12x).
Similar to its property developer peers, the gearing ratios for CHIPEN is high with debt to total assets of 52.83% at 1H21 (Tuan Sing: 48.79%, Oxley: 60.23%).
The construction company had SGD 402.39m of cash and short term deposits as at 1H21, but possibly half are likely made up of short-term deposits. Of the SGD 374.04m of cash and short term deposits as at 31 December 2021, SGD 179.91m are held at project accounts. Residual cash on hand was only SGD 156.25m.
Looking at its current liabilities, CHIPEN recorded SGD 496.02m of current loans and borrowings, but SGD 71.25m of this amount has been refinanced to 2024. The project loans at Park Colonial will also be repaid upon its TOP in 2022.
Cash flows will also improve upon the completion of the Land Transport Authority Contract T227 (construction of Marina South Station and tunnels for Thomson-East Coast Line) and the Public Utilities Board Contract C22A (Changi Water Reclamation Plant Phase 2 – Foundation Works for Train 5) by 2022. Barring unforeseen circumstances, the company said that “the financial impact from Covid-19 is not expected to affect the group’s ability to fulfil its financial obligations in FY2022”. We believe that Chip Eng Seng is able to refinance its secured bank loans and has adequate liquidity to repay short-term borrowings.
Relative valuation
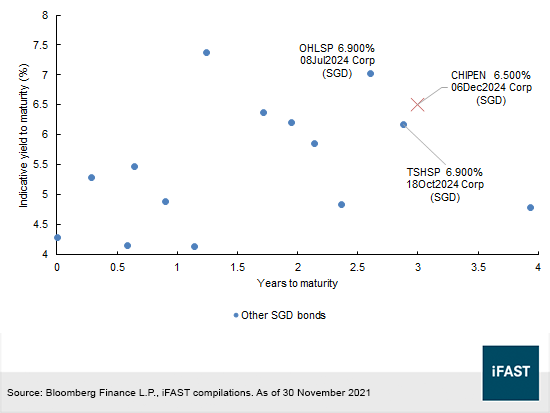
In our opinion, the CHIPEN 6.5% 2024’s are fairly priced within the SGD high yield space. The OHLSP 6.900% 08Jul2024 Corp (SGD) are trading at a higher yield-to-maturity of 7.03%, and that is reflective of the issuer’s higher gearing and lower interest servicing ability compared to CHIPEN. Tuan Sing has the lowest gearing of the three companies and the TSHSP 6.900% 18Oct2024 Corp (SGD) is trading at the lowest yield-to-maturity of 6.17%.
Considering their short maturities, recent financial performance and credit metrics, we think that the TSHSP 6.900% 18Oct2024 Corp (SGD) and CHIPEN 6.500% 06Dec2024 Corp (SGD) are more attractively priced compared to the OHLSP 6.900% 08Jul2024 Corp (SGD). We still hold the view that Oxley will repay its 2024 bonds; we also have positive outlooks for Tuan Sing and Chip Eng Seng. But as of 30 November 2021, the valuations of the CHIPEN 6.5% 2024’s and TSHSP 6.9% 2024’s are more attractive than the OHLSP 6.9% 2024’s.
Figure 1: Relative valuation among SGD bonds
Declaration: For or specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in OHLSP 6.900% 08Jul2024 Corp (SGD) and TSHSP 6.900% 18Oct2024 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!