Hotel Properties Limited (“Hotel Properties”) is planning to refinance the HPLSP 3.850% 27May2021 Corp (SGD) and finance working capital requirements through a new debt offering. The new 7-year notes have an initial price guidance (“IPG”) of 3.90%.
About the bonds
The senior unsecured bonds will mature in May 2028 and they are priced under the terms and conditions of the SGD 1 billion multicurrency debt issuance programme dated 3 Mar 2017 (“MTN programme”). According to the preliminary pricing supplement, these bonds are redeemable in a Change-of-Control Event, which is triggered when there is a significant change in the ownership of the company. As per the definitions in the MTN programme , bondholders have the option of selling back their notes upon the cessation or suspension of shares on the Singapore Exchange. In addition, the bonds may be redeemed for taxation reasons.
About the issuer
Hotel Properties is a publicly listed company that was incorporated on 28 Jan 1980. The group has an interest in 38 hotels, and owns resorts and shopping galleries in 15 countries including Bhutan, Italy, Maldives, South Africa and Vanuatu. Since its initial public offering in June 1982, the market capitalization of the company has expanded to approximately SGD 1.68 billion on 19 May 2021.
Mr Ong Beng Seng co-founded the company and held a deemed 39.43% interest in the group as at 18 Mar 2021. According to Forbes, Mr Ong and his wife are one of the richest persons in Singapore. Wheelock and Company Limited, the other major shareholder, has a 22.52% deemed interest in the group. Wheelock is now a private company but they are widely recognized as one of the largest property developers in Hong Kong.
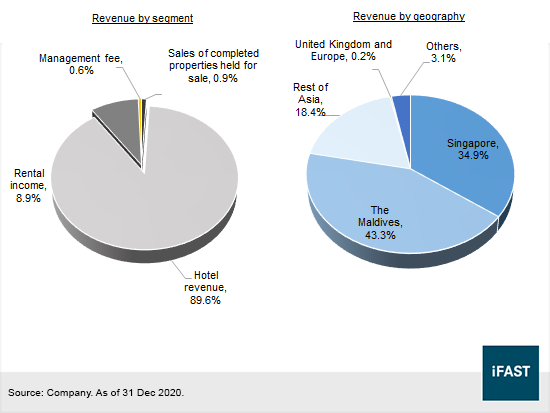
Group revenue is recognized through four primary segments – (1) sales of completed properties for sale; (2) hotel revenue; (3) rental income and (4) management fees (Figure 1), while geographically, most of the company’s revenue is derived from Singapore and The Maldives.
Figure 1: 2020 revenue by segment and geography
2020 financial performance
During the financial year ended 31 Dec 2020, Hotel Properties recorded a 53.5% drop in annual revenue to SGD 258.8m from SGD 556.4m in 2019. Coinciding with the onset of the pandemic in the first few months of 2020, there was a meaningful drop in revenue during the initial phase of the outbreak but hotel reservations subsequently improved towards the end of the year.
The group witnessed a recovery in its Singapore operations as the hotels received more guests on staycations and hosted guests who were on Stay Home Notices. According to responses at their annual general meeting, the properties in Maldives were reportedly doing well up until borders were closed. However, travel resumed at the end of 2020 and there was a strong demand for room bookings. Overall, the group’s resorts in Maldives benefited from permitted tourism activity and improved flight connectivity.
As for their London Properties, Paddington Square is due to achieve completion in 2022. However, they are not expected to commence pre-sales activity until 2022. The Bankside Yards project consists of 3 buildings, one of which is expected to be completed in 2022 whereas the other 2 are likely to be completed only after 2024. Both Paddington and Bankside offices are being marketed and the properties have received interest from international businesses.
Moving along the financial income statement, other operating income plunged from SGD 38.6m in 2019 to SGD 5.3m in 2020 while operating expenses increased from SGD 16.8m to SGD 33.8m during the same period. Staff costs were reduced to SGD 100.6m from SGD 164.4m while its share of results from associates and jointly controlled entities swung from a SGD 28.9m gain to a SGD 42.0m loss in 2020. After taking into account a SGD 28.2m charge for fair value losses in investment properties, the company reported a net loss of SGD 188.1m for the year.
Liquidity and credit discussion
Hotel Properties recorded SGD 95.7m of cash at the end of December, out of which SGD 4.2m were pledged to secure credit facilities. The amount of cash is insufficient to cover its SGD 150.3m of short term borrowings, but the issuer is likely to repay the SGD 100m HPLSP 3.85% 2021’s through this bond offering. According to our understanding, the company also raised SGD 50m in January 2021 through a fixed rate bond issue.
Group gearing, measured as the ratio of financial obligations (i.e. short-term borrowings, long-term borrowings, long-term lease liabilities and perpetual securities) over total assets, increased from ~35.6% in 2019 to ~41.7% in 2020. Net debt to total equity meanwhile climbed to ~71.7% from ~51.0% in 2019. The level of gearing is high, but they are still lower than Shangri-La Asia Limited, which had estimated ratios of ~45.6% and (net debt-to-equity) ~86.5% in 2020 respectively.
If need be, the group may divest some of its assets to meet debt requirements. The amount of investment properties, consisting of shop units along Orchard Road, had a carrying value of SGD 681.3m as at 2020. Together with the SGD 753.5m of freehold and leasehold buildings, the combined value of SGD 1.43 billion would cover the SGD 946.1m of interest bearing liabilities due in 2 to 5 years.
Relative valuation
In spite of its adequate liquidity profile, we do not think that the new 7-year bonds are attractively priced. With an IPG of 3.9%, the HPLSP bonds have an I-spread, or credit spread above the 7-year Swap Offer Rate (“SOR”), of 262 basis points (“bps”). This is nearly equivalent to the credit spread of the HPLSP 3.800% 02Jun2025 Corp (SGD), with an I-spread of 258bps (Figure 2). Both senior notes have identical terms with cessation and Change-of-Control put provisions. Based on theirs relative valuations, we would prefer the HPLSP 3.8% 2025’s over the new HPLSP 7-year note because of its shorter maturity and similar credit spread.
Figure 2: Relative valuation among comparable SGD fixed rate notes
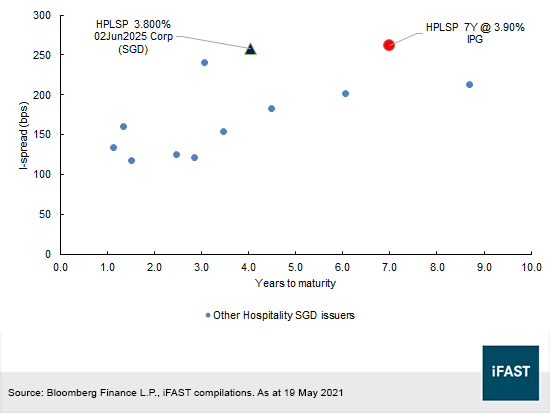
Apart from the HPLSP 3.8% 2025’s, investors have the option of considering the HPLSP 4.650% Perpetual Corp (SGD) at its yield to next call of 11.63%. The HPLSP 4.65% perps are callable on 5 May 2022, and the distribution rate will reset to the sum of the prevailing 5-year SOR + 268.5bps initial spread if not called. Group cash flows may be low, but we assume that the firm will sell assets for liquidity. For investors who do not mind a non-call event, the perps look attractive at its current price. Furthermore, the new reset rate is unlikely to head lower and HPLSP can call the perps at every 6 months thereafter if the issuer fails to redeem the issue on its first call date.
Figure 3: Relative valuation using yield-to-maturity
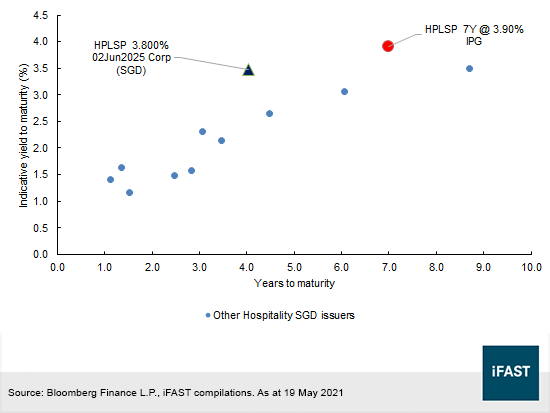
From another perspective, although the 3.9% IPG would provide the highest yield-to-maturity among comparable hospitality issues, we do not think that the 40bps pickup compensates adequately for a 2-year difference between the HPLSP 3.8% 2025’s and the new bonds.
Keeping all the above in mind, we continue to keep a positive outlook on Hotel Properties Limited as a bond issuer, but we think that the initial price guidance of 3.9% for a 7-year issue is not attractive enough vis-a-vis to its existing notes.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!