- SIA saw record
quarterly profits in 1H22 as travel demand recovers.
- Net debt
position went negative as cash position significantly improved from the performance.
- SIA redeemed its
first tranche of Rights MCBs, citing a strong cash position.
- SIASP 3.030% 28Mar2024 Corp (SGD) - Retail is attractive over the Singapore T-bills.
A long history before becoming Singapore Airlines
Singapore Airlines Limited (“SIA”) prides itself as a global company dedicated to providing air transportation services of the highest quality. Being the flag carrier airline for Singapore, SIA has begun its operations in 1947 under Malayan Airways, which broke off later in 1972. As a group, it operates via several business segments, mainly SIA, its full-service carrier; Scoot, its low-cost carrier; and SIA Engineering Company, which provides a variety of advanced engineering services. Across the carriers, it operates a total of 193 aircraft with the passenger network covering 111 destinations across the globe.
With the COVID-19 pandemic resulting in lockdowns across the globe, SIA had to bear the brunt of lockdowns during 2020 and 2021 when leisure travel was practically impossible. Over the past few years, it raised more than SGD 22b through various corporate actions to fund its operations – rights issuance of shares and mandatory convertible bonds (“MCB”), private placements, sales of aircraft, debt issuance and others. While the lockdown was undeniably damaging, SIA remained prepared for the resurgence in air travel with talent retention and resource deployment initiatives – putting them in a prime position to capture the travel demand at the best opportunity.
As a testament to its record performance, SIA recently announced an interim dividend of SGD 0.10 per share, the first since the COVID-19 pandemic affected its business severely. Similarly, looking at their latest operating results in December 2022, group passenger capacity has already recovered to 80% of pre-COVID-19 levels, which has risen from a mere 46% at the start of last year in January 2022.
The big winner in the post-COVID era
Unsurprisingly, SIA’s performance had been stellar in 2022. For the half-year period ended 30 September 2022 (“1H22”), SIA attained a record operating profit of SGD 1,234m – a huge reversal from the operating loss of SGD 619m in 1H21. Passenger flown revenue increased by 694% year-on-year (“YoY”), while cargo revenue grew 11.9% YoY despite a 5.6% decline in cargo loads, in which the lesser loads were compensated by higher yields on cargo. The spectacular results came despite having a 93% increase in fuel prices, which SIA indicated that overall inflation has had an impact on their expenditures.
Chart 1
Improving performance by SIA post-COVID
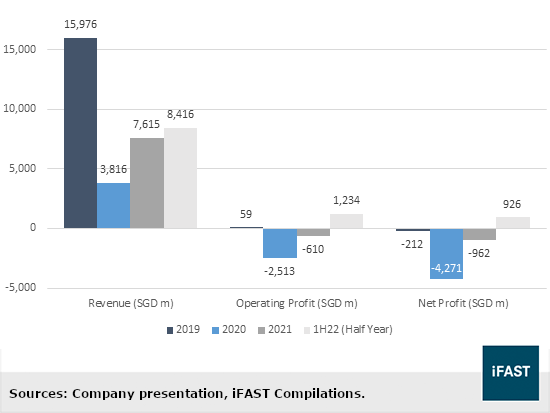
For the three months ended 30 September 2022 (“2Q22”), SIA recorded the highest quarterly revenue in history at SGD 4,488m, a 14.3% increase from the previous quarter. Similarly, the highest quarterly operating profit was recorded at SGD 678m, which was a 21.9% increase from 1Q22. Net profit came at SGD 557m in 2Q22, which increased by 50.5% from the previous quarter – attributable to higher operating profit, lower net finance charges and improvement in the share of results of joint ventures and associated companies.
Amidst the balance sheet, the sales in advance of carriage particularly stood out, which the increase in sales in advance of carriage amounted to SGD 2,053m in 1H22, reflecting an additional SGD 2b worth of pre-booking, undelivered flights in the first half of the year alone. With the resurgence in travel demand, SIA has benefitted strongly from the pent-up demand to travel – which saw significantly huge pre-booked orders for flights as we continue to see COVID-19 further easing up. SIA expects the forward sales to continue coming through in the months leading up to the Lunar New Year period, especially in consideration of the easing of restrictions in Hong Kong, Taipei and Japan.
A lot of debt, yet a lot of cash?
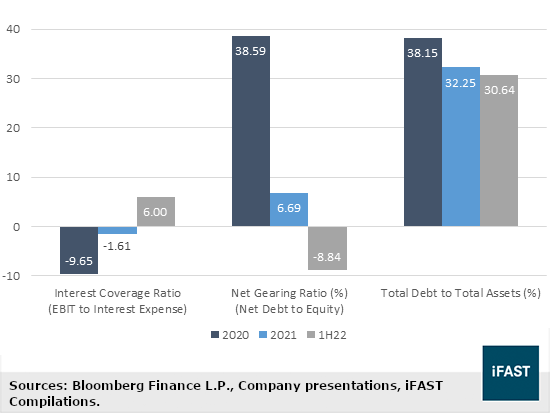
As an airlines company, it is within expectations for SIA to have a substantial amount of debt to finance its capital expenditure and acquisition of aircraft – as of 30 September 2022, SIA has a total debt of approximately SGD 15.8b – furthermore, the pandemic situation required SIA to raise fresh funds to ensure it remains in operation. However, with total cash and bank balances sitting at SGD 17.4b, the net debt for SIA falls back to negative. Its cash position significantly increased from the previous SGD 13.7b as of 31 March 2022, with a net cashflow of SGD 3.7b primarily due to net cash generated from operations, inclusive of the proceeds from forward sales.
With the rebound in its performance in contrast to the past few years of pandemic-stricken lockdowns, we see significant improvements to its interest coverage ratio and also net gearing ratio (various ratios made not meaningful for comparison due to lack of profits for SIA over the pandemic, but we do see such ratios improving significantly as well.)
Chart 2
SIA’s Debt and Liquidity Ratios since 2020
On 25 October 2022, SIA announced the intention to fully redeem the SGD 3,496m Rights MCBs previously issued in June 2020 at the semi-annual date of 8 December 2022. The accreted principal amount was valued at SGD 3,860m, 110.408% of the principal amount, and funded completely with its cash reserves that have “risen in line with the strong recovery in the demand for passenger air travel”. With the redemption, SIA’s pro forma total cash and bank balances fall to SGD 13.6b alongside its equity falling from SGD 23.2b to SGD 19.3b, as the MCBs were accounted under equity. Consequently, the debt-to-equity ratio will rise from 0.68 to 0.82 after the redemption.
Looking further into SIA’s debt profile, it was indicated that the total floating rate loans amount to SGD 4,426.8m as of 31 March 2022, which SIA hedged a significant 93% of it with interest rate swaps. On the other hand, SIA has about SGD 1.67b worth of current borrowings as of 30 September 2022, which SIA is unlikely to have any issues repaying or refinancing considering their current cash position and an undrawn credit line amounting to SGD 2.2b. As SIA continues to benefit from the recovering travel demand, we believe their credit and liquidity profile will only improve from here – one that has already recovered to a sufficiently strong level as reflected by their intention to redeem the first tranche of Rights MCBs.
Recommendations
Table 1
SIASP SGD Issuances
|
Issue |
Years to Maturity |
Ask Price |
Yield to Maturity (%) |
|
0.77 |
99.56 |
3.80 |
|
|
1.19 |
98.11 |
4.77 |
|
|
1.22 |
100.01 |
3.78 |
|
|
2.23 |
98.40 |
3.84 |
|
|
2.88 |
110.62 |
-1.95 |
|
|
3.84 |
97.15 |
3.98 |
|
|
4.60 |
96.70 |
3.96 |
|
|
7.39 |
102.00 |
7.04 |
|
|
7.88 |
94.08 |
4.45 |
|
|
Sources: Bondsupermart, iFAST Compilations. Data as of 19 January 2023. *These issues are not available through our platforms. |
|||
With SIA’s current credit and liquidity profile, the SIASP 3.030% 28Mar2024 Corp (SGD) – Retail is a strong consideration over the existing 6-month and 1-year Singapore T-bills, currently sitting at yields of 4.04 and 4.10% as of 19 January 2023 respectively. While the T-bills are generally risk-free, the additional 60 over basis points offer a fair yield pick-up over the T-bills, alongside a slightly longer term to maturity of 1.19 years – as compared to the 6 months nature of the more frequently issued T-bills. At the same time, this issue is offered on a retail basis – allowing all retail investors to gain access to the issuance with just $1,000, similarly accessible like the T-bills, in contrast to SIA’s other fixed-dated notes.
SIA’s other retail offering is its Rights MCBs (SIASP ZERO 08Jun2030 Corp (SGD) – Retail) offered in 2021 with a total tranche of approximately SGD 6.1b. We would like to highlight that this series of Rights MCBs are not offered on our platform. With SIA redeeming their previous tranche of Rights MCBs, and the continued strong performance from recovering in tourism, it is likely for SIA to seek redemption of the Rights MCBs as soon as they can. The Rights MCBs severely dilute the shares upon conversion and subsequently impact the share price, while the accreted principal amount increases on every semi-annual callable date. As such, it benefits SIA more to redeem the Rights MCBs when the opportunity arises rather than doing it later or allowing it to convert.
As we currently favour short-duration issues with strong credit profiles, SIASP 3.030% 28Mar2024 Corp (SGD) – Retail falls into the right spot, concurrently allowing retail investors to take part as compared to the conventional corporate bonds. In addition, we believe SIA’s credit profile will continue to strengthen as global travel recovers to pre-pandemic levels – further supporting the case of the retail offering being an attractive pick over the T-bills.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!