Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
- On 24 June 2021, Keppel Corporation Limited and Sembcorp Marine Ltd entered into a non-binding memorandum of understanding into talks of possibly merging Keppel O&M and Sembcorp Marine.
- The O&M sector has contracted due to a sustained reduction in oil exploration and development activities.
- Keppel reported its 1Q21 results for the quarter ended 31 March 2021 and recorded a net profit for the quarter.
- We think that Keppel bondholders will benefit from the potential merger as Keppel will offload its O&M segment through this merger.
On 24 June 2021, Keppel Corporation Limited (“Keppel”) and Sembcorp Marine Ltd (“Sembcorp Marine”) have entered into a non-binding memorandum of understanding (“MOU”) into talks of possibly merging Keppel Offshore & Marine (“O&M”) and Sembcorp Marine (“Combined Entity”).
In recent years, there has been a significant contraction in the O&M sector due to a sustained reduction in oil exploration and development activities. The demand for oil was severely impacted due to COVID-19 and oil prices plunged as a result. As the global footprint pivots towards clean energy and away from oil, the Combined Entity will also transition into new opportunities in the clean energy sector. If the proposed transaction is completed, the Combined Entity will be a stronger player to capitalise on the growing opportunities of the O&M, renewable and clean energy sectors.
About the Potential Merger
Keppel and Sembcorp Marine are exploring the possibility to merge Keppel O&M and Sembcorp Marine into a Combined Entity. Keppel will enter into a 50-50 joint venture with the Combined Entity and this would allow Keppel to continue accessing Keppel O&M capabilities required for its projects. Additionally, it is envisioned that the Combined Entity will be the preferred engineering, procurement, and construction (“EPC”) partner for future projects while the Combined Entity will provide relevant expertise to Keppel.
If successfully completed, the Combined Entity will be a listed entity and Sembcorp Marine’s shareholders will hold shares in the Combined Entity while Keppel will receive 50% of shares in the joint venture with the Combined Entity and cash considerations of up to SGD 500m.
We view that Keppel will benefit more from this potential merger as Keppel will offload its O&M segment through this merger. On the other hand, the Combined Entity will have the potential to grow as a strong player in the O&M sector and capitalise on the opportunities in the growing clean energy and renewable sector. Establishing it as the preferred EPC partner for future projects will also provide Keppel additional income stream for future projects through the Combined Entity.
However, discussions and negotiations of the merger are still in the preliminary stage and is expected to take several months. We will provide another update once the merger has been finalised.
About Sembcorp Marine
Sembcorp Marine is a company that provides engineering solutions to global offshore, marine and energy industries. It has shipyards and other facilities in Singapore, Indonesia, the United Kingdom, Norway and Brazil.
In September 2020, Sembcorp Marine announced a SGD 2.1b recapitalisation and demerger from Sembcorp Industries. Now that the demerger has been completed, Sembcorp Marine has ceased to be a subsidiary of Sembcorp Industries and Temasek’s wholly owned subsidiary Startree Investments is now a direct and significant shareholder of the Company.
The company is currently pivoting into the renewable energy sector, securing a contract from RWE Renewables to supply the high voltage direct current electrical transmission system for the Sofia Offshore Wind Farm. It is the second largest contract for the Sofia Offshore Wind Farm and is worth approximately SGD 1.12b.
The company also has footfall in the highly competitive offshore wind sector in Taiwan. Sembcorp Marine is currently fabricating 15 jacket foundations in the Formosa 2 Offshore Wind Farm, which will be Taiwan’s largest offshore wind farm.
About Keppel Corporation
Keppel is one of Singapore’s household blue-chip names. It has business segments in Energy and Environment, Urban Development, Connectivity and Asset Management. It had a market capitalisation of about SGD 9.54b on 8 July 2021 and is 20.4% owned by Temasek Holdings (as of 4 March 2021).
Figure 1: Trailing twelve month revenue by business segments
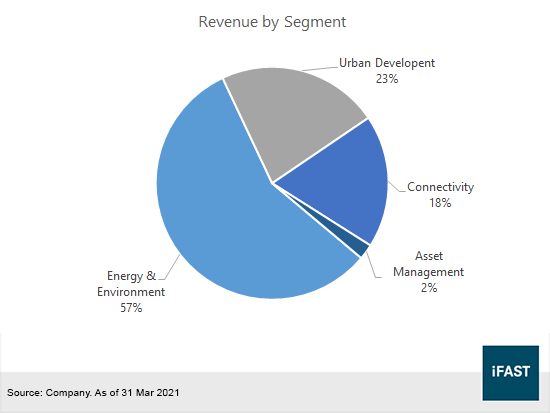
Keppel’s Energy & Environment segment is made up of Keppel O&M and Keppel Infrastructure. Keppel O&M has been making efforts in recent years to pivot into the renewable energy sector. In 2020, Keppel O&M secured about SGD 1b of new orders with Liquid Natural Gas (“LNG”) orders making up 65% of new orders. As at end-2020, 82% of Keppel O&M’s net orderbook comprises of renewables and gas solutions. Last year, Keppel Infrastructure secured SGD 2.1b worth of waste-to-energy (“WTE”) and district cooling contracts across Singapore, India and Thailand.
Keppel’s Urban Development segment is made up of Keppel Land and Keppel Urban Solutions. In 2020, Keppel Land announced divestments of about SGD 1.3b. Keppel Land has a total residential landbank of 54,000 homes majority of which are located in China and Vietnam. Keppel Urban Solutions is a developer of smart and sustainable urban townships and continues to collaborate with Keppel Land to develop Saigon Sports City.
M1 and Keppel Data Centres make up Keppel’s Connectivity segment. M1 secured the 5G network license together with Starhub in 2020 and will roll out 5G networks across Singapore. M1 has grown to secure the second largest postpaid customer base in Singapore. We expect the 5G rollout and its postpaid customer base to provide M1 with consistent and new streams of income.
Lastly, the Asset Management segment consists of Keppel Capital, private funds, business trusts and listed REITs. Keppel Capital grew assets under management from SGD 33b in 2019 to SGD 37b in 2020. Despite COVID-19 headwinds, Keppel Capital managed to raise SGD 4.5b from institutional investors in 2020.
Keppel 1Q21 Financial results
Figure 2: 1Q21 Revenues by segment
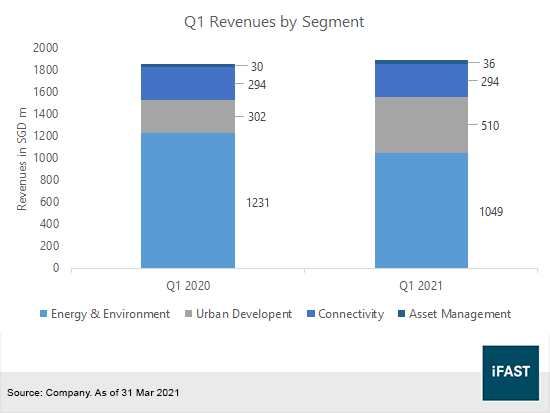
Keppel reported its 1Q21 results for the quarter ended 31 March 2021 and recorded a net profit for the quarter. Revenues for 1Q21 improved to SGD 1.89b, representing a 1.72% increase from 1Q20. All business segments except for Keppel O&M were profitable for the quarter.
From Figure 2, revenues from all business segments increased QoQ except for Energy & Environment. This is mainly due to declining revenues from Keppel O&M. However, Keppel O&M reported positive EBITDA and recorded a net loss for the quarter. Revenues of Keppel O&M fell from SGD 569m in 1Q20 to SGD 412m in 1Q21 due to the termination of Awilco rigs.
Revenues from Keppel Land increased from SGD 302m in 1Q20 to SGD 510m in 1Q21 due to the increase in home sales. Looking ahead, Keppel Land is expected to sell 8,740 overseas units worth around SGD 4.7b, which will be recognized from 2Q21 onwards to 2025.
Revenue from its Connectivity segment remained stable at SGD 294m. Revenues for M1 fell from SGD 260m in 1Q20 to SGD 254m in 1Q21. This is due to lower roaming and prepaid revenues. The Connectivity segment is expected to grow in the following quarters as COVID-19 restrictions are being lifted off. Furthermore, the development of the Bifrost Cable System will provide additional new income streams to this segment.
Keppel Capital performed better due to stronger operating results as well as gains from mark-to-market investments. Asset management fees added to SGD 42m for 1Q21 as compared to SGD 35m in 1Q20.
With that in mind, we find the merger of Keppel O&M and Sembcorp Marine to be beneficial to Keppel as it will offload its loss making segment and focus on development in its other segments. The Urban Development and Connectivity segments have more headroom to grow and should be a significant revenue driver in years to come.
By offloading Keppel O&M to form a Combined Entity with Sembcorp Marine, it will develop a stronger player in their efforts to expand into the growing renewables and clean energy sector. Furthermore, by partnering with the new Combined Entity and with the new Combined Entity being the preferred EPC partner in future projects, this will provide Keppel additional streams of income following the merger.
Liquidity Profile
Total borrowings climbed to SGD 12b in FY2020 (the financial year ended 31 December 2020), up by SGD 1.1b from the previous year. 37% of borrowings were repayable within one year while the rest of the balance repayable more than three years later.
Figure 3: Debt maturity profile
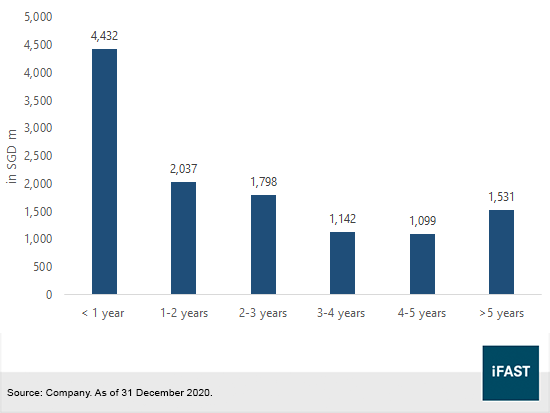
Liquidity is managed so that working capital lines are available at any time. Cash flows and the group’s debt payment requirements are reviewed on an ongoing basis. Operating cash flows for FY2020 is currently positive at SGD 202m while in the previous year, operating cash flows suffered a loss of SGD 825m.
However the company’s gearing is adequate at this point. Net gearing dropped slightly to 0.88x in 1Q21 compared to 0.91x for FY2020. If the divestment of Keppel Bay Tower was completed in the first quarter, net gearing for Keppel would have been 0.83x.
As of FY2020, Keppel’s interest coverage (taken as EBIT/ Interest Cost) was 0.11x while cash flow coverage (taken as Operating Cash Flow + Interest Cost/ Interest Cost) was at 1.60x. In our view, Keppel’s liquidity profile will improve and the group will be able to manage its short term debts better if it managed to setup a new Combined Entity.
Bond Recommendations
Bondholders currently holding KEPSP bonds can rest assured that a merger, if materialized, is deemed as a credit positive to Keppel. The potential merger will allow Keppel to focus on developing its growing business segments especially in the Urban Development and Connectivity segments. Keppel’s credit profile will improve following the merger as Keppel will be able to offload the loss making segment of Keppel O&M, improve liquidity as well as lower its leverage.
Figure 4: Relative valuation among Keppel’s fixed rate bonds
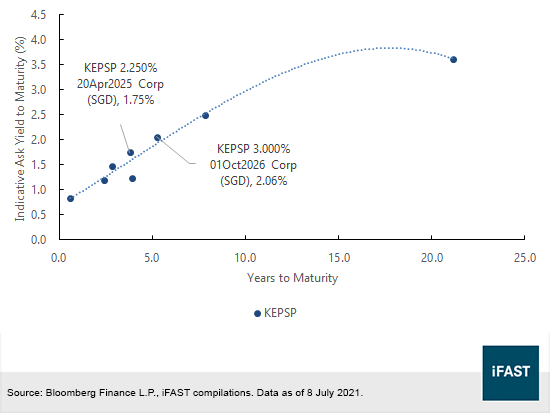
For investors looking into investing in Keppel bonds, they may consider KEPSP 2.250% 20Apr2025 Corp (SGD) or KEPSP 3.000% 01Oct2026 Corp (SGD). The yield-to-maturity (“YTM”) is 1.75% and 2.06% respectively as of 8 Jul 2021.
All in all, we find that the probable setup of a new entity to be credit positive for Keppel. This transaction allows Keppel to offload its loss making segment in Keppel O&M and also benefit from the partnership through future projects from the Combined Entity by making it as the preferred EPC partner. Additionally, this Combined Entity would create a bigger player in the growing renewables and clean energy sector. Post-transaction, the credit profile is expected to improve and allow Keppel to better manage its short term debts. Therefore, we feel that Keppel would emerge as the larger winner from this potential merger.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!