Highlights:
Hysan Development mainly engages in property investment and management. Its asset portfolio and development focus are in the Causeway Bay area of Hong Kong. The Caroline Hill Road project is currently in good progress and it is expected that 2027 onwards will be the "harvesting period" for the company.
- Regarding the industry outlook, Hong Kong office rents might continue to be under pressure. But the retail industry in Hong Kong is not that bad. The retail sales and rents should recover slowly going forward.
- The overall operating performance of Hysan is fair. It is expected to be a bit weak going forward. However, the company’s investment properties are valuable. The actual leverage level is low. The overall credit risk remains low.
- Investors could consider its 2027 bond, with a yield to maturity of 5.7%.
Hysan Development (“Hysan”) mainly engages in property investment and management. Its asset portfolio is mainly located in Causeway Bay, Hong Kong, including Lee Gardens Phases 1 to 6, Hysan Place and Leighton Center. The company is listed on HKEX (Stock Code: 14.HK) with a market capitalization of around HKD 15.1 billion.
2027 Onwards will be the "Harvest Period" for the Company
About 90% of Hysan's rental revenues come from Causeway Bay, Hong Kong, including its office and retail portfolio, with only a small number of co-development projects in Hong Kong and rental properties in the Mainland. The company focuses on expanding its investment properties in the Causeway Bay area.
As shown in Chart 1, in mid-2021, Hysan and Chinachem Group formed a JV to acquire the Caroline Hill Road site for HKD 19.8 billion (Hysan and Chinachem Group have a 60% and 40% interest in the project respectively. The revenue and cost of this project will be accounted for in a consolidated statement). The company aims to create a larger scale of Lee Gardens.
Chart 1: Hysan’s Causeway Bay Development blueprint
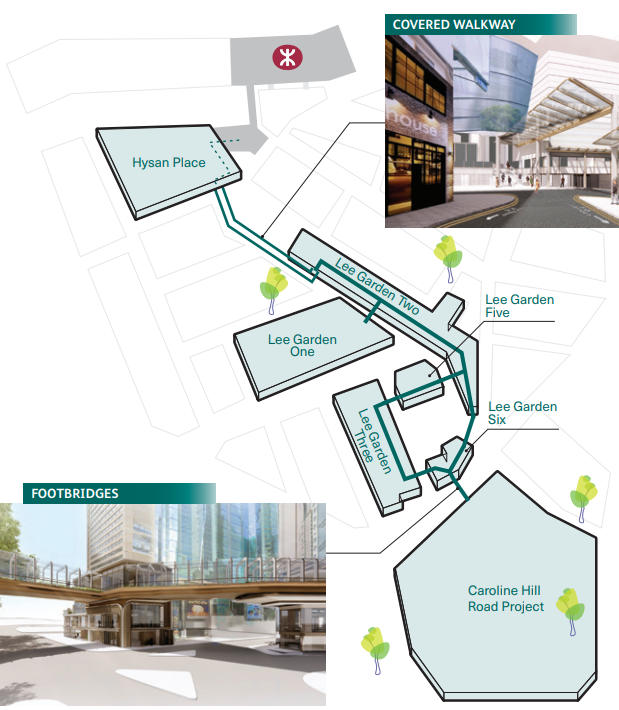
The Caroline Hill Road project will add around 1.1 million sq. feet to Hysan’s asset portfolio, which is expected to generate at least HKD 800 million extra rental revenues (in 100% project stake), equivalent to Hysan’s current revenues of around 20% to 25%. The Company targets to start the operation by the end of 2026. The project is currently in good progress and it is expected that 2027 onwards will be the "harvesting period" for the company.
Looking back from a current perspective, Hysan's decision to acquire the land at that time might not be precise as they buy at the peak. It is similar to Henderson Land's acquisition of the 3 New Central Harbourfront lot at a high price in that year.
However, for bond investors, some false decision making in the business is not fatal. Given that the issuer has enough ability and cash flows to repay the debt, the bond still has good investment value.
Hong Kong Office Rents might Continue to Be Under Pressure
Hysan's core portfolio consists of offices and malls in Causeway Bay, Hong Kong. The industry outlook of commercial real estate in Hong Kong is important to the company. For the office outlook, as shown in Chart 2, since the protest in 2019 and COVID-19 in 2020, the rental revenues of offices in Wan Chai and Causeway Bay dropped significantly, with the rate of decline even as high as 40% from the high level, making it one of the hardest-hit areas.
Chart 2: Net Rent per NSF of Grade A Offices in Different Districts
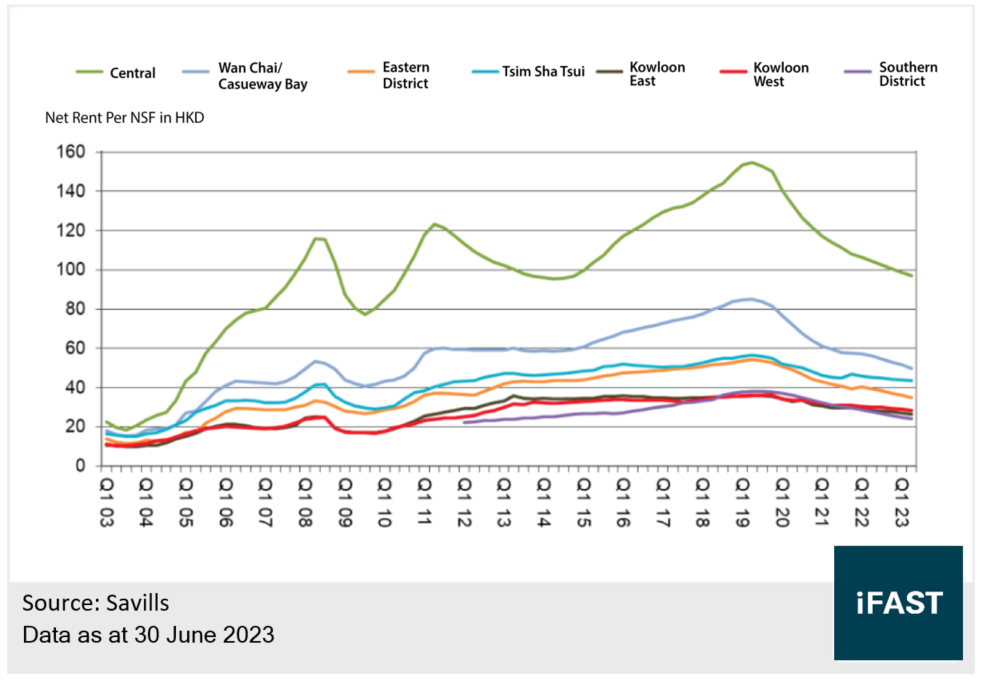
Fortunately, as shown in Table 1, the occupancy rate of offices in Wan Chai and Causeway Bay shows the sign of stabilising by the end of October 2023, with an occupancy rate of 90.2%. The rate is also higher than that of the occupancy rate of overall Grade A offices.
Table 1: Occupancy Rate of Grade A Offices in Different Districts
|
Dec 2022 |
Oct 2023 |
|
|
Wan Chai and Causeway Bay |
89.8% |
90.2% |
|
Overall |
87.9% |
87.4% |
|
Sources: JLL, iFAST Compilations Data as of 30 October 2023 |
||
Whether in Hong Kong or just in Wan Chai and Causeway Bay, there will be more new supply of office space in the future. On the demand side, we believe that the factors, such as the uncertainties in the global and China and Hong Kong economic outlook, would exert further downward pressure on the local office market, since corporations are generally more cautious in leasing new space. Hysan's portfolio will be less likely to survive individually. The rents of its office portfolio might continue to be under pressure.
The Retail Industry in Hong Kong is Not that Bad; Retail Sales and Rents should Recover Slowly Going Forward
Regarding shopping malls, as shown in Table 2, since year-to-date, the rents of major shopping centres in Hong Kong rebounded, mainly driven by the Hong Kong and mainland China border reopening and business expansion of major brands which have better sales. However, the rebound in sales and rents is not too strong because Hong Kong residents are more disciplined in their consumption spending due to the higher interest rate, higher mortgage repayments and higher rents in residential, along with the increasing willingness of Hong Kong residents to go travelling outside Hong Kong.
Table 2: Rents of Major Shopping Centres in Different Districts in Hong Kong
|
2021 (YoY) |
2022 (YoY) |
2023 Q1 (QoQ) |
2023 Q2 (QoQ) |
2023 Q3 (QoQ) |
|
|
Hong Kong Island |
-6.9% |
-2.6% |
+5.2% |
+1.1% |
+0.7% |
|
Kowloon |
-2.7% |
-2.9% |
+5.0% |
+1.2% |
+1.3% |
|
New Territories |
+3.1% |
-9.8% |
+4.8% |
+0.4% |
+0.2% |
|
Overall |
-2.1% |
-5.1% |
+5.0% |
+0.9% |
+0.8% |
|
Sources: Savills, iFAST Compilations Data as of 30 September 2023 |
|||||
We believe that the retail industry in Hong Kong is not that bad. After all, the unemployment rate in Hong Kong is at a historical low. In some industries, employees’ salary has a huge increase, which makes the consumption of Hong Kong residents somewhat resilient. The Mainland China residents also have the intention to visit Hong Kong for travel. The base rents of shopping malls already dropped by about 20% to 30% from 2020 to 2022. With the low-base effect, the rents of shopping malls should be in the position of stopping the decline and starting to be stabilised. The retail sales and rents should recover slowly going forward.
Overall Operating Performance is Fair; Expected to Be a bit Weak Going Forward
As shown in Chart 3, in the first half of 2023, Hysan’s revenues were around HKD 1.61 billion, which decreased by 9.3% YoY, mainly due to the partial closure of about 11% of the shopping mall area for asset enhancement. The core profit decreased 12.2% YoY to around HKD 1.03 billion.
Chart 3: Hysan Development’s Revenues and Core Profits
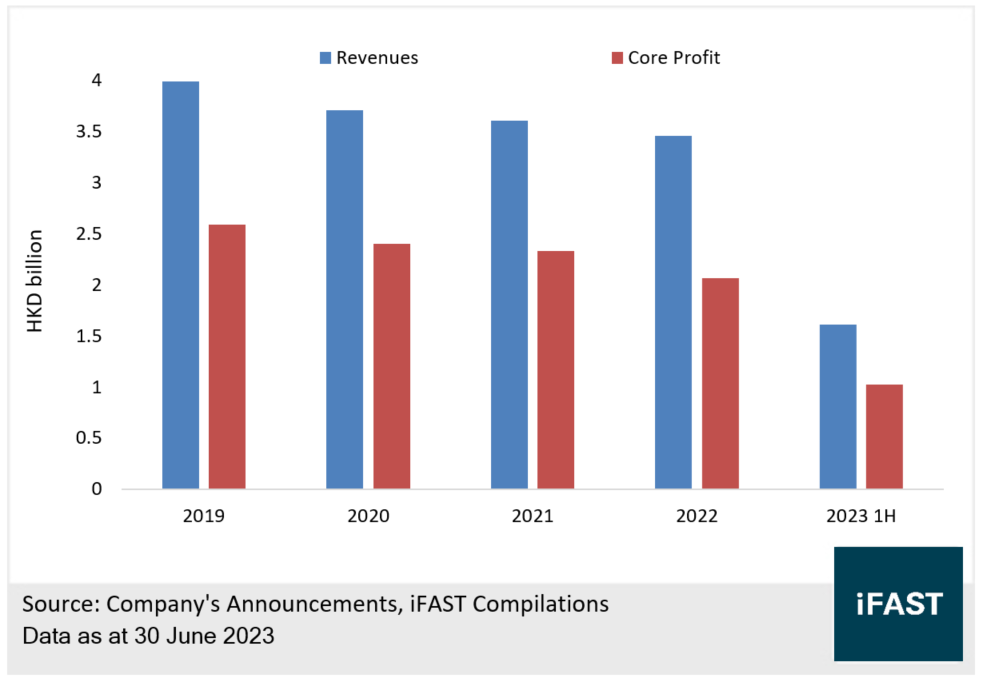
Hysan's revenue and core profit both declined in recent years, mainly due to a decrease in rental revenues. The overall operating performance was fair. However, along with the shopping mall rents being stabilized, we believe it is unlikely that its revenue will continue to fall over the long term. The partial closure of the shopping mall area under renovation will eventually come back into operation. However, before the completion of the Caroline Hill Road project, the company's operating performance is expected to be a bit weak due to the downward pressure on overall rents and an increase in interest expenses (especially in light of the company's borrowing to purchase the lot for the Caroline Hill Road project under the high interest rate environment).
With Valuable Investment Properties, Overall Credit Risk Remains Low
As shown in Table 3, as of the end of June, Hysan’s total debt was around HKD 35.8 billion. The net gearing ratio was 42.5%. The net debt to EBITDA was high at 12.8 times. The leverage level seemed to be high. The interest coverage ratio was 1.6 times. The interest payment ability looked weak.
In 2021, Hysan and Chinachem Group formed a JV to acquire the Caroline Hill Road site for HKD 19.8 billion, resulting in a large increase in its cash expenses and debts. This large-scale commercial project will not be completed until the end of 2026. There is a time lag between the increase in its debt level and profitability. Thus, the profitability-based credit metrics (such as net Debt/EBITDA and interest coverage ratio, etc.) might appear to be unsatisfactory, but this is a normal phenomenon of the operation. Therefore, investors should not be too worried about weak profitability-based credit metrics.
On the other hand, the company has valuable investment properties of around HKD 96.7 billion in terms of book value. Only 20% of its investment properties have been pledged to secure bank loans. Its net debt/investment properties were low at 31.4%. From this angle, the company's actual leverage level is not high. There is large room for refinancing and increasing leverage.
Table 3: Hysan’s Credit Metrics
|
Dec 22 |
Jun 23 |
|
|
Total Debt* (HKD billion) |
37.5 |
35.8 |
|
Total Cash and Marketable Securities (HKD billion) |
7.8 |
4.4 |
|
Investment Properties (HKD billion) |
96.8 |
96.7 |
|
Net Gearing Ratio* (%) |
39.3% |
42.5% |
|
Net Debt* / Investment Properties (%) |
29.7% |
31.4% |
|
Net Debt* / EBITDA (times) |
11.1x |
12.8x |
|
Cash to Short-term Debt (times) |
2.4x |
4.1x |
|
Interest Coverage Ratio* (times) |
2.0x |
1.6x |
|
Average Cost of Borrowings (%) |
3.3% |
4.0% |
|
*Total debt includes perpetual debt, and interest expense includes the distribution to perps Source: Company's Announcement, iFAST Compilations Data as at 30 June 2023 |
||
As the high interest rate environment persists, the value of investment properties may fall to a certain extent as a result of the increase in the capitalization rate. Referring to Table 4, under the current scenario of capitalization rate plus an additional 200 basis points, the net debt/investment property is still only about 44.7%. The leverage level is still manageable. Even if its property assets depreciate significantly by about 55% due to other factors, it is still in a position to allow its creditors to get back the full principal amount, indirectly reflecting its overall credit risk is low.
Table 4: Credit Metrics Under Stress Testing
|
Value of Investment Properties |
Decline in % |
Net Gearing Ratio (%) |
Net Debt / Total Investment Properties (%) |
|
|
Cap Rate* + 100 bps |
HKD 79.9b |
-17.4% |
55.6% |
38.1% |
|
Cap Rate* + 200 bps |
HKD 68.1b |
-29.6% |
70.9% |
44.7% |
|
* Current Cap Rate Assumption (Median): HK Malls (5.4%), HK Offices (4.6%), HK Projects under Development (4.3%), Residential (3.8%), Mainland China (7.3%) Sources: Company’s Reports, iFAST Compilations Data as at 30 June 2023 |
||||
Investors Could Consider its 2027 Bond with a Yield To Maturity of 5.7%
The current credit rating of Hysan is BBB+ (Fitch), which belongs to the investment grade issuer. Given the company’s low leverage level, valuable investment properties and strong refinancing ability, the company’s default risk remains low even if there is downward pressure on rents and property valuations.
Therefore, investors could consider its 2027 bond, with a yield to maturity of 5.7% (see Table 5).
Table 5: Hysan’s 2027 Bond
|
Bond Name |
Years To Maturity |
Ask Price (Investors Buy) |
YTM (%) |
| HYSAN 2.875% 02Jun2027 Corp (USD) | 3.5 |
91.1 |
5.7% |
|
Source: Bondsupermart Data as at 1 December 2023 |
|||
Related Risks
If the high interest rate environment persists for a long period of time, it will put pressure on all sectors, even affecting the occupancy rate, rental revenues and valuation of properties. At the same time, Hysan's interest costs will gradually rise, which may affect its earnings and credit performance.
The downward pressure on the economies of China and Hong Kong will affect the occupancy and rental revenues of properties. Meanwhile, the reduction in base rents might result in a lower valuation of properties, leading to an increase in Hysan's leverage level.
If Hysan's operating cash flow is insufficient to cover the current interest expenses, the banks and creditors might question its solvency and increase its refinancing risk. If the financing channels are narrowed, Hysan might need to sell its investment properties for debt repayment in the long run, which will involve execution risk.
Conclusion
Hysan Development mainly engages in property investment and management. Its asset portfolio and development focus is in the Causeway Bay area of Hong Kong. The Caroline Hill Road project is currently in good progress and it is expected that 2027 onwards will be the "harvesting period" for the Company.
Regarding the industry outlook, Hong Kong office rents might continue to be under pressure. But the retail industry in Hong Kong is not that bad. The retail sales and rents should recover slowly going forward.
The overall operating performance of Hysan is fair. It is expected to be a bit weak going forward. However, the company’s investment properties are valuable. The actual leverage level is low. The overall credit risk remains low.
Investors could consider its 2027 bond, with a yield to maturity of 5.7%.Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.