Highlights:
- Meituan is a Chinese E-commerce platform, dedicated to building an ecosystem for amusement and enjoyment, and gradually improves the operating margins. Its current operating losses would be a short-term issue. In addition, thanks to the low profit margin room of food delivery, the food delivery services instead becomes Meituan’s moat.
- Meituan’s credit profile is remarkable, with a healthy gearing level and a strong financing ability. Even for the longer-term debt, its solvency remains strong.
- Investors can consider the USD bond due in 2025, with a current yield to maturity of around 5.2%. The bond is now available on Bond Express.
Meituan was dedicated to building an ecosystem for amusement and enjoyment
Meituan is a Chinese E-commerce platform. The main services include food-delivery, dining, entertainment, delivery and travel services.
The group was founded by Wang Xing in 2013 and listed on HKEX (Stock Code: 3690.HK) in 2018, with a current market capitalization of around HKD 926.0 billion.
Since inception, Meituan has been dedicated to building an ecosystem for amusement and enjoyment in China, becoming a platform to connect merchants and consumers. At the beginning, the Group established the food delivery service as a core business, and then expanded to others related to entertainment and food and beverage, including dining, hotel booking, other in-store services (medical aesthetics, pet care and healthcare) and retail.
The Group’s revenues are categorized into three segments:
(1) Food delivery
(2) In-store, hotel and travel
(3) New initiatives and others. Currently, revenue from this segment are primarily derived from B2B food catering services, micro-financing services, Meituan Insta-shopping and bike sharing and moped services.
In 2021, all three segments delivered strong revenue growth, with YoY revenue increase of 45%, 53% and 84% respectively (see Table 1). The Group’s revenue increased significantly by 56% YoY to RMB 179.1 billion, but it recorded a net loss of RMB 23.5 billion, mainly due to the larger investments in developing its new initiatives and others business segment.
Food delivery services are the Group’s biggest revenue source, currently contributing around 54% of total revenue. Although the operating margin of food delivery services was low at 6.3%, the Group positions the food delivery services as “attracting inflows”, for the purpose of attracting new customers to use Meituan’s other services and increase its customer stickiness. Therefore, the lower operating margin can be seen as part of the Group’s operating strategy.
Table 1: Revenue and Operating Profit of Meituan and the segments
|
(RMB billion) |
2021 |
2020 |
YoY Growth |
|
|
The Group |
Total revenue |
179.1 |
114.8 |
56% |
|
Operating profit |
-23.1 |
4.1 |
N/A |
|
|
Food delivery |
Total revenue |
96.3 |
66.3 |
45% |
|
Operating margin |
6.4% |
4.3% |
+2.1 ppt |
|
|
In-store, hotel & travel |
Total revenue |
32.5 |
21.3 |
53% |
|
Operating margin |
43.3% |
38.5% |
+4.8 ppt |
|
|
Source: Company Reports, iFAST Compilations Data as of 31 December 2021 |
||||
The
Group turned the operating profits into losses. However, this was mainly due to
the Group deploying more resources in the new
initiatives and others segment, resulting in huge operating costs. The
operating margin of this segment was even expended further from -39.8% to -76.4%.
We believe that these investments can gradually translate into future revenue growth drivers and improve their operating margins – similar to businesses like food delivery and dining, hotel and travel services that have gradually improved their operating margins. Thus, the current operating losses would just be a short-term issue.
Thanks to the low profit margin room of food delivery, it becomes Meituan’s moat
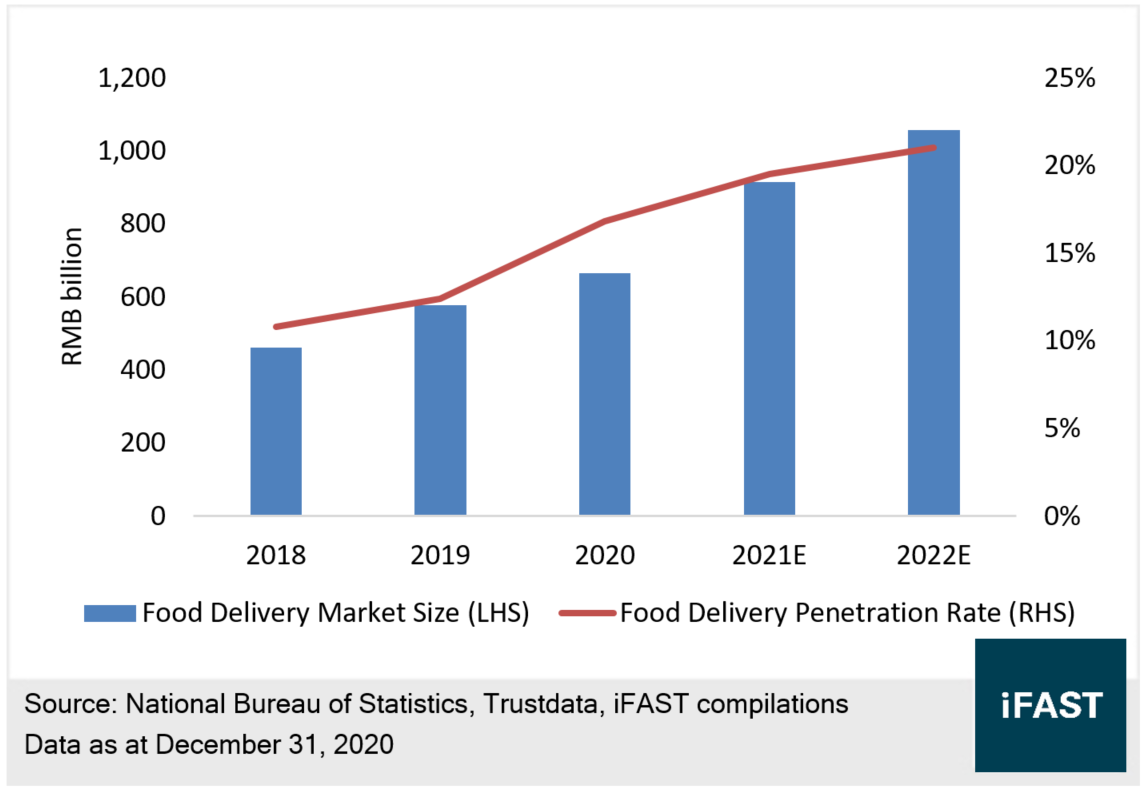
Meituan is the industry leader of food delivery services in China. As shown in Chart 1, Meituan’s 2020 market share was around 67%, far away from the second one, ELEME Inc. Along with a consistent increase in the penetration rate of food delivery (see Chart 2), the market size is expected to achieve RMB 1 trillion in 2022, and Meituan should benefit from this industry’s tailwind.
Chart 1: Chinese food delivery market share
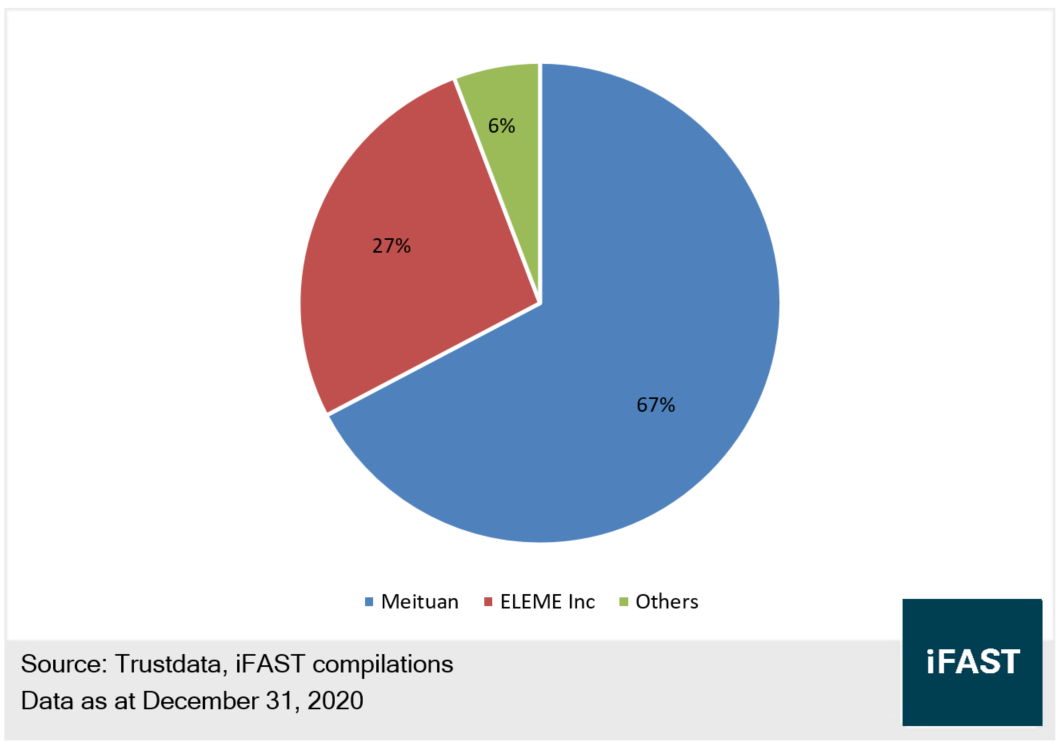
Chart 2: Chinese food delivery market size and penetration rate
It is highlighted that the food delivery industry has a high barrier to entry. This is mainly due to higher transportation and labor costs, some technological requirements (mapping and searching system etc.), the money and time cost of building the service platforms and the participation of merchants. These series of costs, together with low pricing power in general food delivery services, result in a low profit margin. It requires a certain scale to achieve a positive profit. As such, as an absolute industry leader, Meituan has a dominant position. The food delivery services have now become its moat.
Meituan’s credit profile is remarkable, with a healthy gearing level and strong financing ability
As shown in Table 2, as of end December 2021, Meituan’s liabilities to assets ratio was 47.8%, which was a level under control. The Group had a low net gearing ratio of 6.7%, meaning its gearing level remained quite healthy. Further to that, it also held up to RMB 45.8 billion in cash and RMB 84.3 billion in short-term treasury investments. As such, even though partial Group’s new initiatives and others businesses are generating operating losses (2021 adjusted EBITDA loss was around RMB 9.7 billion), these should not have a material impact on its credit profile.
Table 2: Meituan’s credit indicators
|
2021 |
2020 |
|
|
Liabilities to Assets Ratio (%) |
47.8% |
41.4% |
|
Net Gearing Ratio (%) |
6.7% |
Net cash |
|
Total Debt (RMB billion) |
54.2 |
24.1 |
|
Total Cash (RMB billion) |
45.8 |
29.9 |
|
Short-term Treasury Investment (RMB billion) |
84.3 |
44.0 |
|
Cash to Short-term Debt (times) |
4.0 |
4.0 |
|
Source: Company Reports, iFAST Compilations Data as of 31 December 2021 |
||
Another highlight of Meituan is its strong financing ability. In April 2021, the Group raised over USD 10 billion through the issuance and allotment of new shares and the issuance of convertible bonds. The Group issued and allotted 187 million shares at HKD 273.8 per share, and issued USD 3 billion convertible bonds (with an exercise price of HKD 431.24). This was the largest share allotment activity in the Hong Kong market.
Despite a recent plunge in the Group’s stock price, it remains a favourable choice amongst investors. Its equity financing ability remains strong. Without impacting its credit profile, the Group can develop and invest in more new initiatives and others businesses, which serve as the Group’s long-term drivers but are in deficit in the near-term.
Investors could consider the bond due in 2025, with a current yield to maturity of around 5.2%
As an issuer, Meituan is considered investment grade, with credit ratings of BBB- / BBB- (S&P / Fitch). As shown in Table 3, there are two Meituan bonds available on Bondsupermart – including the bonds due in 2025 and 2030.
Table 3: Meituan’s USD bonds
|
Bond Name |
Years to Maturity |
Yield to Maturity |
Ask Price (Investor Buys) |
|
MEITUA 2.125% 28OCT2025 CORP (USD) (Bond Express New Member) |
3.6 |
5.2% |
90.0 |
|
MEITUA 3.050% 28OCT2030 CORP (USD) |
8.6 |
6.0% |
80.5 |
|
Source: Bondsupermart Data as at 1 April 2022 |
|||
With the factors such as its low gearing ratio, strong financing ability and up to RMB 84.3 billion short-term treasury investments available to be sold, we believe that its credit profile is remarkable. The default risk remains under control for its middle- and longer-term bonds.
However, for now, Meituan's 2030 bond is only yielding about 50 basis points higher than its 2025 bond. We think that the 2030 bond does not sufficiently factor in the higher interest rate risk given the longer tenor. Therefore, investors could first consider the 2025 bond, with an attractive yield to maturity of 5.2%.
Related Risk
With the anti-monopoly crackdown, new regulatory policies will continue to be introduced. These might affect Meituan’s future growth outlook and ability to finance through equity. In addition, news related to regulation changes and crackdowns could make the bond price volatile. In an extreme case, taking reference from the restructuring of the Chinese Education industry, if the Group is unable to continue operating, the repayment ability would be materially impacted.
As the coronavirus persists, it might adversely affect the group’s consumer-related businesses. If the pandemic does not end soon, the Group would face greater cash flow pressure, and costs related to COVID-19 would increase.
Meituan continues to invest in new initiatives and others businesses, incurring more short-term expenses. Besides, the visibility of these new initiatives is low, which might not be able to drive the Group’s future growth as expected.
Conclusion
Meituan is a Chinese E-commerce platform, dedicated to building an ecosystem for amusement and enjoyment, and gradually improves the operating margins. Its current operating losses would be a short-term issue. In addition, thanks to the low profit margin room of food delivery, the food delivery services instead becomes Meituan’s moat.
Meituan’s credit profile is remarkable, with a healthy gearing level and a strong financing ability. Even for the longer-term debt, its solvency remains strong.
Investors can consider the USD bond due in 2025, with a current yield to maturity of around 5.2%. The bond is now available on Bond Express.