About the new issue
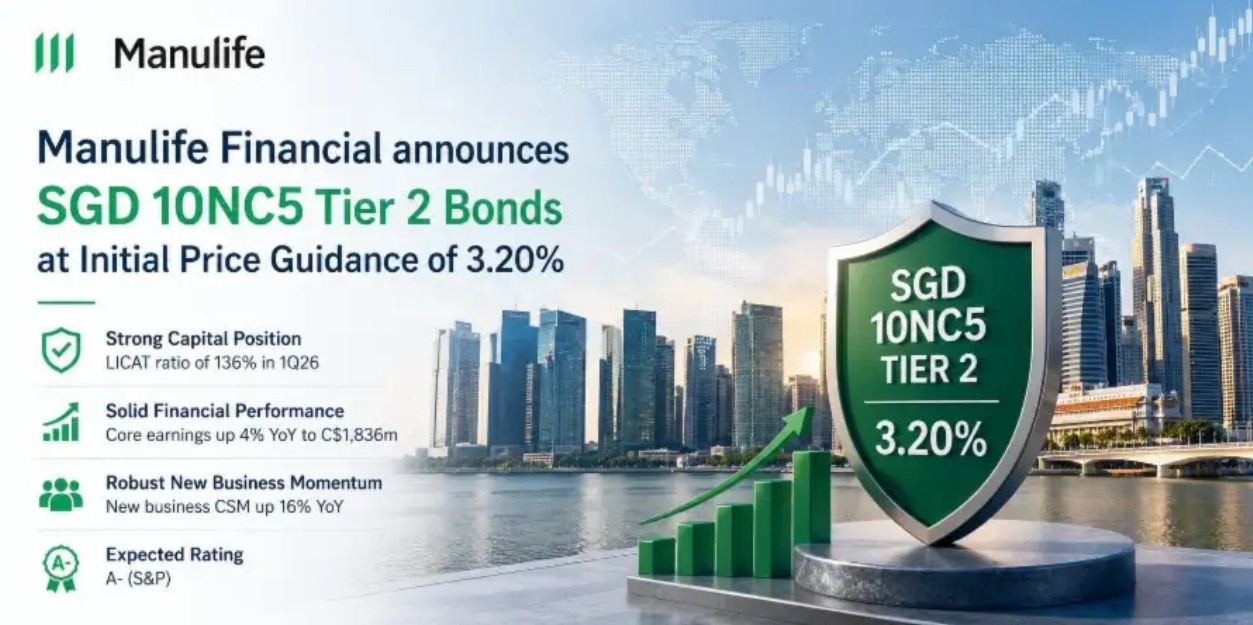
Manulife Financial Corporation (MFC) plans to issue new SGD 10NC5 Tier 2 bonds at an initial price guidance (IPG) of 3.20%, for accredited and institutional investors only. These Tier 2 bonds will be unsecured and subordinated. They may be redeemed on the first call date (04 June 2031) and each interest payment date thereafter.
The issuer is rated A (Stable) by S&P, and the new issue is expected to be rated A- by S&P. Proceeds from this new issuance will be used for general corporate purposes, including investment in subsidiaries and potential future redemptions of existing securities.
Financial highlights
Manulife delivered a solid quarterly performance in 1Q26. On an IFRS basis, total insurance service result grew 12% y/y to C$1,164m, supported by higher contractual service margins (CSM) recognised. Total investment service results improved a -C$364m (loss) in 1Q25 to C$417m in 1Q26, due to stronger reinsurance finance income and less negative insurance finance expense (both not recorded under core earnings below). Overall, Manulife’s net income after tax rose 98% y/y to C$1,236m, supported by broadly stable costs.
Furthermore, Manulife’s core earnings* (non-GAAP) growth remained intact despite a volatile market backdrop. Core earnings rose 4% y/y to C$1,836m. This was primarily driven by a 16% improvement in its core net insurance service result to C$1,070m, helped by higher CSM recognition. By contrast, core net investment result fell -8% to C$837m, due to lower expected investment earnings.
(*Core earnings include ‘recurring’ earnings derived from Manulife’s different businesses, including insurance, wealth management, and banking. It excludes more volatile items like market experiences gains/losses.)
New business momentum was solid and should support Manulife’s future profitability. APE sales rose 7% to C$2,821m, new business CSM rose 16% to C$1,019m, and new business value rose 7% to C$944m. Manulife’s CSM balance reached C$25,589m as of March 2026, up 2% q/q from end-2025, or 15% from March 2025. The higher CSM balance may not translate into a stronger performance immediately, but we expect its benefits to flow through in subsequent quarters.
Management disclosed that a 10% decline in public equity markets would reduce CSM (net of non-controlling interests) by $660m and net income after tax by $430m. Its sensitivities are largest to the S&P 500 Index (US), followed by MSCI Asia and EAFE excluding Japan. While these would certainly affect Manulife’s reported earnings, we think it remains manageable relative to Manulife’s core earnings base of C$1,836m in one quarter (1Q26) and CSM balance of C$25,589m.
Credit highlights
Manulife’s capital position remains strong. Its Life Insurance Capital Adequacy Test (LICAT) ratio was reported at 136% in 1Q26, extending a streak of stability (1Q25 – 1Q26: LICAT ranged from 136% - 138%). Based on Manulife’s sensitivity disclosures, a 50 bps decline in interest rates would reduce the LICAT ratio by just 1 pp, while a 50 bps corporate spread tightening would reduce LICAT by 3 pp. Either way, Manulife’s LICAT ratio would remain comfortably above the regulator’s (OSFI) supervisory target of ~100%, equivalent to about a C$25b buffer.
Manulife’s leverage remains conservative, with a leverage ratio of 22.5% in 1Q26. This marked a notable decline (improvement) from 23.9% in both 1Q25 and 4Q25, while remaining below management’s 25% medium-term target. We view this as a positive development, especially as the improvement in leverage came despite ~C$1.2b in shareholder distributions (dividends and buybacks) during the quarter.
Its underlying asset quality remains sound. Total invested assets stood at C$461.8b as of 1Q26, with its largest exposures to corporate bonds (28%), government bonds (18%), and mortgages (13%). 96% of its total debt securities and private placements were investment-grade, with 69% rated A or higher.
About C$52.4b (11%) of assets were in private placements, with a focus on investment-grade placements (average rating: A). Private credit and mezzanine debt exposure (encapsulated under private placements) was small at C$5.1b (~1% of assets), with a large majority (90%) in senior positions and valued quarterly independently. Overall, management appears confident that its private credit exposure remains very much manageable.
Risks
These bonds are subject to the usual risks associated with Tier 2 subordinated instruments. However, we have not identified explicitly & direct contractual loss-absorption features such as principal write-down or equity conversion, nor explicitly & direct interest or principal deferral mechanisms. Instead, the key risk appears to primarily stem from their subordinated ranking versus senior debt, and hence the possibility of impaired recovery in an insolvency scenario.
We also highlight the possibility of non-calls, though the likelihood remains small. We generally expect Manulife to call these bonds on its first call date, barring a significant deterioration, due to an economic disincentive arising from the amortisation of the bond beginning from the first call date.
Bond comparison
This new issue’s 3.20% IPG represents a ~126 bps pickup over the prevailing 5y SORA of 1.94%, or a 145 bps pickup over the prevailing 5y SGS yield of 1.75%. We also note that the final price guidance (FPG) is likely to come in lower than the 3.20% IPG.
Manulife currently has one existing set of SGD bonds: MFCCN 4.275% 19Jun2034 Corp (SGD), which matures in just over 3 years. We also include other peer comparisons, especially other Tier 2 bank (non-insurance) bonds.
The existing Manulife 2034 bonds are trading at around 2.3% (70 bps over SGS), while the AIA and Prudential bonds are trading at around 3.0% (100+ bps over SGS). We also note that the AIA and Prudential bonds have longer tenors than this new Manulife issuance. Taking these into account, the new Manulife bonds may look relatively attractive considering their spreads over government bonds.
Furthermore, we look at SGD bank (non-insurance) bonds, which are similarly rated (A-) or with slightly lower ratings (BBB or BBB+). We find that other bank bonds rated A- generally trade at lower yields, including the longest-tenor WSTP 3.000% 19May2038 Corp (SGD) example below. Lower-rated bank bonds from French issuers, meanwhile, offer similar levels of yields (~3%) despite the lower rating. The Manulife bonds may therefore again look relatively attractive to these.
(Note: A- rating represents the highest within the SGD space, for Tier 2 bonds.)
Table 1: Bond comparison (new issue bolded)
| Bond Name | Reset / Maturity Date (Years to Reset / Maturity) |
Ask Price | Yield to Worst** | Credit Rating (S&P / Moody's / Fitch) |
| Manulife New Issue (2036)* | 04 Jun 2031 / 04 Jun 2036 (5.0 / 10.0) |
100.000* | 3.20%* | A- / - / - |
| MFCCN 4.275% 19Jun2034 Corp (SGD) | 19 Jun
2029 / 19 Jun 2034 (3.1 / 8.1) |
105.788 | 2.31% | A- / - / A- |
| AIA 3.580% 11Jun2035 Corp (SGD) | 11 Mar 2035 / 11 Jun 2035 (8.8 / 9.0) |
104.342 | 3.01% | - / A2 / - |
| PRUFIN 3.800% 22May2035 Corp (SGD) | 22 Feb
2035 / 22 May 2035 (8.8 / 9.0) |
106.133 | 3.00% | A- / A3 / - |
| WSTP 4.650% 07Sep2032 Corp (SGD) | 07 Sept 2027 / 07 Sept 2032 (1.3 / 6.3) |
103.175 | 2.12% | A- / A3 / - |
| ANZ 4.500% 02Dec2032 Corp (SGD) | 02 Dec
2027 / 02 Dec 2032 (1.5 / 6.5) |
103.450 | 2.18% | A- / A3 / A- |
| ANZ 3.750% 15Nov2034 Corp (SGD) | 15 Nov 2029 / 15 Nov 2034 (3.5 / 8.5) |
103.758 | 2.61% | A- / A3 / A- |
| WSTP 3.000% 19May2038 Corp (SGD) | 19 May
2033 / 19 May 2038 (7.0 / 12.0) |
99.700 | 2.99% | A- / A3 / A- |
| ACAFP 4.250% 14Jan2035 Corp (SGD) | 14 Jan 2030 / 14 Jan 2035 (3.6 / 8.6) |
104.342 | 2.98% | BBB+ / Baa1 / A- |
| BPCEGP 4.600% 21Jan2035 Corp (SGD) | 21 Jan
2030 / 21 Jan 2035 (3.7 / 8.7) |
105.242 | 3.07% | BBB / Baa2 / BBB+ |
| BNP 3.950% 15Apr2035 Corp (SGD) | 15 Apr 2030 / 15 Apr 2035 (3.9 / 8.9) |
103.575 | 2.97% | - / Baa2 / A- |
| ACAFP 3.300% 25May2038 Corp (SGD) | 25 May
2033 / 25 May 2038 (7.0 / 12.0) |
99.947 | 3.28% | BBB+ / Baa1 / A- |
| Source: Bloomberg, Bondsupermart, iFAST
compilations. Data as of 25 May 2026. *Bond is not yet issued, 3.20% yield is only an initial price guidance and may fall on issuance. |
||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds positions in MFCCN 4.275% 19Jun2034 Corp (SGD) and ANZ 4.500% 02Dec2032 Corp (SGD). The analyst who produced this report hold NIL positions in the abovementioned securities. This research report was prepared with the assistance of artificial intelligence (AI) tools. iFAST Financial Pte Ltd does not rely exclusively on AI for content generation; the content of this report – including all investment theses, ratings, price targets and conclusions – has been independently reviewed and verified by the research analyst(s) to ensure accuracy and professional integrity.