In this series of articles, we provide an overview of issuers currently on our watchlist, including the latest developments and our commentary on each issuer.
|
Company |
Latest Developments |
Related article |
Comment |
|
Tan Chong Motor Holdings Berhad |
- In 1H26, the Group's performance remained under pressure, with revenue declining 14.9% YoY to RM929.6 million. - The Group’s loss before tax narrowed to RM39 million, mainly due to a RM20.1 million gain recognised on the disposal of an asset classified as held for sale. - Tan Chong has signed a three-year master agreement with Perodua Sales to provide ED coating and painting services, as well as rent out designated assembly lines for Perodua’s BEV project. |
- We maintain a negative view on Tan Chong’s business outlook, as we expect sales to remain under pressure amid intensifying competition in Malaysia’s automotive industry. - However, we view that the agreement with Perodua Sales to lease out its assembly lines has improved Tan Chong’s ability to redeem its March 2027 tranche. - We will continue to monitor the group’s latest developments and keep investors updated should there be any material updates. |
|
|
Tropicana Corp |
- In 1H26, revenue increased by 97% YoY to RM1,164 mil, driven by a one-off gain on the disposal of three land parcels, together with stronger progress billings. - Bottom line remained in the red, attributable to mark-to-market loss on quoted shares amounting to RM23.1 million, which was a non-cash item. Excluding this, the group would have recorded a higher profit before tax of RM32.2 million. - Tropicana has been actively deleveraging through asset monetisation and project completions, demonstrating continued commitment to debt reduction. - Possess a sizeable landbank of 1,349.7 acres across Malaysia, with an estimated GDV of RM102.6 billion as of June 2026. - Tropicana has announced that it will not exercise the call option on its perpetual securities, which have a next call date of 15 September 2026. Management cited delays in land sales as the reason for the decision.Consequently, the coupon rate has stepped up to 8.6%. |
-Anticipate continued improvement in the group’s profitability and balance sheet, with expansion in Johor serving as a key catalyst for future revenue growth. - Despite the non-call event, we believe Tropicana’s repayment capacity remains intact at this juncture, supported by its ongoing deleveraging efforts, sizeable unbilled sales and substantial landbank. |
|
|
Serba Dinamik |
- The liquidation process remains ongoing. As of today, there has been no major breakthrough or definitive restructuring outcome announced. - The liquidator of Serba Dinamik has filed a lawsuit against former external auditor KPMG, claiming that KPMG failed to perform sufficient audit procedures and should have identified financial misstatements earlier. - The liquidator is seeking at least RM1.56 billion in damages + interest. |
NiL |
-The lawsuit introduces a potential additional source of recovery value for creditors should the liquidator successfully secure compensation from KPMG. -However, given Serba Dinamik’s substantial debt burden relative to its asset base, the overall recovery prospects remain highly uncertain. -Considering the uncertainties surrounding the litigation outcome, asset realisation process and liquidation timeline, potential recovery value remains fuzzy. |
|
Pestec International Berhad (deferred coupon x 3) |
-1QFY27 (30 Jun 2026) was a rough quarter, with revenue plunging 82% YoY to RM21.4m as the Iraq and Cambodia projects wound down. The Group swung to a RM19.3m pre-tax loss from RM171.2m profit a year earlier, although the latter was boosted by a one-off debt-waiver gain. -Cash is also thinning, falling to RM57.1m from RM71.2m as at 31 Mar 2026. The auditor flagged that the Group may need to rely on parent support from Dhaya Maju to continue operations. -The group has announced the deferment of perps coupon from 17 Apr to 16 Oct 2026, marking the third deferral. Given the current financial situation, we are of the view that further coupon deferment may continue. -The Trustee pushed for a financial adviser to be appointed to review the Issuer's financial position and look into available financing options, and Pestec has since appointed one. Engagement is still ongoing and progress is being tracked on its repayment proposal. |
Nil |
- We are negative on Pestec’s ability to service coupon payments and principal redemption. - We will continue to keep investors updated should there be any firm decision or outcome from the issuer. |
|
YNH Property Bhd (deferred coupon x 2) |
- On 23 July 2026, YNH announced its second coupon deferral exercise for both outstanding perpetual securities tranches, deferring a combined RM34.41 million in coupon payments to preserve cash reserves for its active development pipeline and operational needs. - Based on FY26 (June 2026), revenue decreased significantly by 71% YoY, from RM391.6 million to RM112.6 million, mainly due to the disposal of 163 Retail Park in 2QFY25 (December 2024), which generated RM215 million in revenue and resulted in a high base in the previous year. - YNH recorded a loss before taxation of RM105.3 million, mainly due to a one-off impairment of RM35 million on other receivables and a RM38.5 million provision for foreseeable losses on projects. - YNH’s liquidity position remains constrained. As of FY26, the Group’s available cash of RM47.7 million remains insufficient to fully cover its short-term debt maturity of RM367.3 million due within one year. -YNH Property has extended the deadline for its RM170 million land sale to Sunway to 31 December 2026, marking the sixth extension since the deal was announced in May 2023. |
YNH Property Quick Update – Defers Perpetual Securities Coupon for a Second Time |
- The proposed disposal is expected to
bring some liquidity to the balance sheet. - Despite that, we maintain our negative view on YNH. Tight liquidity, subdued revenue recognition, and continued reliance on asset disposals to meet debt obligations remain key credit concerns. |
|
Zetrix AI |
- Zetrix is now increasingly focused on blockchain and AI, with the key concern being whether its sizeable development costs can be monetised to generate sufficient cash flow to support its higher debt burden. - On 28 September 2026, external auditor TGS TW PLT resigned. - On 5 October 2026, JPJ suspended MYEG and Zetrix AI as collection agents over RM314 million in outstanding government collections from 19 May to 30 September 2026. A RM231 million cheque was not processed following instructions from the companies, prompting MOT/JPJ to pursue legal action. Zetrix AI is in discussions with JPJ to resolve the matter. - As of 15 October 2026, Mr Wong Thean Soon’s combined direct and indirect shareholding had declined significantly to 1.895%, raising concerns about compliance with the sukuk programme’s ownership requirements. The issuer has until 22 October 2026 to remedify. - We are still seeking for further clarifications from the issuer team, given the severity of the issues highlighted above, we are turning negative on Zetrix ability to repay the 2027 bonds as usual.
|
-Given the recent auditor resignation, JPJ suspension and reported RM314 million in outstanding obligations, we have turned negative on Zetrix AI’s debt-servicing capacity, amid heightened concerns over its liquidity, financial transparency and ability to refinance its 2027 bond maturity. -Investors may consider disposing of their holdings, although limited secondary-market liquidity could constrain execution.
We will continue to monitor developments closely and provide updates as more information becomes available.
|
|
|
Evergrande |
- Evergrande has officially entered a forced liquidation, and Alvarez & Marsal is the liquidator to handle the asset disposal. - Capability of liquidator is key to max recovery value for debtholders. Liquidators have experience in Lehman Brother and Luckin Coffee. - Hong Kong regulators fines PwC HKD1.3 billion over Evergrande audit work. - Pacific Alliance Group (PAG) is in exclusive talks to acquire Evergrande Property Services’ 51.016% stake, with exclusivity running until 27 October 2026. A successful sale could generate additional recovery proceeds. -Liquidators are pursuing approximately US$8.5bn in damages against PwC, alleging that audit failures allowed Evergrande’s materially overstated financial statements to go undetected, contributing to losses suffered by the company. |
A List of 30 Key Chinese Developers’ Latest Development (Updated on 8 May) |
-The liquidation process is still ongoing, and we posit that it will take a couple of years to complete due to its scale.
-Offshore bondholder recoveries are expected to remain very low given the limited assets realised and their structural subordination to onshore creditors. The PwC lawsuit represents the main potential source of material upside, while the proposed asset sale may provide incremental proceeds. |
|
Century Sunshine |
-Trading in CENSUN shares has been suspended since 1 April 2025 due to the company’s failure to release its 2024 Annual Report on time. -No dividend was declared for the third scheme year, as the proceeds from the share disposals were insufficient to cover the scheme costs. -There is still no decision on whether the Zhangzhou Land should continue to be reserved for the bridging loan or be disposed of. -The Luozhuang Government unilaterally terminated the relocation agreement on the ground that Shandong Hongri failed to carry out soil remediation. Shandong Hongri appealed the decision, arguing that the termination is unjustified because no clear remediation standards had been provided. - One of Shandong Hongri’s creditors obtained an enforcement ruling ordering the auction of part of its land-use rights. The land is to be auctioned as “industrial land,” resulting in a significantly depressed valuation. Shandong Hongri has filed objections and applied to revoke the enforcement ruling and to stay the auction proceedings. - At this juncture, the unilateral termination of the Relocation Plan remains under administrative review, which is currently suspended pending the determination of the Retrial Application. Separately, the judicial auction has not taken place and remains on hold. |
Restructuring Update: Century Sunshine’s Third Scheme Year (2026) |
-Given that there are no other available assets, we hope the land title conversion of the Shandong Land will be successfully completed, as it is likely to unlock higher value when the land is disposed of after the conversion. |
In the next section, we will delve into the insights of the yield curves for Malaysian Government Securities (MGS), US Treasuries (UST), Singapore Government Securities (SGS) and Australia Government Securities (AGS).
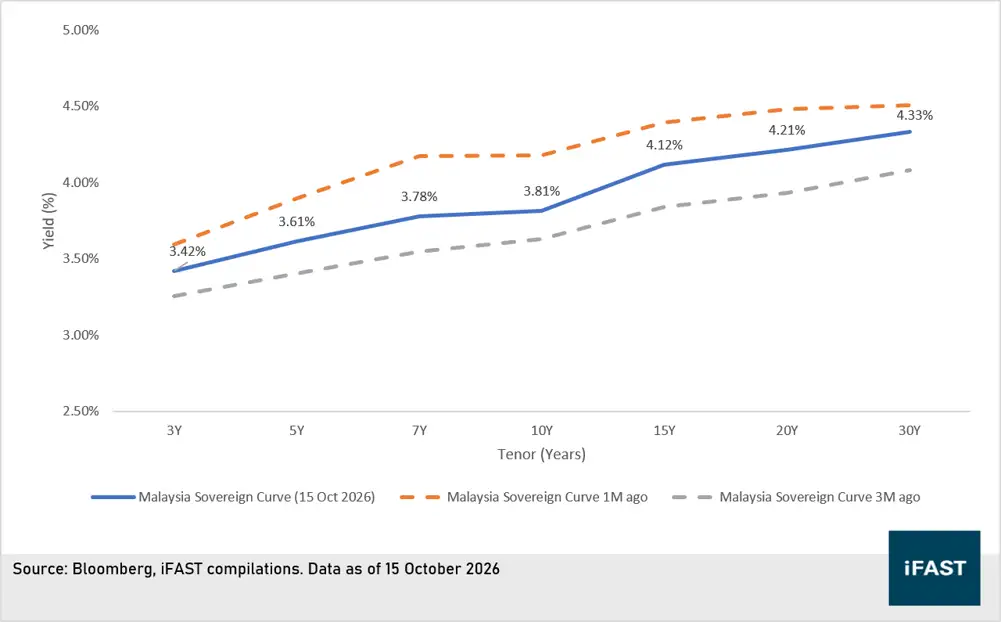
Our view on MGS:
1) The sharper-than-expected increase was mainly driven by the renewed escalation in the US-Iran conflict, which pushed crude oil prices higher and raised concerns over global inflation, indirectly pushing risk premium higher. Yield movement has since moderated a little compared to 1 month ago.
2) We expect BNM to keep the OPR (2.75%) unchanged through 2026, as resilient domestic growth with manageable inflation.
3) We see little room for MGS yields to retrace lower in 2H26, as global yield repricing and domestic political uncertainty continue to weigh on market sentiment with risks tilted to the upside.
4) We prefer the short-to-medium segment of the curve, particularly the 3–5-year tenor as political uncertainty continues to overweight other positive developments like fiscal consolidation.
Chart 1: MGS Curve
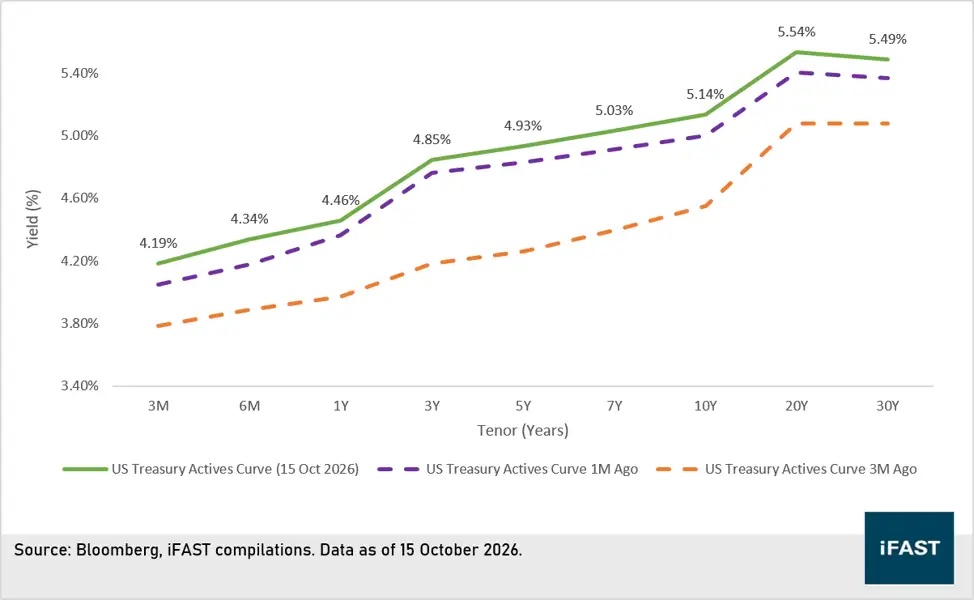
Our view on UST:
1) Following the rate hike in September, another hike remains on the table, mainly driven by sticky inflation and our view that inflation will remain higher for longer. At this juncture, market is still pricing in another 2-3 rate hikes in 2027.
2) We favour short and medium-duration bonds:
· Short-term: low sensitivity to interest rate movements.
· Medium-term: On selective basis (focusing on companies with strong balance sheets and good fundamentals)
Chart 2: UST Yield curve
Our view on SGS:
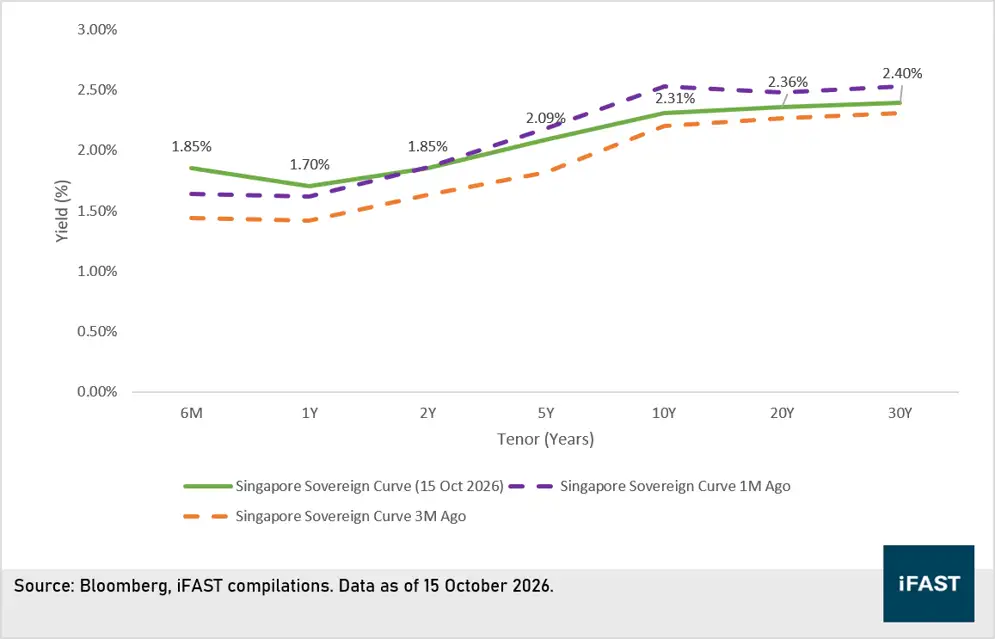
1) Singapore interest rates are expected to remain rangebound with an upward bias, as potential global rate hikes provide upward pressure, while continued safe-haven and wealth inflows help anchor yields.
2) For bond recommendations, we favour:
- Short-term SG T-bills: Rolling 6-month to 1-year T-bills to remain nimble amid the uncertain rate environment.
- SGD financial corporate bonds: Tier 2 bank bonds, particularly investment-grade bonds issued by strong global banks.
- SGD non-financial corporate bonds: Quality issuers, with the 3–5 year tenor being the sweet spot, where the yield pickup is most attractive.
Chart 3: SGS Yield curve
Our view on AGS:
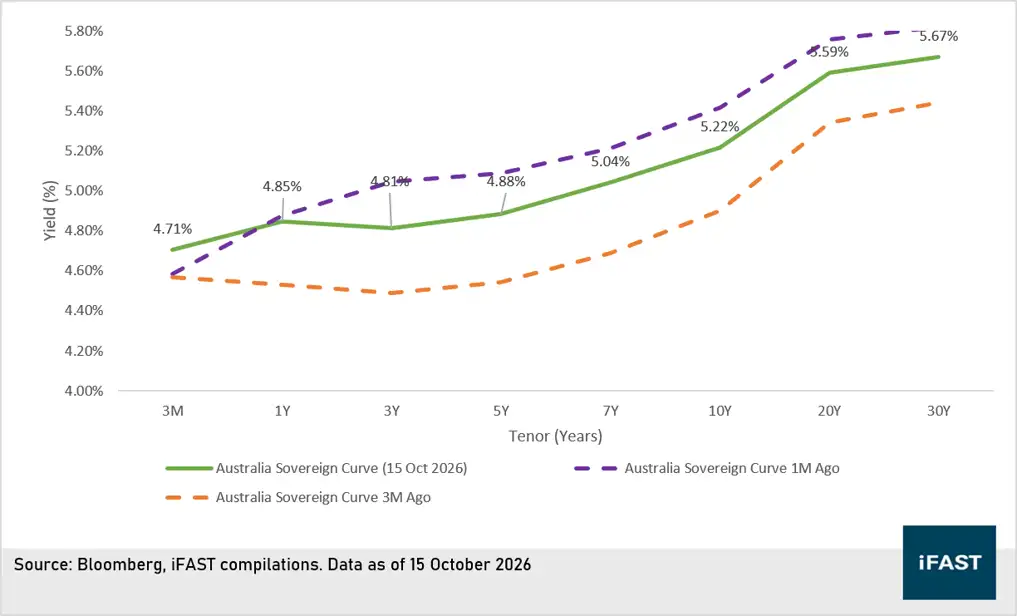
1) The RBA hiked again as inflation re-accelerated. August headline CPI rose to 4.0% y-o-y (from 3.5% in July) on energy and goods, while trimmed mean stayed sticky at 3.6%. The RBA lifted the cash rate 25bp to 4.60%, its fourth hike this year, with no signal that the cycle is over.
2) We think 4.60% is at or near the peak. Policy is restrictive and demand is cooling: household spending was flat in August and unemployment rose to 4.6%. However, one more hike is possible if the Q3 CPI (28 October) shows core inflation persisting.
3) We reiterate our preference for high-quality bonds and the barbell strategy. We favour short (around 1-year) and longer (7- to 10-year) tenors, building long-end positions gradually given global term premium risk.
Chart 4: AGS Yield curve
Some of the Credit Announcement by RAM & MARC (as of 30 Sep 2026)
RAM
1) Upgrades Sunway REIT’s CCR to AA1/Stable; related debt issue ratings also upgraded
2) Assigns AAA/P1 ratings to Suria Capital Holdings Berhad
3) Affirms TIME dotCom’s AA1 sukuk rating
4) Affirms AA3 rating of Tanjung Bin Energy’s RM4.5 bil sukuk
5) Affirms Johor Plantations’ AA1/Stable/P1 ratings
6) Affirms Ranhill Solar Ventures’ sukuk at AA3
7) Affirms CelcomDigi Telecommunications’ AAA/Stable sukuk rating
8) Assigns final AAA rating to KIP REIT Capital’s 2026-Issue 6 Class A MTN
https://www.ram.com.my/news-events/?tab=list-ratingannouncement
MARC
1) Affirms Alam Flora’s MARC-1IS/AAIS sukuk ratings
2) Affirms Tropicana’s positive ratings outlook
3) Upgrades ratings on Sunway Group’s issuances
4) Assigns rating of AA-IS to Mah Sing’s RM2.0 billion Sukuk Murabahah Programme
5) Affirms AA-IS rating on Guan Chong’s RM800.0 million sukuk programme
6) Places Zetrix AI’s rating on MARCWatch Developing
7) Assigns preliminary rating of AIS to Winstar’s proposed IMTN Programme
8) Revises JB Cocoa’s outlook to positive
9) Affirms Celcom Networks’ AAAIS rating
https://www.marc.com.my/insights/rating-announcements/
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in CENSUN 7.000% 03Jul2020 Corp (SGD), EVERRE 8.250% 23Mar2022 Corp (USD), EVERRE 7.500% 28Jun2023 Corp (USD) and the analyst who produced this report hold a NIL position in the abovementioned securities.