


- Based on our Asia macro and earnings outlook, we expect lower stress and healthy fundamentals for Asia high yield issuers this year. We also hold a constructive view on China's real estate sector, which should lay a positive backdrop for China high yield issuers.
- Asia high yield provides strong coupon return, offering handsome yield pick-ups over peer segments. Valuation for the asset class remains cheap, with spread close to one standard deviation above historical average. We expect ample room for tightening, back to near pre-Covid levels, driving upside for price return.
- Interest rate risk remains muted given lower duration and high yield per unit duration. Default risk is subsiding and will be manageable with current spread compensating well for undertaking such risk. We view risk premia offered by Asia high yield to be very attractive.
- Asia high yield is one of our top fixed income pick for 2021 and current yield/ spread presents good entry opportunity.
Higher-yielding, riskier debt has been on a tear since late 4Q20. Expectations of a continuance in low policy rates, braced by mounting risk sentiment have emboldened investors to venture beyond traditional safe havens such as treasuries and investment grade bonds.
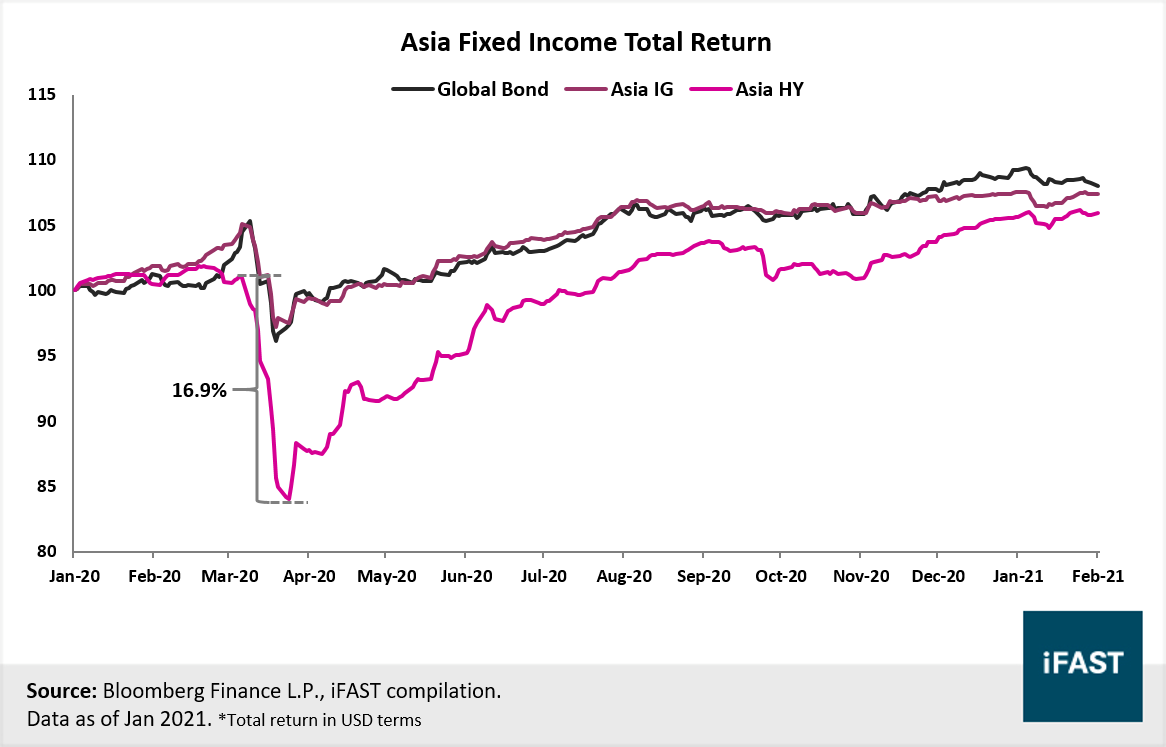
Amongst the riskier higher yielding segments, our preference remains tilted to Asia high yield (HY). The asset class was hit dramatically back in March 2020 (chart 1), when Covid-19 fears rippled from Asia, but has since underwent a rigorous rebound.
As we explore attractive credit opportunities in 2021, Asia HY stands out strongly given a multitude of favourable tailwinds and manageable risks (outlined in the following sections). Peering further into 2021, we believe the asset class can be a gem in the fixed income space.
Chart 1: Asia HY was hit hard back in Mar ’20 but has since rebounded valiantly
Excellent yield pickup opportunity
Part of the allure for Asia HY, even over its HY peers, is its attractive coupon return. Most fixed income segments are offering paltry levels of yield, with many just a thread above their historical minimum (chart 2).
In our view, Asia HY is amongst the best asset class to harness yield. Given a beefy yield offering of 6.6%, coupon return easily best its fixed income peers (chart 2) and bond proxies. Despite drastic retracement in credit spreads since March ‘20 and lately in November ’20, Asia HY’s yield is only marginally below its long-term average of 7.1%.
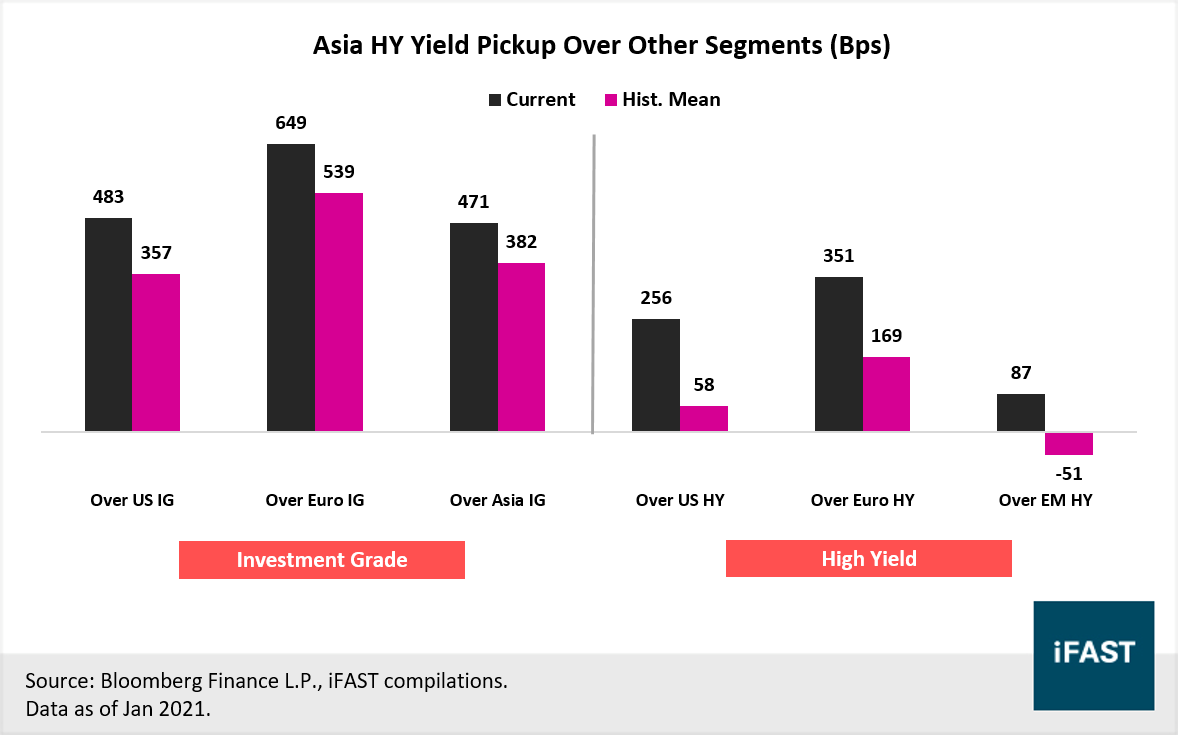
The asset class also offers handsome above-average yield pick-ups over IGs and even HYs peers (chart 3). Against the former, Asia HY offers a pick-up of 470 – 650 bps, and against the latter, it offers a pick-up of 90 – 350 bps. We view the decent pickup against other HY segment as significant because it meant that additional coupon return generated by Asia HY do not come at the cost of higher credit risk.
Chart 2: Asia HY offers the highest yield on a relative basis …
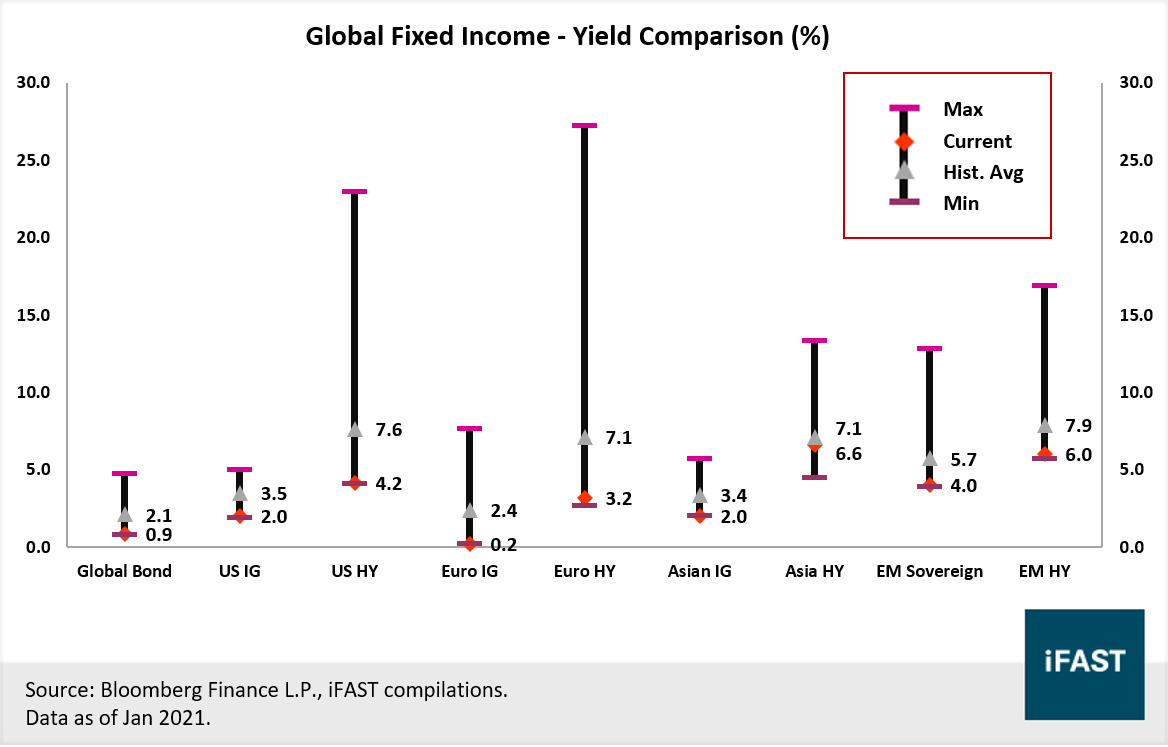
Chart 3: … yield pickup over both IG and HY are also substantial
Cheap valuation and potential for further spread compression
Akin to equity markets, valuation (in terms of spread) is no longer cheap for most fixed income segments (chart 4). Credit spread for HYs have retraced drastically, reflecting improving fundamentals as well as dissolving liquidity and default concerns. Despite so, we continue to find Asia HY to be one of the scant few that offers value.
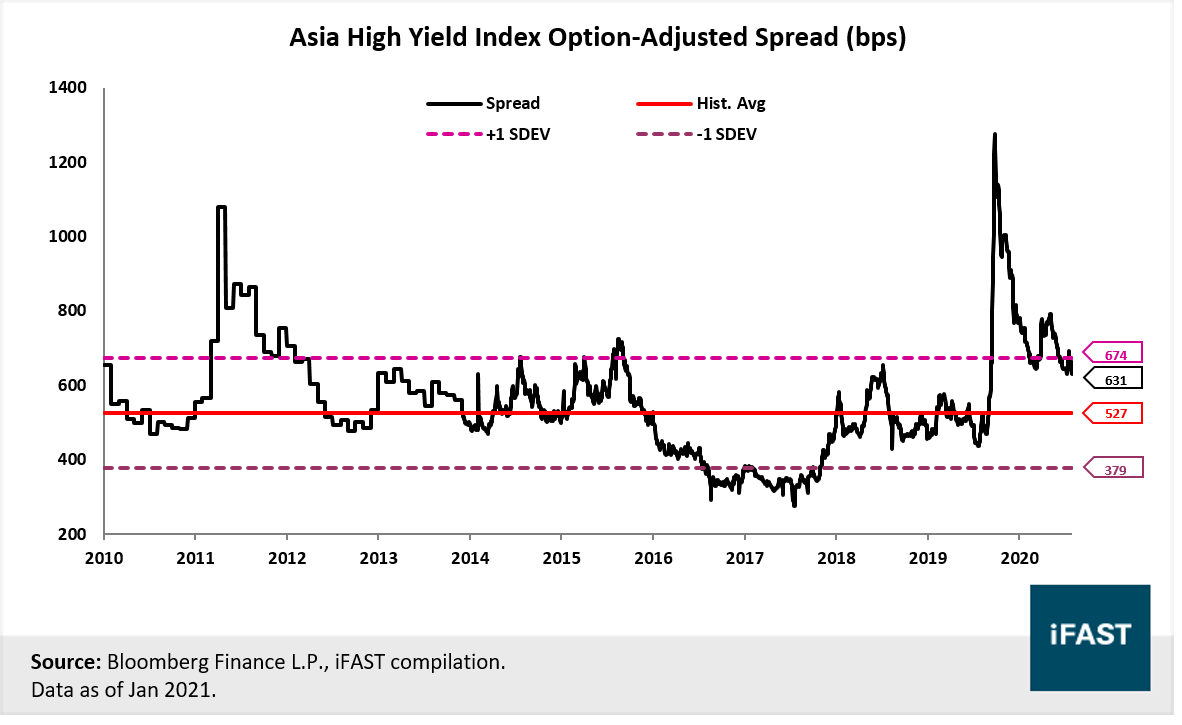
On an absolute level, spread (631 bps) for the asset class is still hovering close to one standard deviation above historical average (Z-score of 0.7) (chart 5). While on a relative level, Asia HY offers the highest spread amongst all segments, with the highest Z-score when compared.
Credit spread tightening is an integral driver of return for HY assets - the wider the spread, the higher the potential returns over time. We hold the view that Asia HY spread will reprice lower this year as credit risks subside. Our believe is predicated by i) our Asia macro and earnings outlook, ii) expectation of accommodative policy and iii) demand meeting debt issuance (issuers able to refinance) in 2021.
With where spread is at relative to history, we see ample room for tightening (higher potential return). In our view, there is a good possibility that spread return to pre-Covid level (430 bps) over time, which would entail a handsome tightening of 200bps.
Chart 4: Valuation for the fixed income space has turned expensive
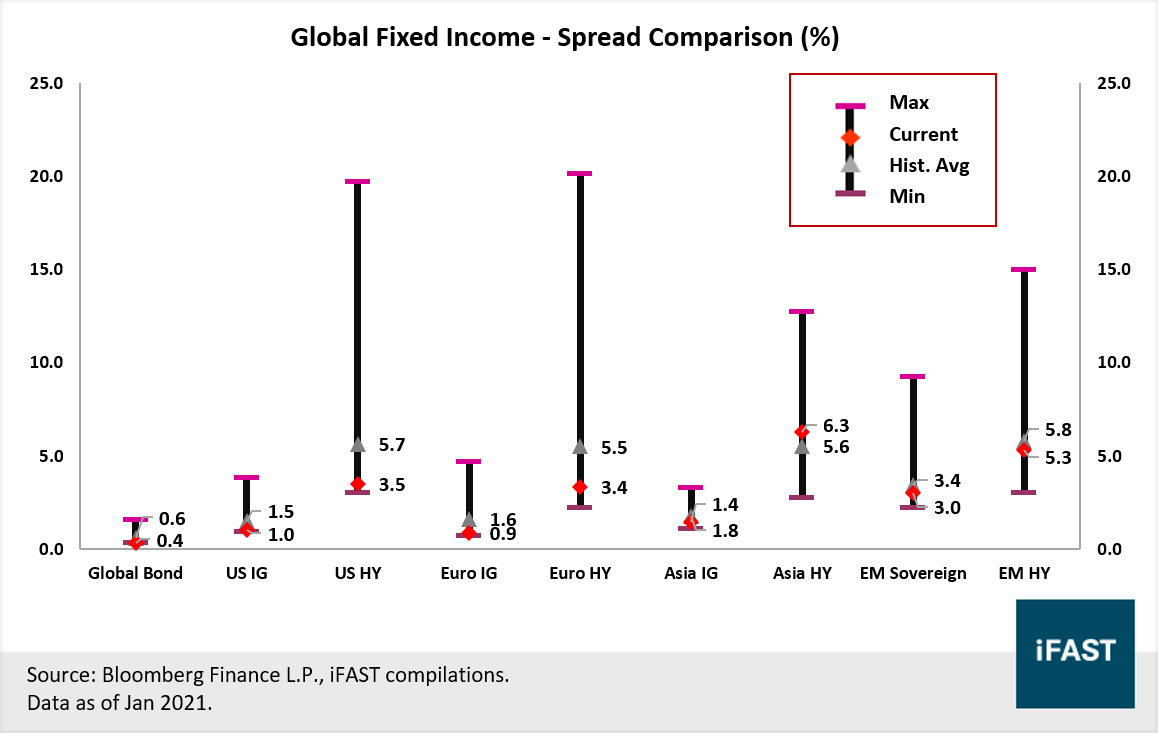
Chart 5: Asia HY spread near +1 Standard deviation from historical average (Z-score of 0.7)
Attractive subsequent return at current yield level
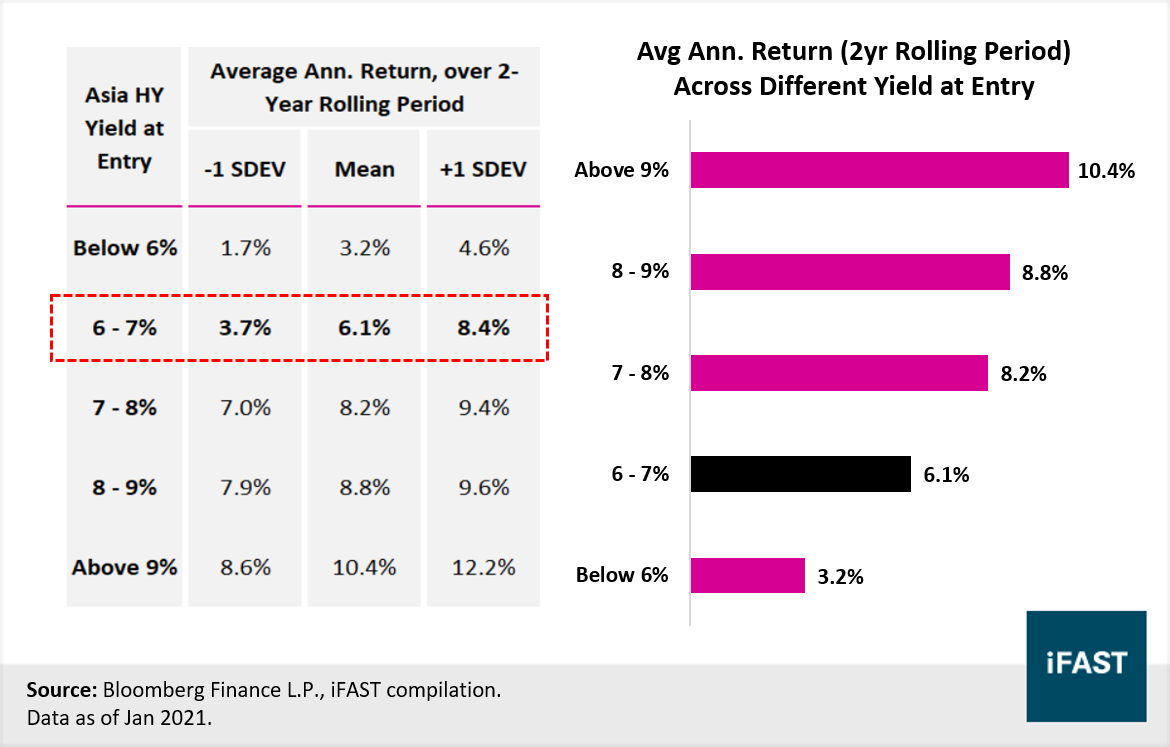
As outlined in the previous section, the wider the spread, the higher the potential returns over subsequent periods of time. History shows, entering Asia HY at yield level between 6 - 7% generated a return, on average, of 5.3% in the next 1 year or 6.1% annually on a rolling 2-year basis (chart 6 and 7). Such level of return stands attractive amongst fixed income peers and in particular, after considering Asia HY delivered a 6% total return (in USD terms) in 2020.
Chart 6: Average 1yr return at various yield at entry
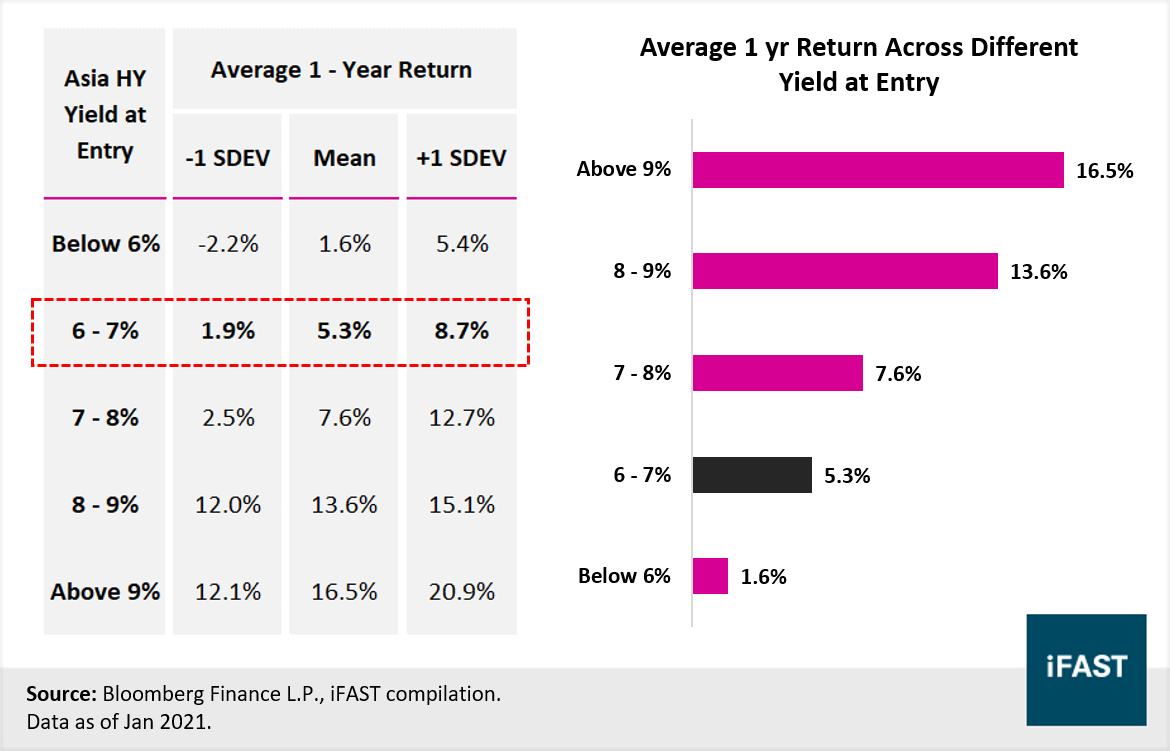
Chart 7: Average annualised return on a 2Yr rolling period at various yield at entry
Healthy fundamentals supported by Asia’s macro and earnings recovery
On a macro level, we expect Asia’s economic recovery, which accelerated in late - 3Q 2020, to hold steady in early 2021. The region’s growth remains well bolstered by robust exports growth as well as a confluence of positive cycle dynamic (tech and manufacturing upcycle). Based on our projections, growth in Asia ex Japan has recovered to pre-Covid levels (Real GDP growth 0.8% YoY in 2020) and should see above-trend healthy growth in 2021 (Est. 6.1% YoY).
The region should also see strong corporate earnings rebound 2021, underpinned by healthy macro recovery, supportive policy rhetoric and a relatively faster ‘normalisation’. Moreover, monetary policies across Asia should stay accommodative throughout 2021, perpetuating the low rates and easy refinancing, lending support to high yield issuers in managing maturities this year.
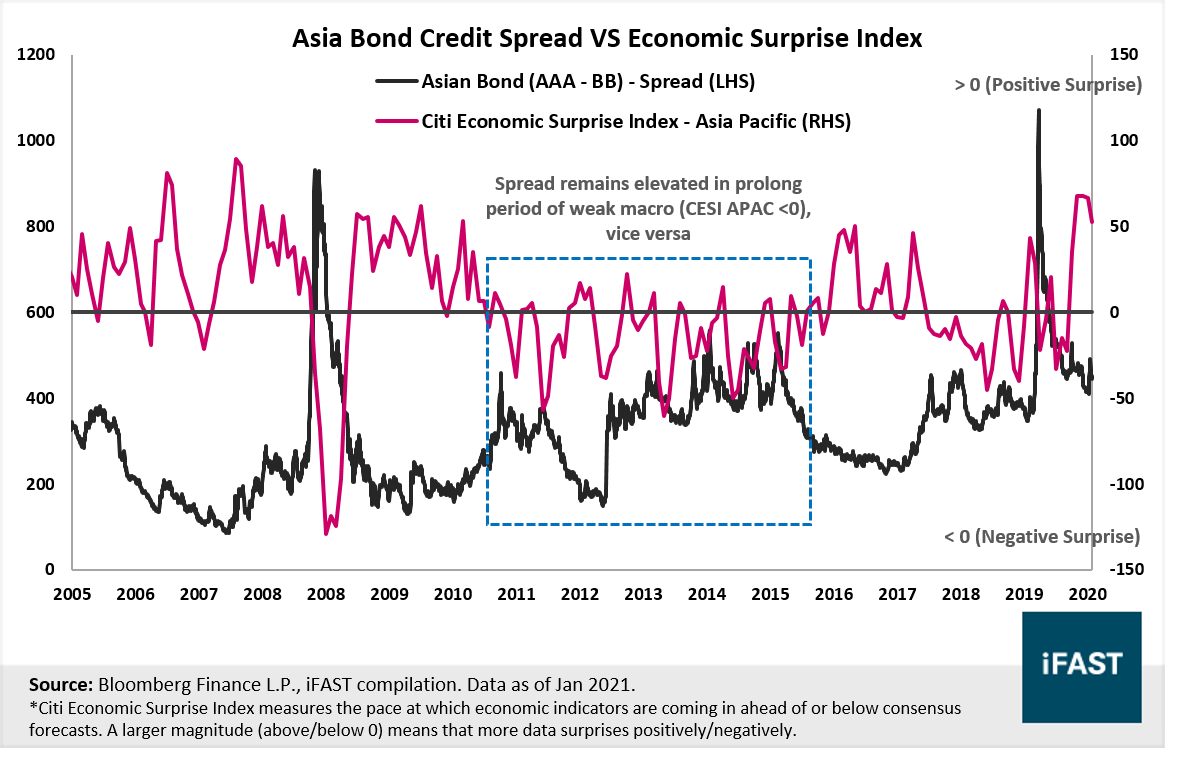
Given the region’s constructive macro, earnings and policy outlook in 2021, we expect lower stress and healthy fundamentals for issuers, alleviating credit risks in Asia HY moving forward.
Chart 8: During improving macro backdrop (CESI APAC >0 or in an uptrend) spread tends to compress and remain muted, vice versa
Manageable default risks, spreads adequately compensates for credit risk
As Covid-19 still has much of the world’s economy in a tight vicegrip, we believe it is prudent to continue monitoring default rates for riskier segments. Consensus expects a dip in Asia high yield default rate (chart 9) from about 3.5% in 2020 to 2-3% by end-2021 (in line with our expectation (2.5%) from reasons outlined in the section above). In the worst case scenario, which entails China’s onshore default panic spreading to its offshore bond market, we expect default rates to climb to 4% in 2021.
Comparing default rates across the various HY segments – US, EU and EM, Asia HY possess one of the lowest expected default rates alongside one of the highest recovery rate (average) of 40%. But what really enhanced Asia HY’s appeal is its risk premia, driven by the overpricing of default risk.
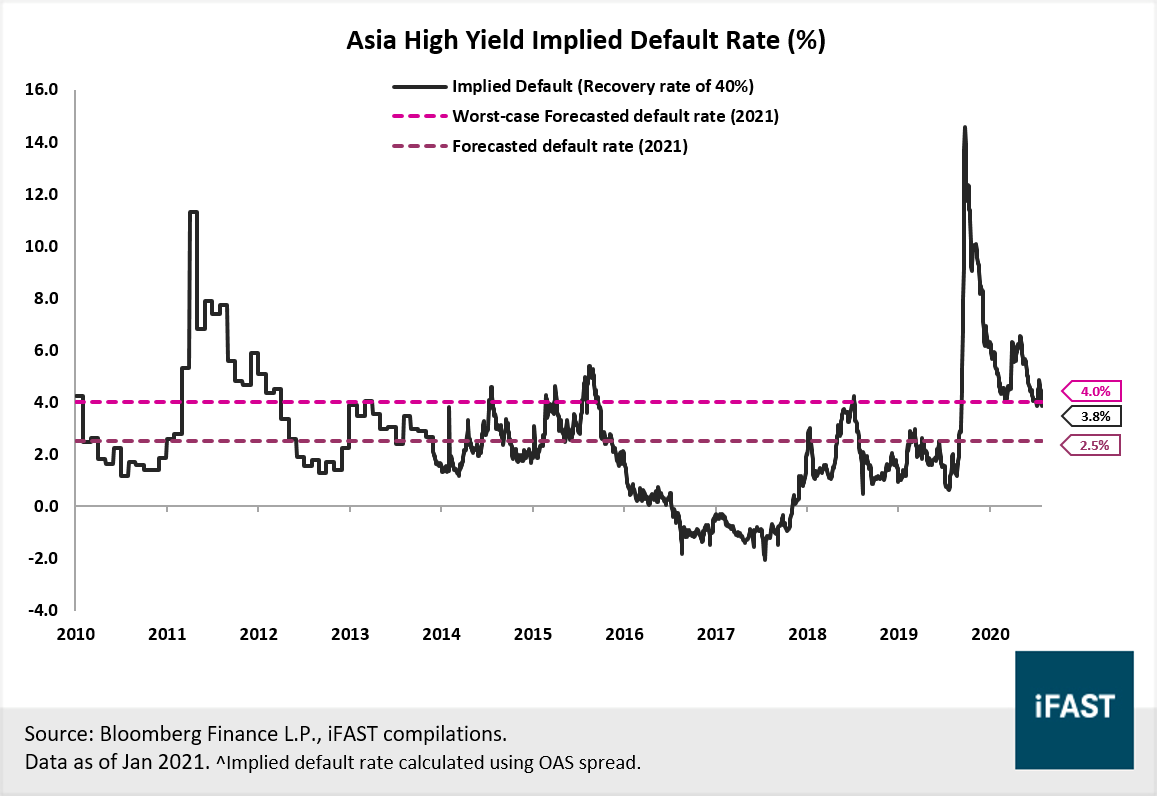
At current spread of 631 bps and a historical recovery rate of 40%, Asian high yield is pricing in around a default rate of 3.8% (chart 10). This appears excessive as compared to our expected 2021 default rate (2.5%). Over and above, current spread is almost pricing in a ‘worst-case scenario’ default rate (4.0%). In other words, investors entering/holding Asia HY currently will be well compensated via the risk premium (wide spread).
Chart 9: Default rate for Asia HY expected to fall to 2.5% in 2021
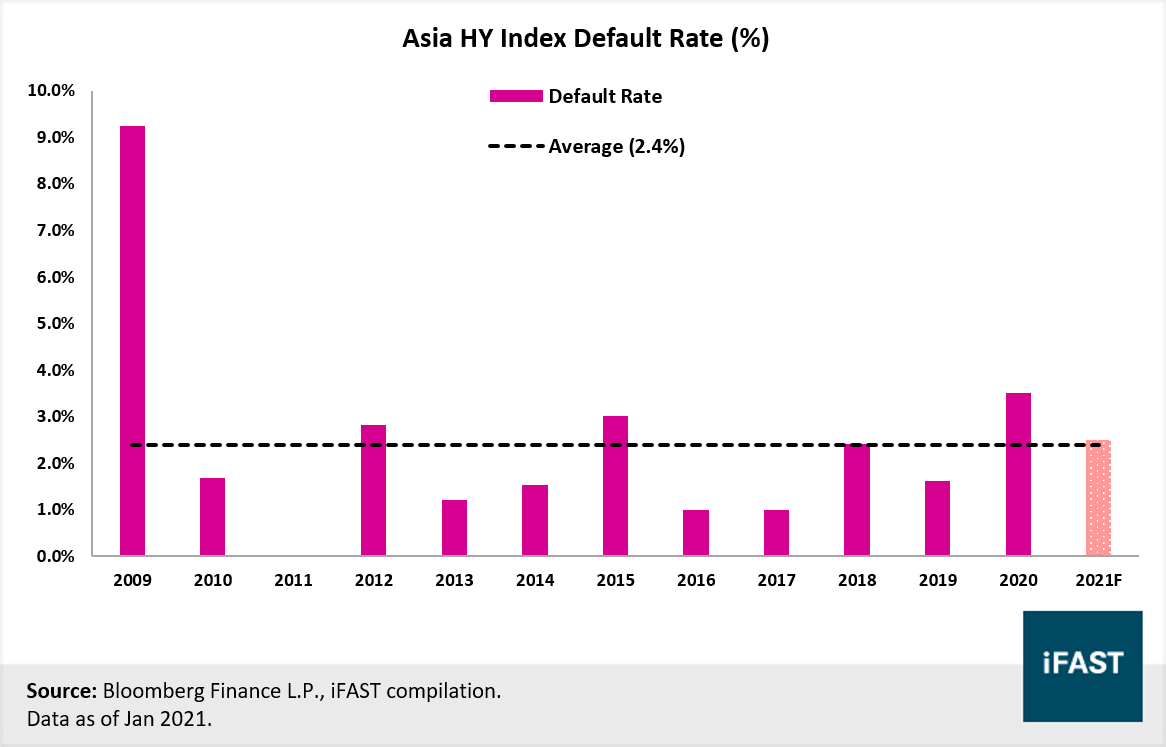
Chart 10: Spread implies a default rate higher than forecast, suggesting adequate compensation
Duration provides defense against interest rate risks
With the long end of the US treasury (UST) curve rising, managing interest rate risk through duration exposure should be of consideration in a fixed income selection strategy. Inflation expectation should continue to thread northwards for the year, bolstered by the macro backdrop, dollar weakness and upbeat commodity prices.
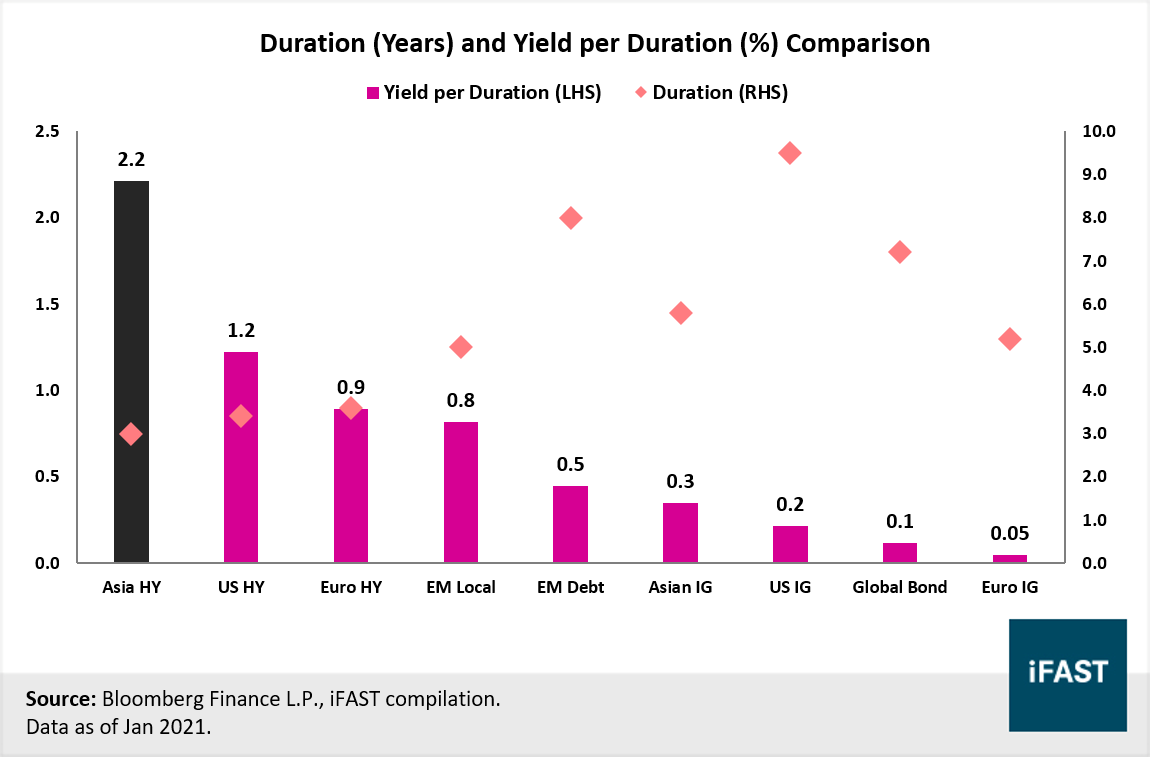
Asia high yield offers one of the lowest duration (around 2.7 – 3.0 years) within the fixed income space, and will be less affected by rising UST yields compared to other HY segments. Additionally, the combination of high yield and low duration, which Asia HY, is extremely favourable amid a rising yield backdrop.
The asset class possess one of the highest yield-to-duration ratio (chart 11) compared to peers – measurement of how much a rise in yield will overwhelm interest income. Should the long end of UST march higher in 2021, it will take a larger rise in yields (approximately 2.2%) to erode away Asia HY’s coupon return of 6.6%.
Chart 11: Asia HY possess the smallest duration and largest yield per duration (2.2%)
View on China and its real estate sector
China HY bonds (majority of which are property developers) dominates the Asian HY space, accounting for almost 50% of the universe. Given such substantial representation, the overall credit health of this credit segment are heavily influenced by conditions of the Chinese real estate sector.
As outlined in our outlook for China’s real estate sector (by our HK research team), fundamentals are looking healthy and housing prices should remain stable this year. We also expect sales growth to slow slightly but, given the lower base in 1H 20, annual sales growth should reach high single-digit to around 10% in 2021. While tighter regulations (such as the “Three Red Lines” policy) plague China’s developers, we believe the impact is likely limited as many mainstream developers are not severely affected.
From a macro level, money supply in China has recently turned lower, sparking some initial concerns for Chinese issuers as well. Nonetheless, we see low probability of any tightening in monetary policies over the next 2 quarters, in line with policymaker’s comments. The reasons are as such - i) demand-side is still playing catchup to supply-side’s recovery, ii) absence of material inflationary pressure and iii) global growth hitting a virus speed bump lately.
Riding on Asia high yield in 2021
Risk appetite has hit a bump as of late, troubled by a mixture of renewed virus fears, less-dovish monetary policies and speculative market behaviour. This may have halted HY’s recent performance, but we believe demand for risk assets will prevail in the end for reasons highlighted in our 2021 outlook.
That said, we expected more investors to eventually venture lower down the credit spectrum, undertaking more risks. Therefore, greater emphasis should be on a risk-reward assessment for HY credit, which Asia HY should come out on top in our view.
From a reward perspective, Asia HY offers the combination of attractive yield pickup, value capture and spread compression while backed by healthy fundamentals. From a risk perspective, we find interest rate and default risk to be mild and manageable, and risk premia to be attractive All things considered, Asia HY is our top fixed income pick for 2021 and current yield/ spread presents good entry opportunity.
Recommended bonds
|
High Yield Bonds |
|









