Azalea Asset Management (“Azalea”), the sponsor of the popular Astrea Private Equity (“PE”) bonds, hosted their annual Astrea Investors Day on 24 Feb 26. Here is a summary on the points mentioned during the presentation.
On 24 February 2026, Azalea Asset Management, the sponsor of the popular Astrea Private Equity (“PE”) bonds, hosted its annual Astrea Investors Day. The session offered investors a closer look beneath the surface of the Astrea structure and the evolution of its private equity portfolios. What follows is a distilled account of the key themes from the presentation.
About Astrea Private Equity Bonds
For investors new to the platform, Azalea Asset Management is a wholly owned subsidiary of Seviora Holdings and indirectly owned by Temasek Holdings. The firm focuses on investing in private equity funds while developing products that broaden access to the asset class.
The Astrea series is one such innovation. These bonds are asset-backed securities supported by cash flows generated from an underlying portfolio of private equity investment portfolio. Each Astrea series holds a diversified portfolio of PE funds managed by established general partners, with exposure to numerous portfolio companies beneath them.
Cash flows are typically realised when these portfolio companies exit or are sold, with proceeds flowing back through the structure to fund coupon payments and principal redemption. Over time, Azalea has become a regular issuer in Singapore’s retail bond market, with Astrea 9 Private Equity Bonds marking its sixth listed retail bond in Singapore.
Check here to find out more about Astrea 9 bonds.
Astrea Portfolio Performance
Since 2023, the private equity exit landscape has begun to thaw. Both exit volumes and transaction values have trended higher, signalling a gradual reopening of the realisation window for sponsors. While activity remains below the frenetic pace of 2021, the recovery is gaining traction—helped by stabilising interest rates, better price discovery, and firmer public equity markets. A healthier exit environment ultimately translates into stronger portfolio distributions, smoother rebalancing, and capital recycling across the private equity ecosystem. Against this improving backdrop, the credit profile of the Astrea bond platform has correspondingly strengthened.
Within the Astrea family, the earlier vintages—Astrea III through V—have already completed their lifecycle and been fully redeemed. The remaining live structures span Astrea VI Private Equity Bonds through Astrea 9 Private Equity Bonds
Astrea VI
- Class A tranche was fully reserved by March 2025 and remains on track for full redemption in March 2026—five years from issuance. The principal for Class B bonds will begin to be amortized in the same distribution period.
- Credit metrics have also improved. In November 2025, Fitch Ratings upgraded the Class B bonds from ‘A’ to ‘A+’. Currently, the Class A-1 bonds carry a ‘AA-’ rating, while the Class A-2 and Class B tranches are rated A+.
- Astrea VI has announced the scheduled redemption of all Class A-1 bonds on 18 March 2026. Bondholders will receive full principal repayment together with unpaid accrued interest, alongside a 0.5% redemption premium on the principal—an added sweetener tied to the scheduled redemption. We believe Class B bonds are likely to be redeemed as the available surplus cash will flow unimpeded to amortize the Class B bonds once Class A bonds are fully retired.
Astrea 7
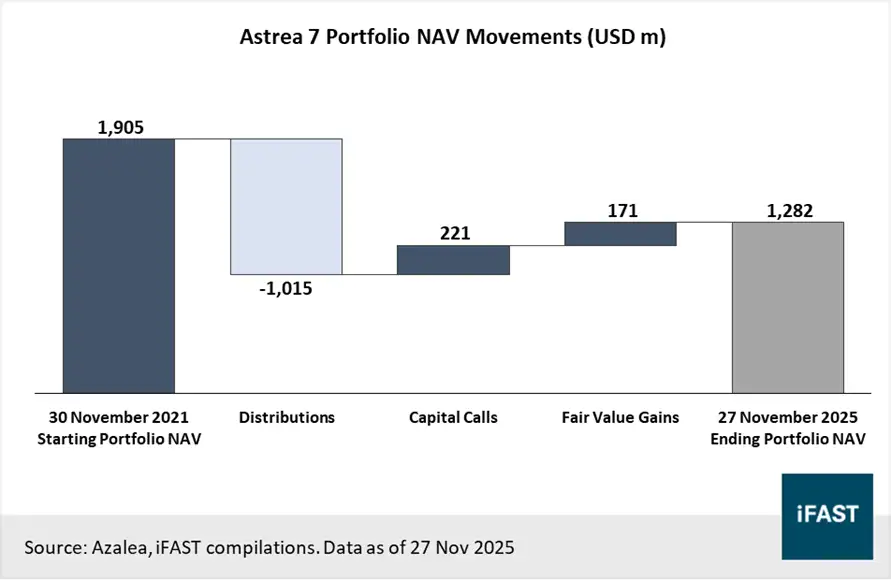
Chart 1: Astrea 7 Portfolio NAV Movements (USD m)
- As of the most recent distribution date, reserve levels have reached roughly 75% of the outstanding Class A bond size. The structure’s loan-to-value (LTV) ratio stands at 27.3%, comfortably below the 50% maximum, reflecting both portfolio value growth and steady cash inflows.
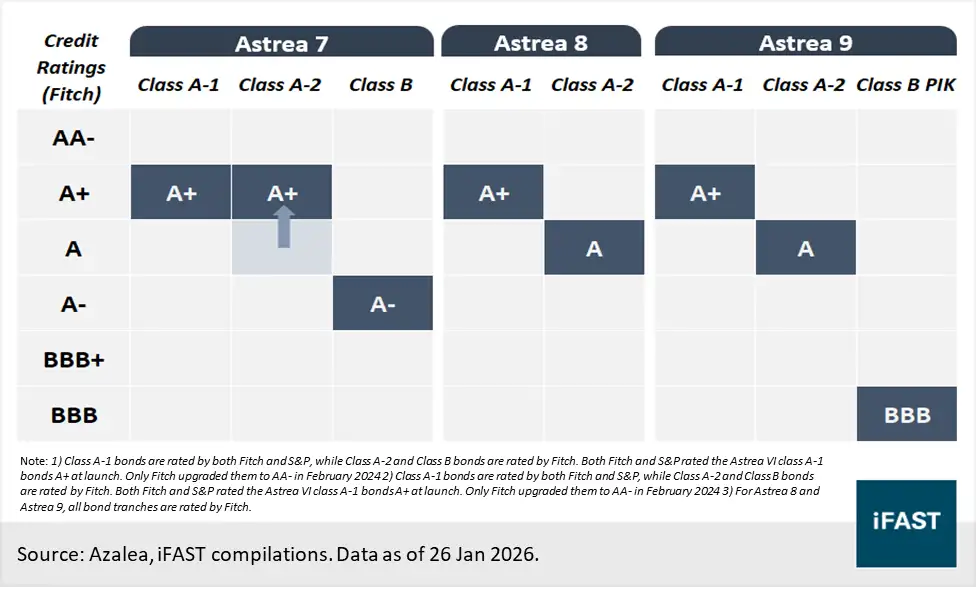
- Credit quality has correspondingly improved. In November 2025, Fitch Ratings upgraded the Class A-2 tranche from ‘A’ to ‘A+’, citing the stronger LTV profile. Currently, both Class A-1 and Class A-2 bonds are rated ‘A+’, while the Class B tranche carries an ‘A-’ rating.
- To date, Astrea VII has generated over US$1 billion in cash distributions, equivalent to roughly 53% of the portfolio’s starting net asset value, underscoring the steady monetisation of underlying private equity investments.
Astrea 8
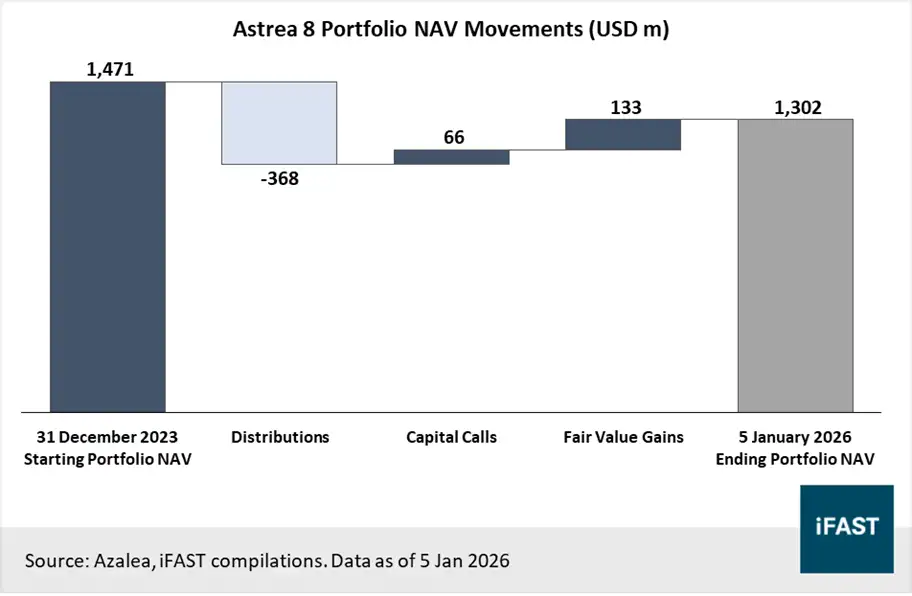
Chart 2: Astrea 8 Portfolio NAV Movements (USD m)
- As of the latest distribution date, reserves stand at roughly 40% of the Class A-1 bond size. The loan-to-value (LTV) ratio for the Class A bonds is 34.5%, well below the 40% maximum. In terms of credit ratings, the Class A-1 bonds are rated A+, while the Class A-2 tranche carries an A rating, according to Fitch Ratings.
- To date, the Astrea VIII portfolio has generated more than US$360 million in distributions, representing approximately 25% of its starting net asset value—sufficient to meet all bond obligations thus far while gradually building its reserve.
Astrea 9
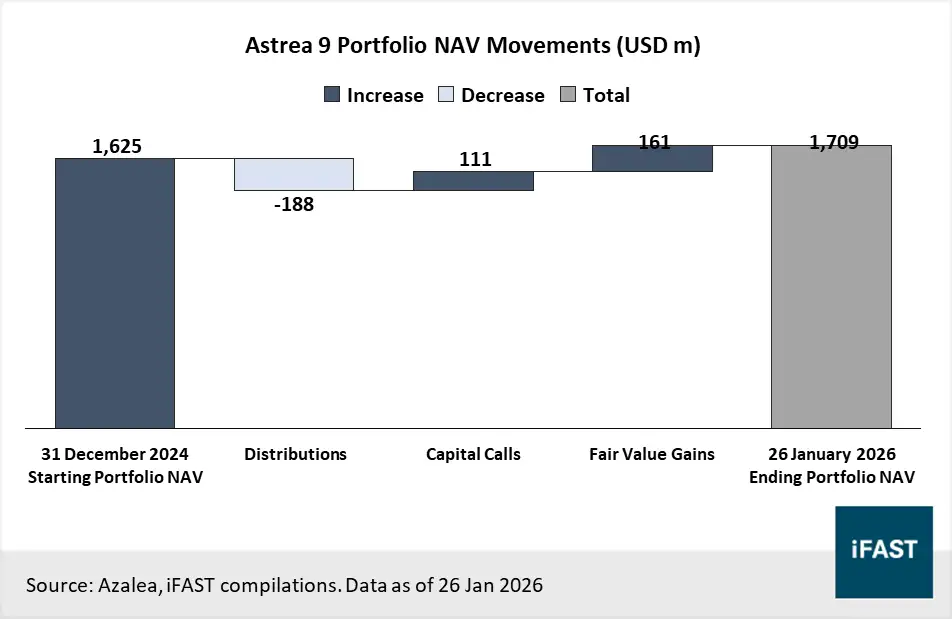
Chart 3: Astrea 9 Portfolio NAV Movements (USD m)
- As the newest vintage in the platform, Astrea 9 PE Bonds is still in the early innings of its distribution cycle. As of the most recent distribution date, reserves stand at roughly 11% of the Class A-1 bond size. The loan-to-value (LTV) ratio for the Class A bonds is 38.4%, comfortably below the 50% maximum.
- In terms of ratings, Class A-1 bonds are rated A+, Class A-2 bonds carry an A rating, while the Class B PIK tranche is rated BBB, according to Fitch Ratings.
- Astrea 9 recorded its first distribution in February 2026. Since inception, the portfolio has generated approximately US$188 million in distributions, equivalent to around 12% of the starting net asset value—sufficient to meet all bond obligations to date.
Chart 4: Credit rating across all Astrea Portfolios
Recommendations
Table 1: Astrea SGD and USD Bonds
|
Issue |
Astrea Series |
Ask Price |
Yield to Call/ Maturity |
Years to Call/ Maturity |
|
SGD |
||||
|
Astrea 7 |
101.85 |
2.56%/ 4.54% |
1.3 / 6.3 |
|
|
Astrea 8 |
104.75 |
2.87%/ 4.56% |
3.4 / 13.4 |
|
|
Astrea 9 |
101.90 |
2.94%/ 3.86% |
4.4/14.4 |
|
|
USD |
||||
|
ASTLC 5.350% 27May2032 Corp (USD) - Class A-2 Classified as SIP |
Astrea 7 |
100.50 |
4.91%/ 5.99% |
1.2/ 6.2 |
|
Astrea 8 |
104.35 |
5.22%/ 6.43% |
4.4/ 13.4 |
|
|
Astrea 9 |
102.20 |
5.14%/ 6.06% |
4.4/ 14.4 |
|
|
ASTLC 4.350% 18Mar2031 Corp (USD) - Class B Classified as SIP |
Astrea VI |
99.80 |
-/ 4.40% |
-/ 5.0 |
|
Astrea 7 |
100.45 |
5.78%/ 6.48% |
2.2/ 6.2 |
|
|
ASTLC 7.350% 08Aug2040 Corp (USD) - Class B PIK Classified as SIP |
Astrea 9 |
101.90 |
-/ 6.99% |
-/ 14.4 |
|
Sources:
Bondsupermart, iFAST Compilations. Data as of 9 Mar 2026. |
||||
SGD bonds
- Class A-1 bonds remain appealing for retail investors. They trade favourably relative to the broader SGD credit universe, offer a solid yield pickup over comparable-tenor Singapore Government Securities, and carry no currency risk for local investors, while maintaining an A+ rating from Fitch Ratings.
- To lock in yields over the medium-term, ASTLC 4.350% 19Jul2039 Corp (SGD) - Class A-1 Retail (Astrea 8) and ASTLC 3.400% 08Aug2040 Corp (SGD) - Class A-1 Retail (Astrea 9) offer yield-to-call of roughly 2.8%–3.0%, placing them at the upper end of SGD corporate bonds with 3–4 year tenors, where yields typically range from the high-1% to around 3.0%
- For shorter duration exposure, ASTLC 4.125% 27May2032 Corp (SGD) - Class A-1 Retail (Astrea 7) stands out as a good alternative, particularly to fixed deposits. Astrea 7 Class A-1 bonds are well on schedule to and likely to be redeemed on the mandatory call date.
USD bonds
- Class A-2 tranches remain attractive as yield enhancers for conservative portfolios, offering diversification away from traditional corporate issuers while holding an ‘A’ rating from Fitch Ratings.
- To lock in yields over the medium-term, ASTLC 6.350% 19Jul2039 Corp (USD) - Class A-2 Retail (Astrea 8) and ASTLC 5.700% 08Aug2040 Corp (USD) - Class A-2 Retail (Astrea 9) currently offer yield-to-call around 5.1%–5.2%, a pickup over the approximately 4.4% yield for ‘A’ rated USD corporates with similar tenors.
- For shorter duration exposure, ASTLC 5.350% 27May2032 Corp (USD) - Class A-2 Classified as SIP (Astrea 7) offers a near 5% yield, making it an attractive short-term option like its SGD Class A-1 counterpart.
- Among institutional Class B USD tranches, we like ASTLC 6.000% 27May2032 Corp (USD) - Class B Retail (Astrea 7) stands out with a notable 5.8% yield, supported by the fact that its Class A bonds remain on track for redemption at the mandatory call date.