


Key Highlights
- OPR maintained at 2.75%: BNM kept the OPR unchanged, noting that the current monetary policy stance remains consistent to support sustainable growth while maintaining price stability.
- Growth remains resilient: Malaysia's economy grew 5.7% in 1H26, driven by stronger exports and sustained domestic demand, with full-year growth expected at around 5%.
- Strong domestic and external drivers: E&E exports, technology-related demand, tourism and ongoing investment are expected to support growth, although external uncertainties remain.
- Inflation remains contained: Headline and core inflation averaged 1.8% and 2.0%, respectively, in the first seven months of 2026, providing room for BNM to maintain its current policy stance.
- Investment view: We continue to favour the 3–5-year segment of the MGS curve. Our base case remains no rate change in 2026.
The Monetary Policy Committee (MPC) of Bank Negara Malaysia kept the Overnight Policy Rate (OPR) unchanged at 2.75% in September 2026, in line with our expectations highlighted in previous articles: Malaysia Bond Market Outlook 2H26: Between a Barrel and a Ballot Box | Bondsupermart
BNM Maintains OPR at 2.75% Amid Resilient Growth and Contained Inflation
According to the Monetary Policy Committee (MPC), Malaysia's economy continued to expand robustly, with GDP growth reaching 5.7% in the first half of 2026, supported by stronger-than-expected exports and sustained domestic demand. Growth is expected to reach around 5% for the full year and remain resilient in 2027, supported by robust demand for electrical and electronics (E&E) goods, continued strength in technology-related exports, tourism activity, stable labour market conditions and ongoing investment.
However, the growth outlook remains subject to external uncertainties, particularly a prolonged conflict in the Middle East and lower commodity production. Meanwhile, stronger-than-expected global growth and technology-related export demand could provide further upside to growth.
On the inflation front, headline and core inflation averaged 1.8% and 2.0%, respectively, in the first seven months of 2026. Despite elevated costs and strong economic growth, the pass-through to consumer prices has remained contained, supported by domestic policy measures and stable demand conditions. Nevertheless, elevated global commodity prices and uncertainties surrounding the Middle East conflict could continue to exert upward pressure on cost conditions.
We believe that the contained inflation environment and resilient economic growth provide BNM with room to maintain the OPR at 2.75% for the remainder of 2026. The MPC's latest statement also indicates that the current monetary policy stance remains consistent to support sustainable economic growth while maintaining price stability.
Market Reaction to BNM’s OPR Decision
Following Bank Negara Malaysia's (BNM) announcement at 3:00 p.m. to maintain the Overnight Policy Rate (OPR) at 2.75%, financial markets remained broadly stable.
Thirty minutes after the announcement, the FBM KLCI showed little movement, edging up slightly from 1,771.09 at 3:00 p.m. to 1,771.90 at 3:30 p.m. (Chart 1) Meanwhile, the MGS market was largely unchanged, with the 3-year MGS yield declining marginally by 1 basis point, while yields across other tenors remained stable (Table 1). On the currency front, the US dollar also remained broadly stable against the Malaysian ringgit at around 4.045.
Overall, the muted reaction across the equity, bond and currency markets indicates that BNM's decision to maintain the OPR at 2.75% was broadly anticipated by market.
Chart 1: FBMKLCI’s intraday performance
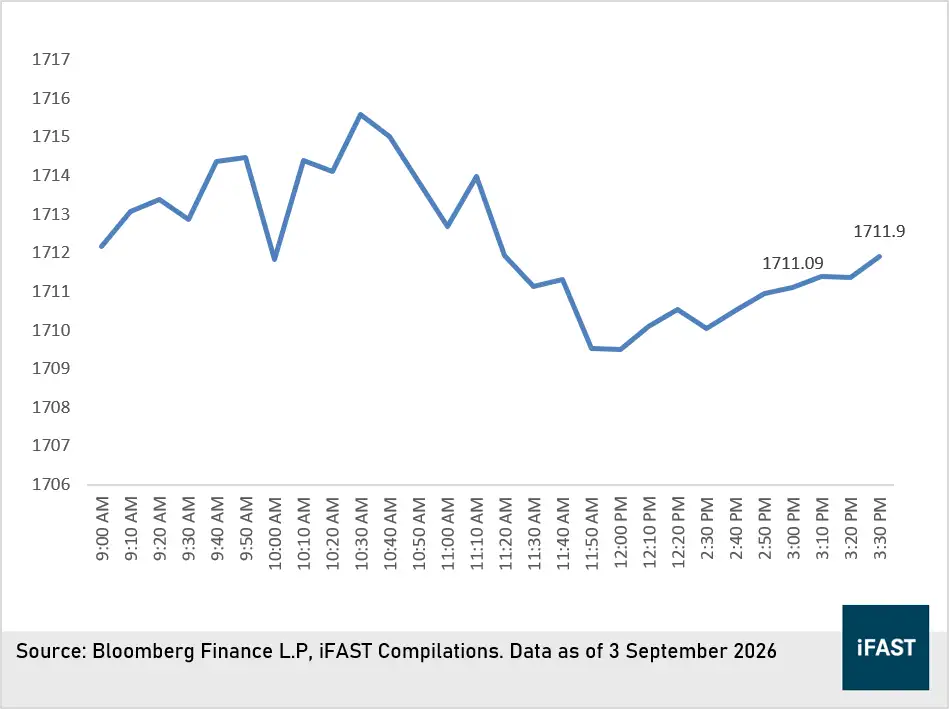
Table 1: Malaysia Government Securities (MGS)
|
Tenure |
Trading Yield (%) |
Change (bps)* |
|
3-year |
3.37% |
-1 |
|
5-year |
3.63% |
- |
|
7-year |
3.86% |
- |
|
10-year |
3.91% |
- |
|
15-year |
4.07% |
- |
|
20-year |
4.22% |
- |
|
30-year |
4.29% |
- |
|
*Changes in MGS yields 30 minutes after the MPC announcement. Source: Bloomberg Finance L.P, iFAST Compilations. Data as of 3 September 2026 |
||
MGS Yield Curve Remains Upward Sloping; Medium-Term (3–5 Years) Favoured
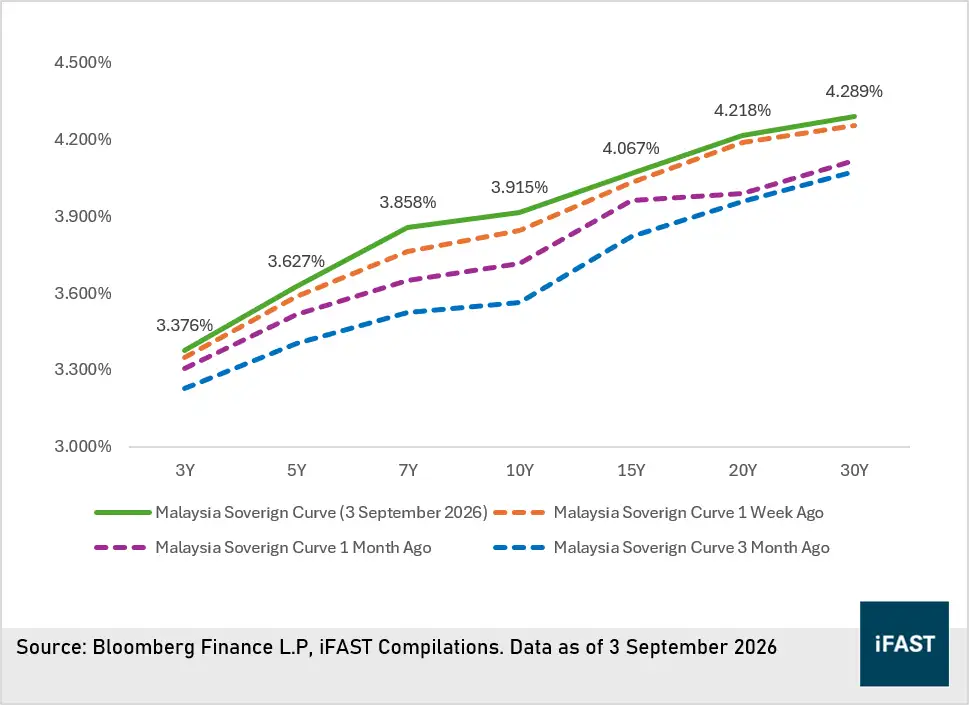
The Malaysian Government Securities (MGS) yield curve remains upward sloping. Compared to one week, one month and three months ago, yields have generally risen across all tenors, although the movement over the past week has been relatively muted. In contrast, the largest increase was observed over the past month, mainly driven by higher U.S. Treasury yields and increased uncertainty surrounding the domestic political landscape.
Looking ahead, we expect MGS yields to remain slightly elevated in 2H26. Against this backdrop, we prefer the short-to-medium segment of the curve of 3–5-year tenor. This segment offers an attractive balance between yield and interest-rate risk, allowing investors to capture reasonable carry while maintaining lower duration risk compared with longer-dated bonds.
Chart 2: Yield Curve and Credit Spread
Overall, we expect the OPR to remain at 2.75% for the remainder of 2026, supported by resilient economic growth and contained inflation. With the next and final MPC meeting of 2026 scheduled for 5 November (Table 2), we maintain our view that BNM is likely to keep the OPR unchanged. However, MGS yields may remain slightly elevated amid global yield and geopolitical uncertainties. We therefore continue to favour the 3–5-year segment, which offers a balance between attractive carry and lower duration risk compared with longer-dated bonds.
Table 2: Monetary Policy Committee Meeting Decision Schedule
|
MPC Meeting No |
Date |
|
1st |
22 January 2026 (Thursday) |
|
2nd |
5 March 2026 (Thursday) |
|
3rd |
7 May 2026 (Thursday) |
|
5th |
3 September 2026 (Thursday) |
|
6th |
5 November 2026 (Thursday) |
|
Source: Bank Negara Malaysia (BNM), iFAST Compilations. Data as of 3 September 2026 |
|
Bond Recommendation
Please find the compiled list within our prefer duration of 3 – 5 years offering the yield in the range of 4.6% to 6.1% (Table 2).
Table 3: Available bond in our platform within (3-5 year)
|
Issuer |
Bond |
Year to call/maturity |
Yield to call/ maturity |
Min and Sub investment amount |
|
Kenanga Investment Bank Berhad |
KNKIB 6.100% Perpetual Corp (MYR)* |
5Y/- |
6.1%/- |
RM25,000/5,000 |
|
WCT Holdings Berhad |
-/3Y |
-/5.2% |
RM5,000/5,000 |
|
|
YINSON HOLDINGS BERHAD |
-/4Y3M |
-/4.6%/- |
RM250,000/250,000 |
|
|
*Not yet issue Source: FSMONE, iFAST Compilations. Data as of 3 September 2026 |
||||










