Important Events
· Last week, the European Central Bank (“ECB”) kept interest rates on the main refinancing operations, marginal lending facility and deposit facility constant at 0.00%, 0.25% and -0.50% respectively. The central bank informed that it will also continue its EUR 1.85 trillion pandemic emergency purchase programme (“PEPP”) until at least the end of March 2022, or until the perceived end of the coronavirus crisis. Asset purchases will also continue at a significantly higher pace than the early months of this year.
The bank also raised the outlook for 2021 and 2022, forecasting that euro area activity will return to growth in 2Q21 and to pick up strongly in 2H20, driven by an easing of supply bottlenecks and a sharp rebound in private consumption. This translates to real GDP possibly exceeding its pre-crisis level from 1Q22 onwards, one quarter earlier than previously projected.
Interest Rates and Currencies
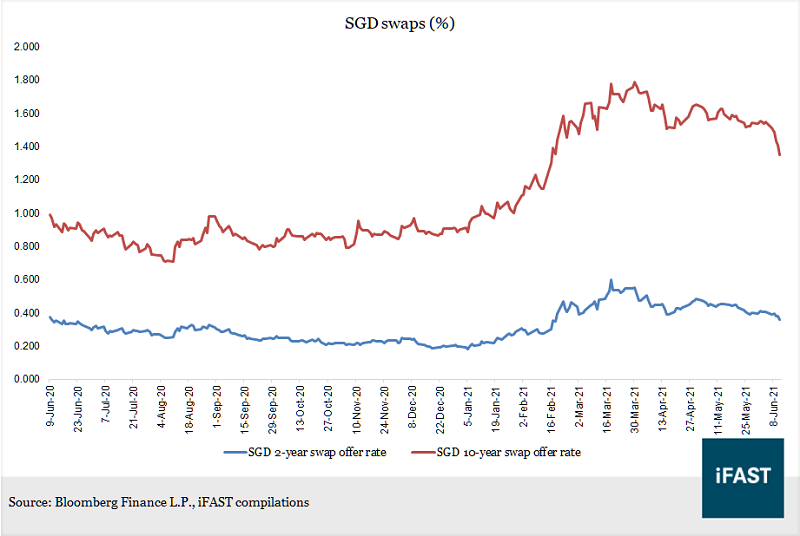
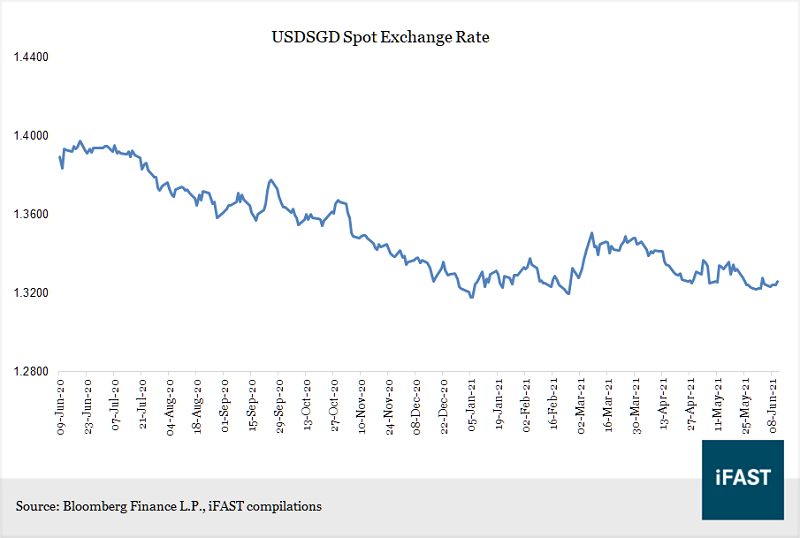
· The US dollar appreciated slightly against the SGD, gaining only 0.1% by the end of last week. The two-year SGD Swap Offer Rate (“SOR”) decreased by 4.8 basis points (“bps”) to 0.3575% while the ten-year SOR declined by 20bps to 1.3500%, coinciding with the drop in US Treasury yields.
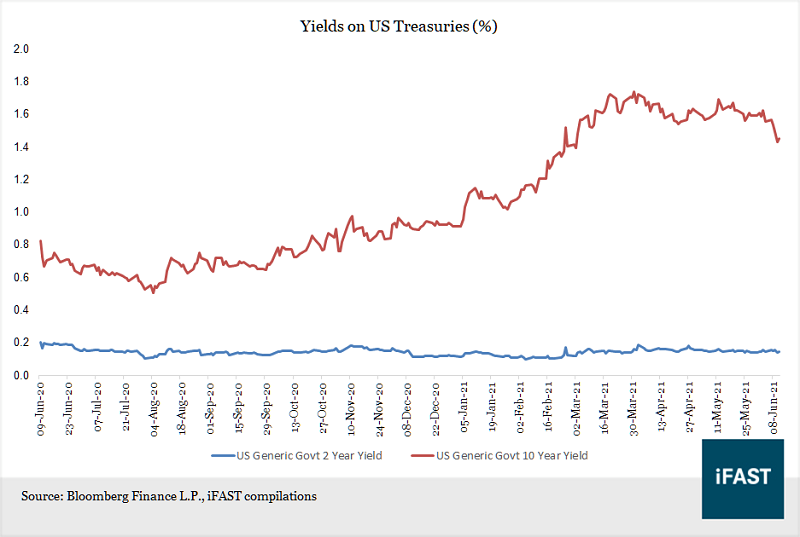
· The yield of 2-year US Treasuries (“UST”) increased by 0.2bps to 0.1469% while the 10-year UST yield decreased by a whopping 10.2bps to 1.4518% as investors adjusted their long-term inflation and growth expectations. US CPI increased by 0.6% MoM in May, but was mainly driven by prices of rental cars, lodging and airfares. Investors may be turning towards the notion of transitory inflation.
Asian High Yield Bond Index
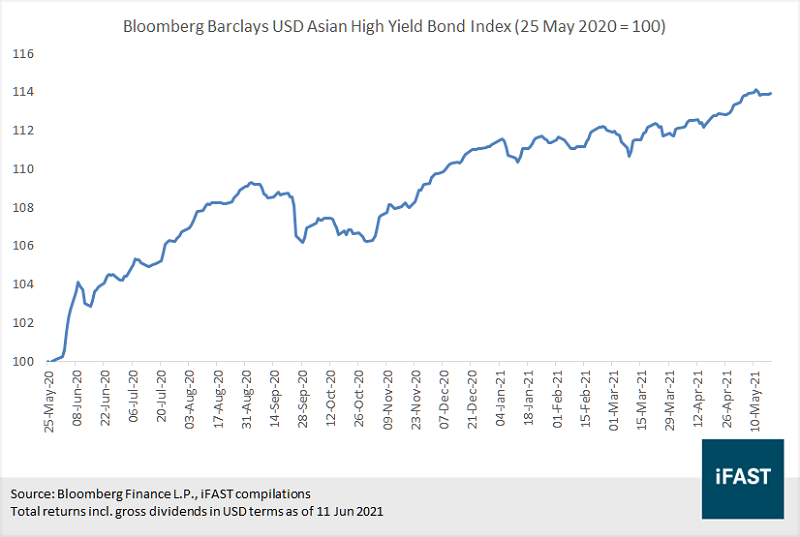
· The Barclays USD Asia High Yield Bond Index declined by 0.27% for the week ended 11 Jun 2021.
·
Evergrande
bonds continue to see large declines, along with Hengda Real Estate bonds, the
keepwell provider for bonds issued by Scenery Journey Ltd., an offshore unit of
Evergrande. China Chengxin International Credit Rating Co., China’s largest
credit risk assessor, put the bonds of the above-mentioned issuers on their
watchlist, causing disturbances in their prices. Bond prices of other Chinese
real estate issuers also declined.
(Read more: China Evergrande is surrounded by rumours again. What is happening this time?)
· Other emerging market bonds, for example Indian and Sri Lankan bonds, saw better performances compared to their Chinese counterparts. Delhi International Airport bonds saw weekly increases of 2% while Pakistan and Sri Lankan sovereign bonds also gained slightly.
Corporate Updates and New Issues
· On Monday, Lendlease Global Commercial Trust Management Pte. Ltd. proposed to acquire 53.0% of the shares in Lendlease Jem Partners Fund Limited (“LLJP”) and between 5.0% and 19.8% of the shares in Lendlease Asian Retail Investment Fund 3 Limited (“ARIF3”) at a purchase consideration of SGD 204.1m to SGD 337.3m. LLJP and ARIF3 hold a respective 25.0% and a 75.0% indirect interest in the shopping mall known as Jem at 50 Jurong Gateway Road.
The acquisition is expected to complete by 30 Sep 2021, thereafter LREIT will hold a 53.0% interest in LLJP, a 10.0% to 24.8% interest in ARIF3, and an effective 20.8% to 31.8% indirect interest in Jem.
Pro-forma net property income based on 1HFY21 numbers (i.e. the six month period ended 31 Dec 2020) will remain the same before and after the acquisition at SGD 30.4m. The profit before tax and change in fair value will increase from SGD 5.3m to 10.1m. Pro-forma total borrowings based on unaudited 1HFY21 results will increase from SGD 545.8m to SGD 687.1m due to the acquisition of the ARIF3 Share Capital. In contrast, the gearing ratio will drop from 35.5% to 34.1%.
· Suntec Real Estate Investment Trust (“REIT”) proposed on Monday to issue the SUNSP 4.250% Perpetual Corp (SGD) at the initial price guidance of 4.45%. The perpetual securities are callable on 15 Jun 2026. Net proceeds will be used by Suntec REIT to refinance its existing borrowings, financing its acquisitions and any asset enhancement works, and general corporate purposes.
(Read more: Suntec REIT launches new SGD NC5 perps at 4.45% IPG)
·
On
Monday, KrisEnergy Ltd announced that DBS has cancelled total commitments under
its revolving credit facility and declared that all loans are now payable on
demand. Madison Pacific Trust Limited also called for an event of default under
the credit facility agreement between KrisEnergy (Cambodia), KrisEnergy
(Apsara) Company Ltd, Kepinvest Singapore Pte. Ltd and Madison Pacific.
Madison Pacific Trust will also be appointing receivers over the security interest granted to it under the share pledge and asset pledge agreements entered into under the Cambodia loan facility. Borrelli Walsh Pte Limited have been appointed as joint and several receivers over the assets. Also, the hearing for the winding up petition has been set at 9am (Cayman Time) on 12 Jul 2021.
· Keppel Infrastructure Trust (“KIT”) informed on Thursday that Basslink Pty Ltd has advised KIT of the legal costs in relation to the 3 arbitrations between – the State of Tasmania and Basslink, Basslink and Hydro Tasmania, and Hydro Tasmania and Basslink.
Basslink is required to pay the State of Tasmania AUD 7.2m and interest of approximately AUD 1.04m for the State Arbitration. As for the Basslink and Hydro Tasmania arbitrations, Basslink will pay Hydro Tasmania a total of AUD $26.0m.
Further to the SGD 76.2m (~AUD 80.5m) arbitration provisions made by KIT Group for the year ended 31 Dec 2020, an additional provision of SGD 23.8m (~AUD 23.1m) will be made following the conclusion of the cost award. However, this update is not expected to have any financial impact on the distribution per unit of KIT for the financial year ending 31 Dec 2021 as KIT does not rely on Basslink for distribution cash flows.
Additionally, KIT also announced that Mr Jopy Chiang will be appointed the new Chief Executive Officer of Keppel Infrastructure Fund Management Pte. Ltd. (“KIFM”) as of 1 Aug 2021. Mr Matthew Pollard will step down as CEO on 31 Jul 2021 to become an adviser to KIFM.
· As of Wednesday, Fraser and Neave, Limited (“F&N”) proposed to issue SGD 100m in aggregate principal amount of the FNNSP 2.000% 16Jun2026 Corp (SGD) pursuant to its SGD 2b multicurrency debt issuance programme. The notes are expected to be issued on 16 Jun 2021 and shall mature on 16 Jun 2026.
· On Wednesday, Chip Eng Seng Corporation Ltd. (“CES”) announced that its subsidiary CES Grosvenor (SA) Pty Ltd has entered into a contract to acquire the commercial property located at 80-82 Hindley Street in Adelaide, Australia. The purchase price for the Property is AUD 2.5m.
A deposit of AUD 0.25m was paid to the vendors’ conveyancers on 9 Jun 2021. Completion will take place on 1 Jul 2021 or any other agreed date. The acquisition will be funded from CES’ internal resources and is not expected to have significant impact on the net tangible assets and earnings per share of CES for the current financial year ending 31 Dec 2021.
· On Wednesday, Hatten Land Limited announced an extension for the repayment of the USD 25m guaranteed secured bonds to 8 Jul 2021. The bonds shall be extended on a monthly basis from 9 Jun 2021 to 8 Sep 2021. During the extension period, the company is required to seek the no-objection from the bondholders for the extension on a monthly basis, failing which the bonds shall mature on the last extended maturity date.
· Hyflux Ltd. announced on Thursday that a virtual townhall meeting will be held on 18 Jun 2021, 1pm (SGT). The meeting seeks to provide bondholders with an update in respect of the judicial management and the winding up application. Bondholders who are interested in joining the meeting must register by 15 Jun 2021, 7pm (SGT) through https://septusasia.com/hyflux-vtm-registration.
· On Friday, Aspial Corporation Limited (“Aspial”) announced a tender and exchange offer to holders of the ASPSP 6.250% 11Oct2021 Corp (SGD). Bondholders may tender their existing notes or exchange them for new 6% coupon notes maturing in July 2022. The new notes are expected to be issued on 1 Jul 2021 and will be guaranteed by Aspial. Bondholders who opt to exchange their holdings for the new notes are entitled to an exchange fee of 0.05 percent of the principal amount. The invite will expire at 10am on 23 Jun 21.
However with regard to the tender option, Aspial will only purchase up to SGD 10m in aggregate principal amount of the ASPSP 6.250% 11Oct2021 Corp (SGD), which has a remaining outstanding amount of SGD 78.5m.
In a separate matter this morning, the company announced that the scheme to acquire all of the shares in World Class Global Limited has been approved by majority of shareholders present and representing at least three-fourths in value of the scheme shares. World Class Global Limited is principally engaged in property development activities in Malaysia and Australia. It was 81.11% owned by MLHS Holdings Pte Ltd, which is Aspial’s controlling shareholder.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!