Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Important Events
- On Monday, the Bank of England (BoE) announced an expansion of its emergency purchase program for gilts by increasing its size of daily auctions for gilt purchases which they intend to use the unused capacity from their earlier auctions to increase the maximum size of their remaining auctions. Following which on Tuesday, it further widened its purchases to include index-linked gilts until Oct 14, which of the GBP 10b limit of daily gilt purchases, half will go to purchasing index-linked gilts. Despite the announcements, reaction remains relatively muted.
On another announcement, BoE refuted a report on the possible extension of the deadline on its emergency purchase program for gilts. Governor Andrew Bailey warned the pension fund managers that they only have those few days to complete their positions by, stressing that the programme was part of the BoE’s financial stability operations, not a monetary policy tool, and had to be temporary.
- From September’s FOMC meeting minutes, FOMC committee members suggested that an additional 75 basis point (“bps”) and 50 bps rate increases is possible at the November and December meetings respectively. The increase in rates are expected to slow down past December, hitting the peak policy rate in 1H23. It was indicated that US real GDP was increasing at a modest pace in the third quarter after a slowdown in the first half.
Based on the given data, projected core inflation was revised for 2022 and 2023, with the projection in 2025 to be at 2.1%. Similarly, the projections for total PCE price inflation were adjusted upwards, but still expected to slow down to 2.0% by 2025. The projected median Federal fund rate for 2022 by the committee increased from a 3.4% to 4.4%; for 2023, an increase from 3.8% to 4.6%; and for 2024, an increase from 3.4% to 3.9%.
- Last
Friday, MAS tightened its monetary policy by moving the centre of the S$NEER
policy band upwards at the prevailing level of the S$NEER. S$NEER had broadly
appreciated to near the top of the policy band, with 3M SIBOR increasing from
2.5% to 3.4% since July, and SORA from 2.1% to 3.4%. Inflation is likely to
remain high in most of Singapore’s key trading partners in the near term,
alongside a moderate global growth. A slower growth is expected for the
economy, on par with the weakening global demand.
Preliminary data showed Singapore’s economy grew 1.5% quarter-on-quarter (“QoQ”) on a seasonally-adjusted basis in 3Q22, in contrast to the 0.2% contraction in 2Q22, primarily contributed by the strong recovery in the tourism sectors considering the relaxed COVID-19 restrictions. GDP grew 4.4% YoY. The overall GDP growth is projected between 3-4% in 2022 for Singapore, with a below trend growth in 2023.
Core inflation rose to 4.9% YoY in July-August from 3.8% in Q2, while the overall inflation rose to 7.3% July-August, up from 5.9% in Q2. Inflation for discretionary goods and services was the major contributor, coupled with the increase in electricity & gas and non-cooked food inflation. Based on MAS projections, core inflation is likely to average around 4% with CPI-All Items inflation around 6% for whole of 2022. For 2023, inclusive of the GST increase, core inflation is expected at 3.5-4.5% on average with CPI-All Items inflation at 5.5-6.5%.
Asian High Yield Bond Index
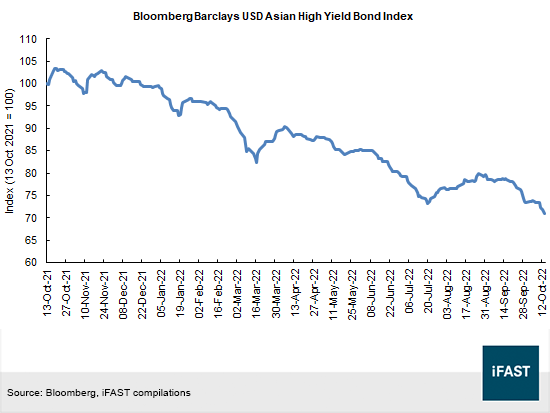
- The Barclays USD Asia High Yield Bond Index fell 3.3% for the week ended 14 October 2022.
- On Thursday, CIFI Group missed interest payment of CIFIHG 6.95% 08Apr25 (HKD) due 8 Oct 2022. This resulted in an event of default occurring. Fitch withdrawn CIFI Group's ratings as CIFI Group decided to stop participating in the rating process.
- On Friday, Road King Infrastructure redeemed USD33m of ROADKG 5.900% 05Mar2025 Corp (USD) and USD46m of ROADKG 6.000% 04Sep2025 Corp (USD).
Interest Rates and Currencies
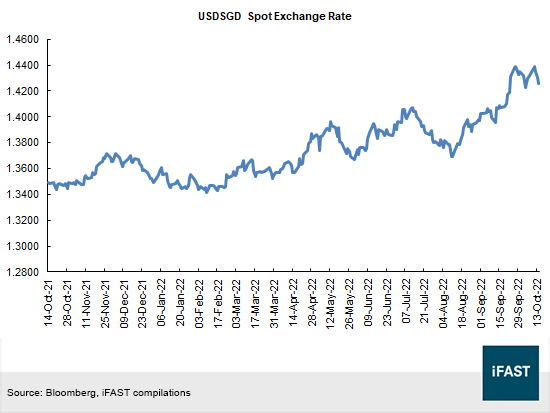
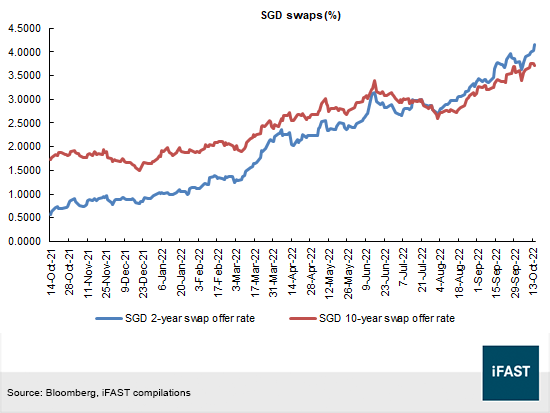
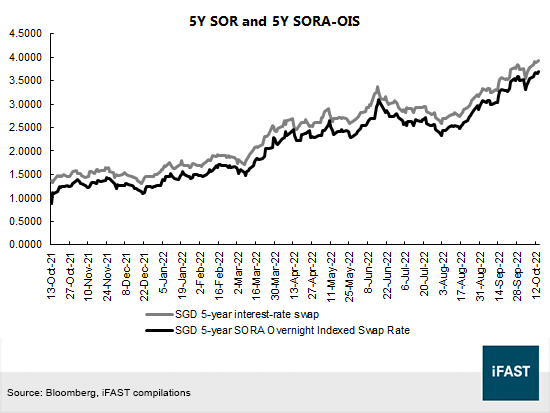
- The US dollar depreciated against the Singapore dollar last week with the USD/SGD currency pair ending at 1.426. The 2-year SGD Swap Offer Rate (“SOR”) increased by 27 bps to 4.160% and the 10-year SGD SOR increased by 8 bps for the week to 3.710%. The 5-year SOR increased by 15 bps to 3.920% while the 5-year SORA-OIS increased by 25 bps to 3.685%.
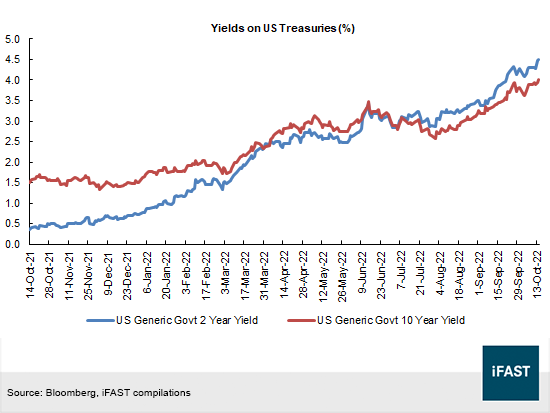
- Last week, the yield of 2-year US Treasuries (“UST”) increased by 19 bps to 4.496% while the 10-year UST increased by 14 bps to 4.018%. US CPI for September recorded a 0.4% increment from the previous month, and 8.2% increment year-on-year (“YoY”), both slightly above their respective projected rates. Core CPI rose by 6.6% YoY, hitting a 40-year high since 1982. Despite a 2.1% drop in energy prices, food prices rose by 0.8% for the month and 11.2% YoY, becoming one of the main contributor to the increase in CPI. Other significant increments include shelter costs (+6.6% YoY) and transportation services (+14.6% YoY).
Corporate Updates and New Issues
- On Monday, Overseas-Chinese Banking Corporation Limited (“OCBC”) announced a change in the appointment of Chief Financial Officer, with Mr. Darren Tan opting for an early retirement. The incoming Ms. Goh Chin Yee was previously the Head of Group Audit.
- On Monday, Sembcorp Marine Ltd (“SMMSP”) announced an update between its wholly owned subsidiary PPL Shipyard Pte Ltd and Borr Drilling Limited (“Borr Drilling”). Definitive agreements have been reached to defer the receivables from Borr Drilling from 2023 to 2025, resulting in Borr Drilling making earlier and higher amounts of interest payments and partial principal repayments from 2022 to 2024.
- On Tuesday, Koh Brothers Group Limited (“KOHSP”) announced the launch and pricing of the SGD 10,500,000 KOHSP 6.500% 17Apr2026 (SGD) Additional Notes, as part of the Series 003 Notes containing the New Notes. The New Notes were previously offered as an exchange offer to the bondholders of KOHSP 5.100% 27Oct2022 Corp (SGD). The Series 003 Notes will be issued at an issue price of 100 per cent, as a senior unsecured bond. The proceeds from the Additional Notes will used for general corporate purposes, including investments and capital expenditure requirements. Investors who are interested in the new issue may refer to our New Issue View here.
- On Wednesday, Keppel Offshore & Marine Limited (“Keppel O&M”) announced that it has entered into amended and restated framework deed to accelerate deliveries of three rigs and defer two others to Borr Drilling Limited (“Borr Drilling”). Keppel O&M will receive full payments of the first three rigs upon delivery, representing at least USD 352m in aggregate across 2022 and 2023, while the seller’s credit arrangements for the two remaining rigs cancelled. The delivery of the remaining rigs will be deferred to 2025.
- On Thursday, Singapore Airlines Limited (“SIA”) announced that they are currently in confidential discussions with Tata Group (“Tata”) to explore a potential transaction regarding the securities of Tata SIA Airlines Limited and Air India Ltd, a subsidiary of Tata. Tata SIA Airlines Limited operates an Indian full-service airline known as Vistara, which SIA holds a 49% equity in with the remaining 51% held by Tata. The discussions seek to deepen upon the existing partnership, potentially including an integration of Vistara and Air India.
- On Friday, Keppel Corporation Limited (“Keppel”) announced that its wholly-owned subsidiary, Keppel Offshore & Marine (“Keppel O&M”) has completed the modification works for four KFELS B Class jackup rigs which will be deployed on bareboat charters in Saudi Arabia in October. The rigs are expected to generate a total charter revenue of about SGD 250 million over three to five years.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!