Highlight
- Resilience Financial Performance: CBA continues to deliver resilience earnings driven by higher net interest income increase 6.5% YoY and solid loan growth of 7.1% YoY, which partially offsets ongoing net interest margin compression.
- Robust Asset Quality: Supported by low arrears, an improving NPL ratio to 1.02%, and strong borrower equity of loan to Value of 42%, providing a meaningful buffer against property market stress.
- Robust Capital and Liquidity Metrics: CET1 ratio of 12% and NSFR of 115% remain well above regulatory requirements and peer averages, indicating a strong capital buffer and stable long-term funding profile that supports resilience under stress scenarios.
- Outlook: Mortgage growth is expected to moderate from 7.1% in FY26 to 4%–6% in FY27 amid higher interest rates, tax reforms and affordability pressures. Nevertheless, structural housing shortages, resilient borrower equity buffers and CBA’s ability to reprice variable-rate mortgages should help sustain earnings resilience and contain credit risks.
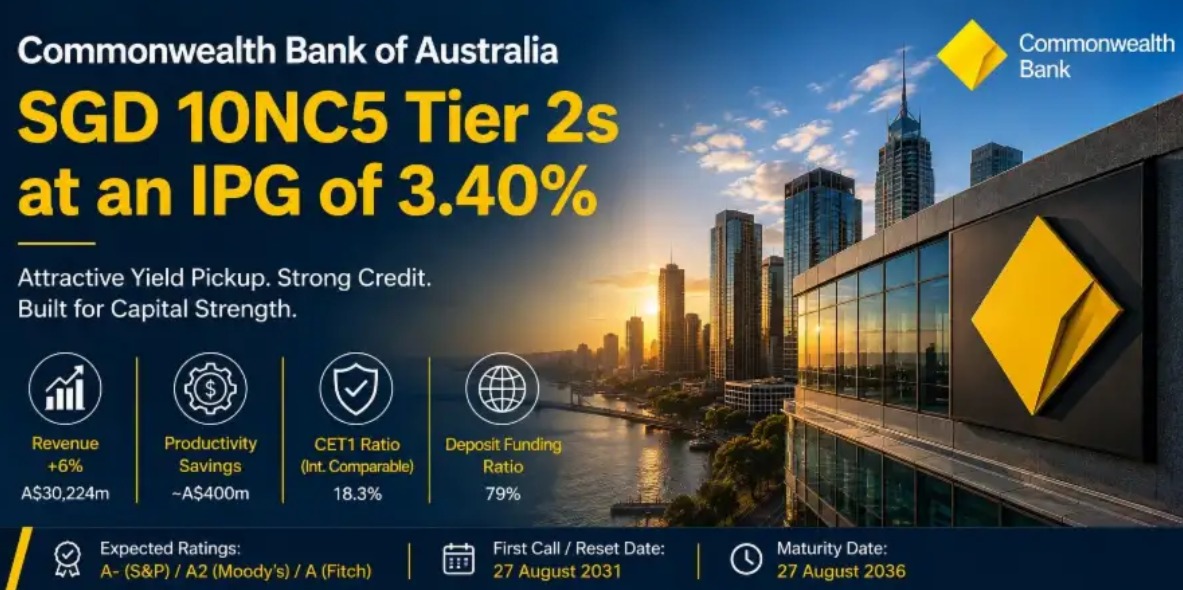
- Recommendation: We remain positive on CBA’s outstanding bonds and recommend bondholders hold.
Following our previous 3Q26 Credit Update, Commonwealth Bank of Australia (CBA) has released its FY26 results, providing further insights into its financial performance, asset quality and lending outlook. This update reviews the key developments since our previous assessment.
Previous Article Update: Credit Update: Commonwealth Bank of Australia –High-Quality Defensive Credit with Pickup (4.7%–6.2%) | Bondsupermart
Robust Loan Growth Offsets Net Interest Margin Compression
As shown in Table 1, CBA delivered a solid FY26 performance (as of June 2026), supported by continued loan expansion. Gross loans and acceptances rose by 7.1% YoY, while average interest-earning assets grew by 8% YoY, reflecting sustained lending momentum. This supported net interest income which increased by 6.5% YoY to AUD $25.6 billion.
However, net interest margin (NIM) declined by 3 basis point to 2.05%, primarily due to increased competition in home lending. Average interest-bearing liabilities expanded by 8.6%, outpacing asset growth. As a result, earnings growth remained largely volume-driven, with the gains from asset growth partially offsetting margin compression.
Non-interest income rose by 7.0% YoY to AUD $4.57 billion. This was supported by a 6.4% YoY increase in net commission income driven by higher volume-driven equities income, higher insurance income and higher fees from syndication activity. Meanwhile, cost-to-income ratio slightly improved from 46.0% to 45.7%, mainly because revenue growth (+6.6%) outpaced expense growth (+5.9%)
Finance costs declined by 2.3% YoY to AUD $40.1 billion, primarily driven by a lower average interest rate, which fell from 4.18% to 3.76% in FY26. Impairment losses have increase 8.5% YoY to AUD $0.79 billion reflecting portfolio growth, increased geopolitical risk and macroeconomic uncertainty. Overall, CBA’s FY26 results highlight resilient underlying performance, with robust loan growth despite modest margin pressures.
Table 1: CBA Financial Highlight
|
FY25 |
FY26 |
Change |
|
|
Net Interest Income (AUD $Billion) |
24.02 |
25.59 |
+6.5% |
|
Non-Interest income (AUD $Billion) |
4.27 |
4.57 |
+7.0% |
|
Net Interest Margin (%) |
2.08% |
2.05% |
-3bps |
|
Gross Loans and Acceptances (AUD $Billion) |
1,015.88 |
1,087.56 |
+7.1% |
|
Average Interest-Earning Assets (AUD $Billion) |
1,153.68 |
1,245.68 |
+8.0% |
|
Average Interest-Bearing Liabilities (AUD $Billion) |
982.22 |
1,066.95 |
+8.6% |
|
Source: Commonwealth Bank of Australia (CBA), iFAST compilations. Data as of 30 June 2026 |
|||
Asset Quality Remained Resilient Amid Macro Uncertainty
CBA maintains a dominant position in Australian housing finance, accounting for 25% of the mortgage market and 71% of its domestic loan book. Despite this concentration, borrower resilience remains strong, with Loan-to-Value Ratios at 42%, below the five-year average of 43.2%, providing a solid collateral buffer against potential property market corrections.
Asset quality remained resilient in FY26, with the NPL ratio improving to 1.02% from 1.08% in the previous year. While slightly above the five-year average of 0.96%, the ratio remains manageable, supported by a high average customer payment-in-advance level of 85%. The decline in Stage 2 and Stage 3 exposures further reinforces the bank’s underlying credit quality.
Amid rising geopolitical risks and macroeconomic uncertainty, provisions increased only modestly to AUD6.48 billion in FY26 (FY25: AUD6.38 billion). This reflects CBA’s existing approximately AUD2.7 billion buffer above expected credit losses under its central scenario, which provides an additional cushion against potential deterioration in asset quality. As this buffer can absorb higher-than-expected credit losses, the bank may not need to significantly increase its provisions unless the risk outlook deteriorates materially beyond current expectations.
Robust Capital, Liquidity and Funding Profile
Capital and liquidity positions remain robust. The CET1 ratio stood at 12.0%, comfortably above APRA’s minimum regulatory requirement of 10.25%, supported by organic capital generation from earnings (+106 bps), which was partly offset by dividend payments (-76 bps), higher Risk-Weighted Assets (RWA) (-46 bps). Liquidity metrics also stayed robust, with the Net Stable Funding Ratio (NSFR) at 115% and the Liquidity Coverage Ratio (LCR) average at 132%, well above regulatory thresholds of 100%, supported by an AUD 46 billion LCR surplus.
Funding remains stable anchored by a strong deposit base that accounts for 79% of total funding. This is supported by strong customer primacy, including a market-leading 34.2% retail main financial institution (MFI) share meaning around one in three Australians regards CBA as their primary bank, alongside deep ecosystem integration that enhances deposit stickiness. As a result, CBA benefits from a structural funding foundation, reflected in a customer deposit-to-loan ratio of 90.1% in FY26 (up from 89.5% in FY25). Wholesale funding is well laddered, with a weighted average maturity (WAM) of 5.2 years on long-term wholesale debt and no concentration in any single period, reducing rollover risk and strengthening balance sheet resilience in an uncertain interest rate environment.
How CBA fare against other Australian banking giants
Relative to its peer, CBA distinguishes itself with a robust capital and funding profile, reporting a high CET1 and an NSFR ratio, both at or in line with peer levels. This reflects a strong capital buffer and stable funding base, reinforcing its resilience under potential stress scenarios. Overall, CBA’s balance sheet metrics highlight in strength in capital and funding management, positioning it favourably among the Big Four banks.
Table 2: Peer Comparison
|
CBA |
WBC |
NAB |
ANZ |
|
|
Common Equity Tier 1 Ratio (CET1) |
12% |
12.1% |
11.93% |
12.51% |
|
CET1 Above Minimum Requirement |
+1.75% |
+1.85% |
+1.68% |
+2.26% |
|
Net Stable Funding Ratio (NSFR) |
115% |
112% |
115% |
113% |
|
Liquidity Coverage Ratio (LCR) |
132% |
132% |
134% |
131% |
|
* CET 1 minimum regulatory requirement is 10.25% ** NSFR and LCR minimum regulatory requirement is 100% Source: Company report, iFAST compilations. Data as of 30 June 2026 |
||||
Outlook: Mortgage Growth Moderates Amid Higher Rates and Tax Reforms, but Bank Earnings and Credit Quality Remain Resilient
FY26 loan growth remained strong at 7.1% YoY, management guidance points to a moderation in growth momentum ahead. Monthly home lending applications declined by 15% following the Federal Budget tax changes and were down 17% YoY. The decline was driven by weaker investor applications, which fell 28%, while owner-occupier applications decreased 9%, suggesting potential headwinds for mortgage growth in the coming quarters.
Accordingly, CBA’s management expects base case for mortgage credit growth in FY27 is narrowed to a tighter 4% to 6% range driven by Federal Budget tax reform measures, and domestic interest rate increases elevated.
Overall, while we expect weaker housing activity and softer property prices to weigh on mortgage lending growth in the near term, while structural housing shortages, resilient household fundamentals, strong borrower equity buffers and contained asset quality deterioration should help limit risks.
At the same time, the predominantly variable-rate mortgage structure allows CBA to reprice a large portion of their housing loan books as interest rates change, providing support for overall lending income and earnings resilience despite slower loan growth.
Related Article
Recommendation
CBA delivered a resilient FY26 performance, supported by solid loan growth and higher non-interest income, which helped offset ongoing margin pressure. Asset quality remained sound, backed by strong borrower equity, prudent provisioning and a robust capital, liquidity and funding profile.
Looking ahead, mortgage growth is expected to moderate amid higher interest rates and tax reforms. Nevertheless, structural housing shortages, resilient household fundamentals and the ability to reprice variable-rate mortgages should help support earnings and credit quality.
We recommend existing bondholders to hold and remain positive on CBA’s outstanding bonds (Table 2 and 3).
Among our recommended bonds, we favour CBAAU 5.180% 9 October 2035 (AUD) senior unsecured bonds and CBAAU 6.152% 27 November 2039 (AUD) Tier 2 bonds. Both bonds currently offer attractive yields above 6% and fit our long-duration preference under the barbell strategy, alongside shorter-duration bonds.
It is important to note that Tier 2 bonds carry loss absorption risk, as their loss-absorbing features may be triggered in the event of a non-viability scenario. When assessing these instruments, both yield and years to call are key considerations. Under Basel III regulations, Tier 2 bonds not redeemed past their call date must be amortised, which encourages issuers to call and refresh their Tier 2 capital earlier.
Table 2: CBA’s Senior Unsecured Bond
|
Bond name |
Year to Maturity |
Yield to Maturity |
Min / Sub investment amount |
Credit Rating (Fitch) |
|
3.40 |
5.1% |
USD 2,000 /1,000 |
AA |
|
|
1.23 |
5.4% |
AUD 200,000/10,000 |
AA- |
|
|
4.24 |
5.5% |
AUD 10,000/10,000 |
AA |
|
|
9.0 |
6.0% |
AUD 10,000/10,000 |
N.R. |
|
|
Source: Bondsupermart, iFAST Compilations. Data as of 21 October 2026. |
||||
Table 3: CBA’s Tier 2 Bond
|
Bond name |
Year to Call/Maturity |
Yield to Call/Maturity |
Min / Sub investment amount |
Credit Rating (Fitch) |
|
4.85/9.85 |
3.3%/3.3% |
SGD 250,000/ 250,000 |
A |
|
|
2.90/ 7.90 |
5.7%/6.4% |
USD 200,000/1.000 |
A |
|
|
1.05/ 6.05 |
5.8%/7.1% |
AUD 200,000/ 1,000 |
A |
|
|
3.90/8.90 |
6.0%/6.2% |
AUD 10,000/10,000 |
A |
|
|
8.11/ 13.11 |
6.5%/6.5% |
AUD 200,000/10,000 |
A |
|
|
Source: Bondsupermart, iFAST Compilations. Data as of 21 October 2026. |
||||