


KAJV is proposing the early redemption of all outstanding Sukuk amounting to RM504 million under its RM1.0 billion Sukuk Programme, following an informal meeting held on 13 October 2026.
The proceeds raised under the Sukuk Programme were utilised to refinance bridging facilities that partially funded the water supply project in Kuala Terengganu.
Following the successful completion of the Project, the Issuer is proposing the early redemption to optimise its funding costs while providing Sukukholders with an opportunity to realise their investments ahead of the scheduled maturity dates at a premium to the prevailing mark-to-market (MTM) levels.
The Issuer has proposed a redemption premium of 65 basis points (bps). The early redemption is expected to take place on 10 December 2026.
The proposed redemption price for each tranche is set out in the table below.
Table 1: Redemption Price
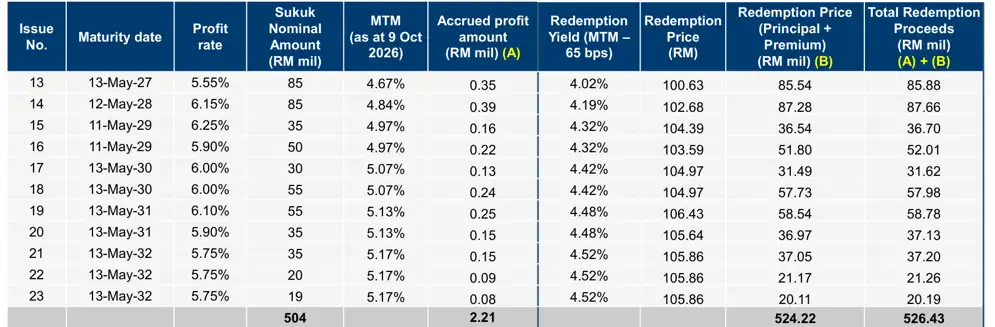
Source: KAJV Presentation Slides
There are 2 special resolutions requiring sukukholders’ approval:
Special Resolution 1: To approve Proposed Early Redemption of Outstanding Sukuk at the redemption premium and redemption price to be agreed and further indebtedness to fund the Proposed Early Redemption
Special Resolution 2: To approve for shorter notice period of not less than [7] days for KAJV to provide the notice of redemption to the Facility Agent and Sukuk Trustee
***All resolutions above form part of a single refinancing transaction and must be approved together
Should Sukukholders Accept the Early Redemption Offer?
We have conducted mathematical calculations and scenario analysis to compare the outcomes of accepting the early redemption offer versus continuing to hold KONKAJ 6.150% 12 May 2028 Corp (MYR) until maturity.
Table 2: Assumptions: Accepting the Early Redemption vs. Holding to Maturity
|
Scenario Comparison (MYR) |
|
|
|
|
|
Scenario |
Principal Received |
Interest Days |
Coupon Interest |
Total Proceeds |
|
Hold to Maturity |
1,000,000.00 |
546 |
91,997.26 |
1,091,997.26 |
|
Early Redemption (at Premium) |
1,026,800.00 |
27 |
4,549.32 |
1,031,349.32 |
|
Difference (Hold vs Redeem) |
(26,800.00) |
519 |
87,447.95 |
60,647.95 |
|
Incremental Return from Holding to Maturity |
|
|
Additional Proceeds (MYR) |
60,647.95 |
|
Holding Period Return |
5.88% |
|
Annualised Return |
4.14% |
In other words, if you accept the early redemption, you will need to seek alternative investments that can offer a comparable yield of 4.14% over a similar investment horizon of approximately 1 year and 7 months. Given the current market environment, finding comparable or higher yields within the MYR bond market may be challenging.
From a reinvestment perspective, investors may therefore consider rejecting the early redemption offer, as alternative MYR bond investments offering similar or better yields over a comparable investment horizon of approximately two years may be limited.
However, if liquidity is your priority and you prefer to recover your investment earlier, you may consider accepting the early redemption offer, bearing in mind the associated reinvestment risk.
***Please note that if the Special Resolution is passed with the required 75% majority, it will be binding on all Sukukholders, including those who voted against it.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.