- Service Corporation International (SCI) engages in the funeral industry and provides funeral-related services in the US and Canada. While the deathcare industry is highly fragmented, the company did not increase its investment in the industry or seek large acquisitions with peers.
- SCI’s atneed businesses are more sustainable in terms of demand, and its preneed services show a signal of continued growth. Its cash flow performance is expected to remain solid, and the business model is sound. Its leverage level is decent. The overall solvency is strong.
- Investors could consider SCI bonds with different tenors, with a yield to maturity of up to 5.7%.
Service Corporation International (SCI) engages in the funeral industry and provides funeral-related services, including deathcare, funeral, cremation and cemetery provision and management services, etc. SCI is currently listed on the New York Stock Exchange (Stock Code: SCI.US) with a market capitalisation of around USD 10.42 billion.
Deathcare Industry is Highly Fragmented; SCI did not Increase its investment in the Industry or Seek Large Acquisitions with Peers
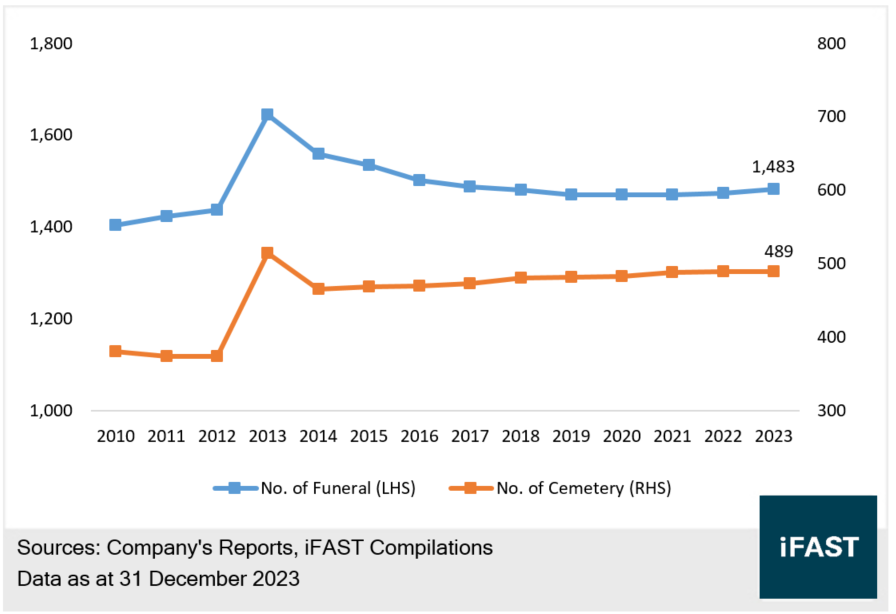
SCI currently operates a total of 1,483 funeral service locations and 489 cemeteries in the US and Canada. Most of them are located in the US. About 90% of these properties are self-owned. The remaining are operated through leasing.
SCI has a market share of up to around 15% (See Chart 1), which is higher than the sum of the other scale peer groups. Hence, SCI is the absolute industry leader in the US.
Chart 1: The US and Canada Funeral Industry - Market Share by Revenue
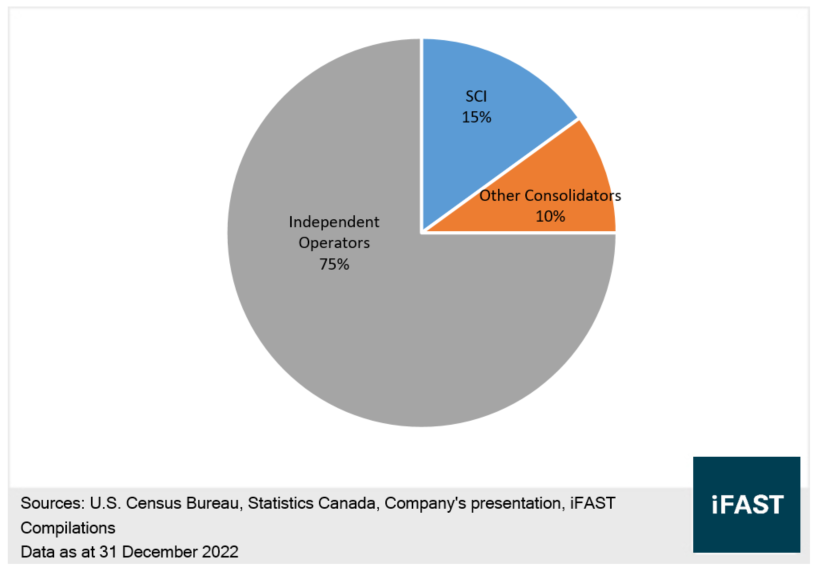
The deathcare industry
is a highly fragmented market with individual operators accounting for
approximately 75% of the market share. While this could be favourable for SCI
to pursue M&A with individual operators, it has little interest in doing
so. Referring to Figure 2, the number of funeral locations and cemeteries has
been gradually stable since 2014, showing that the company did not increase its
investment in the industry or seek large acquisitions with peers. We expect
that the company will maintain this operational strategy in the future, which
will manage its capital expenditures and M&A costs, thus driving its cash
flow performance.
Chart 2: The Number of SCI’s Operating Funeral Locations and Cemeteries (Including Self-owned and Leased)
Atneed Businesses are More Sustainable in terms of Demand; Preneed Services show a Signal of Continued Growth
As shown in Chart 3, SCI can be categorised into two segments: the Funeral segment and the Cemetery segment, which accounts for around 56% and 44% of its revenues respectively. The Funeral segment could be further divided into the Atneed, Matured Preneed and Non-Core business, while the cemetery segment could be further segmented into Atneed, Preneed Property, Preneed Merchandise & Services and non-core business.
Chart 3: SCI’s Revenue Breakdown
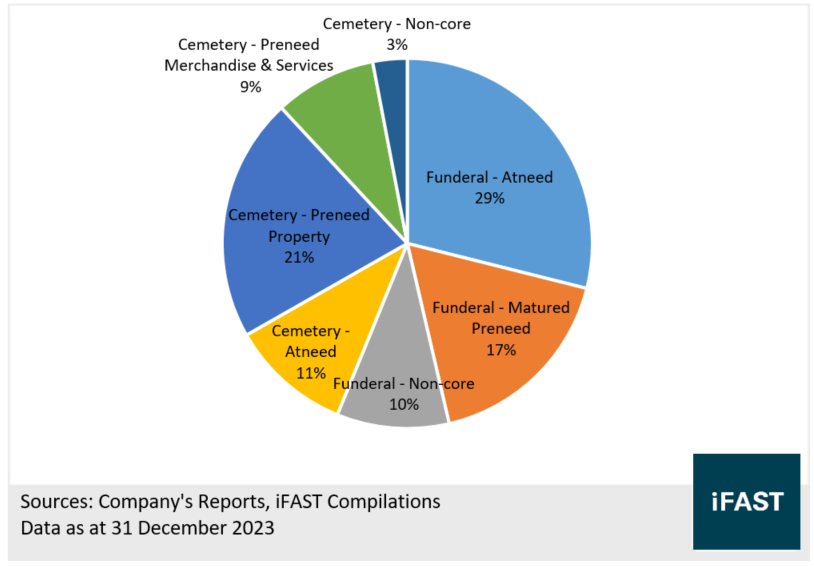
Amongst these, the atneed businesses in both the funeral and cemetery segments are more sustainable in terms of demand. These are of greater necessity for the bereaved. In general, they are willing to pay a higher price for these services. That said, the company has certain pricing power and it could raise its service prices by around 3% to 5% per year.
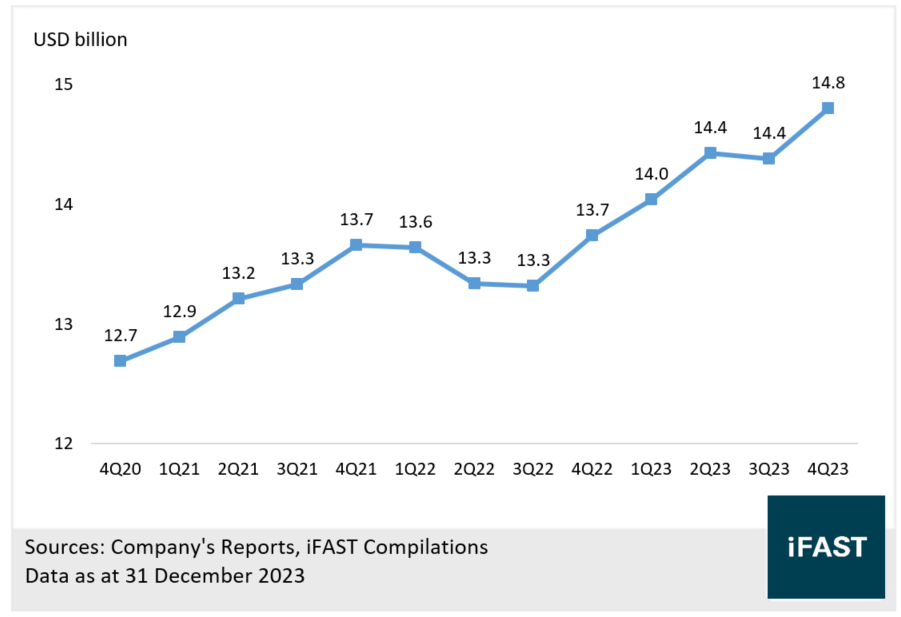
As for the presale-related businesses, as shown in Chart 4, SCI's total backlog of deferred revenues continued to rise to USD 14.8 billion. These funeral preneed and cemetery preneed services show a signal of continued growth, given that more and more people are willing to arrange the deathcare in advance for themselves or their relatives.
With resilient businesses, SCI could generate revenues on a recurring basis. The company aims to achieve an organic growth of 5% to 7% per annum in the short to medium term.
Chart 4: SCI’s Total Backlog of Deferred Revenues
Expected the Cash Flow
Performance to Remain Solid with its Sound Business Model
In 2023, SCI’s EBITDA was around USD 1.26 billion (Chart 5), increased by 2.4% YoY. This was driven by a slight growth in revenues, stable delivery of its backlogs into revenues and a significant cut in administrative costs. However, the company’s gross margin was only 26.6% in the same period, which declined by 147 bps compared to 2022, mainly attributable to an increase in the proportion of the cremation business which has a lower gross profit margin.
Chart 5: SCI’s EBITDA, Operating Cash Flow and Gross Margin
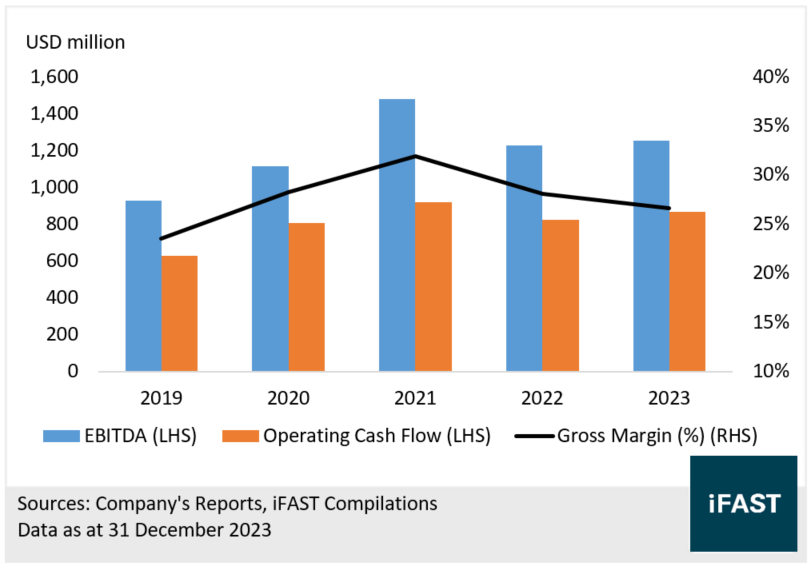
In addition, SCI’s operating cash flow increased 5.3% YoY to USD 870 million in 2023. Looking forward to 2024, SCI provided operating cash flow guidance of USD 900 million to USD 960 million for the current year, which represents a YoY growth ranging from 3.5% to 10.5%. It is expected its cash flow performance to remain solid.
Overall, SCI's business model is sound. The operating performance is quite stable, which is also favourable to its credit profile.
Decent Leverage Level and Strong Solvency
With SCI’s stable business and large pre-sales (preneed) businesses, the company has accumulated a large amount of cash. Thus, the company established a cemetery trust fund, called Cemetery Perpetual Care Trust Fund, many years ago, to generate investment returns and cash flows where the company can take advantage to fund the expenses of maintaining its cemeteries and properties.
At the end of 2023, SCI's cemetery trust fund has a fair value of USD 1.93 billion. If we treat this trust as cash and cash equivalent, its net debt is only USD 2.55 billion (see Table 1). Its net debt/EBITDA and net debt/operating cash flow are only 2.0x and 2.9x, respectively, showing a decent leverage level.
Table 1: SCI’s Main Credit Indicators
|
Dec 21 |
Dec 22 |
Dec 23 |
|
|
Total Debt (USD billion) |
4.06 |
4.44 |
4.71 |
|
Net Debt (USD billion)* |
1.79 |
2.54 |
2.55 |
|
Undrawn Credit Facility (USD billion) |
0.81 |
0.40 |
0.67 |
|
Net Debt* / EBITDA (times) |
1.2x |
2.1x |
2.0x |
|
Net Debt* / Operating Cash Flow (times) |
1.9x |
3.1x |
2.9x |
|
Interest Coverage Ratio (times) |
9.8x |
7.1x |
5.2x |
|
Average Cost of Borrowings (%) |
3.8% |
4.1% |
5.2% |
|
*Net Debt = Total Debt – Cash – Fair Value of Cemetery Perpetual Care Trust Fund Source: Company Reports, IFAST compilations Data as of 31 December 2023 |
|||
In addition, due to the rising interest rates, SCI's interest expense rose by nearly 40%, with the average cost of borrowings increasing to 5.2%. However, its interest coverage ratio is still as high as 5.2 times, which shows a strong interest payment capability. The company also has around USD 670 million of undrawn credit facilities provided by banks, which can be used for new financing or refinancing purposes. The overall solvency is strong.
Investors could consider SCI Bonds with Different Tenors
SCI’s issuer credit rating is BB+ (S&P), and bond credit rating is BB (S&P). Both belong to the higher levels under non-investment grade.
Given SCI’s stable business model, massive cemetery trust fund and decent leverage level, the company's solvency is strong. We believe its short to medium term debt default risk is low.
Referring to Table 2, the net yield to maturity of SCI's bonds with different tenors is close to 5.7%, which have certain attractiveness. Investors looking for stable income can consider them.
Table 2: SCI’s Bonds
|
Bond Name |
Years to Maturity |
Ask Price (Investors Buy) |
YTM |
|
3.8 |
96.8 |
5.6% |
|
| SCI 5.125% 01Jun2029 Corp (USD) | 5.3 |
97.8 |
5.7% |
|
Source: Bondsupermart Data as of 16 February 2024 |
|||
Related Risks
The fair value of SCI's cemetery trust fund is subject to fluctuations in the equity and bond markets. The poor market performance could result in a decline in the fair value, which could affect its liquidity. Since the company will take advantage of cash flows and investment income provided by the trust fund for the expenses related to the maintenance of cemeteries and properties. The weak performance could also add pressure to the company's operations.
SCI’s drawn bank credit facility limits the company’s net debt (excluding the fair value of the Cemetery Trust) / EBITDA to 5 times or less. The ratio is at 3.6 times. However, if the company’s profitability has a significant decline, causing this ratio to rise above 5 times. The banks could require the company to repay the bank loans in advance, which would significantly increase its liquidity pressure.
Conclusion
Service Corporation International (SCI) engages in the funeral industry and provides funeral-related services in the US and Canada. While the deathcare industry is highly fragmented, the company did not increase its investment in the industry or seek large acquisitions with peers.
SCI’s atneed businesses are more sustainable in terms of demand, and its preneed services show a signal of continued growth. Its cash flow performance is expected to remain solid, and the business model is sound. Its leverage level is decent. The overall solvency is strong.
Investors could consider SCI bonds with different tenors,
with a yield to maturity of up to 5.7%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!