After announcing the voluntary administration of the Basslink group in the middle of November, Keppel Infrastructure Trust (“KIT”) is seeking to raise debt capital through a 5-year senior bond offering under its SGD 2b Multicurrency Debt Issuance Programme. The bonds have an initial price guidance (“IPG”) of 3.125%.
Net proceeds from this new issue may be used to refinance existing borrowings, finance acquisitions, asset enhancements, capital expenditures or any other general working capital purposes of the trust. As of 12pm today, the orderbook for this offering has exceeded SGD 210m.
About the senior bonds
The bonds are senior unsecured fixed rate notes of the issuer - Keppel Infrastructure Fund Management Pte. Ltd., who is the trustee-manager of Keppel Infrastructure Trust. The bonds will mature on 1 December 2026 and they come with accompany negative pledge and financial covenants. One of them requires the trust to have an Adjusted EBITDA to Net Interest Expense of at least 3.5x (calculated at the trust level).
Under the terms of this offering, the issuer may also redeem the bonds in the event of the termination or delisting of KIT, or taxation event or if the bonds have a minimal outstanding amount.
About KIT
Keppel Infrastructure Trust is the biggest business trust listed on the Singapore Exchange with SGD 4.2b of assets under management as at 30 September 2021. Most of its assets are invested in Singapore (65%), Philippines (4.8%) and 30.2% in Australia, New Zealand and other countries. The trust will invest in companies or assets in the infrastructure sector to provide a sustainable and recurring distribution to its unitholders.
As manager of KIT, Keppel Infrastructure Fund Management Pte. Ltd. is a wholly owned subsidiary of Keppel Capital Holdings Pte. Ltd (a wholly-owned subsidiary of Keppel Corporation Limited). KIT is 81.8% owned by public investors and 18.2% owned by Keppel Infrastructure Holdings Pte. Ltd. (which is also a wholly-owned subsidiary of Keppel Corp).
For a list of KIT’s portfolio and assets, kindly refer to our earlier article “Keppel Infrastructure Trust to issue SGD NC10 perps at 4.55% IPG”
Recent corporate developments
KIT has a 70% interest in the Singspring Desalination Plant. In July 2021, the manager of KIT entered into a conditional sale and purchase agreement with the judicial managers of Hyflux Ltd to acquire the remaining 30% stake in the Singspring Plant for SGD 12.0m. Regulatory approvals from PUB and others are being sought to complete the acquisition. Upon completion, a subsidiary of Keppel Infrastructure Holdings will take over the provision of operation and maintenance services to the Singspring Plant.
Hydro Tasmania and the State of Tasmania have been in arbitration proceedings with the Basslink group in relation to an outage at the Basslink Interconnector since 2018. In June this year, a standstill agreement has been put in place between the parties to allow further negotiations to settle Basslink’s obligations.
However, the State of Tasmania and Hydro Tasmania decided not to extend the standstill agreement on 27 October 2021. Basslink has to pay AUD 33.3m under the Services Agreement and AUD 25.3m of arbitration costs to Hydro Tasmania. In August, KIT received a confidential proposal from the APA Group to acquire Basslink but the sale was not successful. More recently on 12 November 2021, Basslink and its subsidiaries were placed under voluntary administration.
KIT says there is no contractual recourse to the trust under the financing arrangements that are currently in place for the Basslink Interconnector. Basslink’s revenue for the 6-month period ended 30 June 2021 (“1H21”) was SGD 45.5m, which is small compared to the group’s revenue of SGD 783.5m. Basslink had AUD 625.8m amortising loan as of September 2021. The events of Basslink Interconnector is not expected to have any financial impact on the distribution per unit of KIT as the group does not rely on Basslink’s cashflows for distribution of its units.
Financial and credit highlights
The trust reported a slightly weaker performance in its most recent update with SGD 239.7m of adjusted EBITDA in 9M21, down from SGD 243.8m in 9M20. Free cash flow to equity (“FCFE”) also dropped 8.3% to SGD 145.4m (9M20: SGD 158.5m). FCFE at City Gas decreased SGD 8.79m but this was moderately offset by higher cash flows at Ixom (+SGD 2.48m) and Philippine Coastal (+SGD 5.23m).
Trust liquidity is adequate as at 1H21. KIT had SGD 650.0m of cash and bank deposits, which together with its SGD 150.8m of operating cash flow before working capital changes, is sufficient to cover its SGD 779.0m of short-term borrowings. As we understand, the bulk of KIT’s short-term borrowings comprise of the Basslink AUD loan and there is no recourse to the trust under current financing arrangements.
On the financial impact of excluding Basslink as at 9M21, KIT guided that the cash position of the trust falls from SGD 599m to SGD 561m. Borrowings decline to SGD 1,523m from SGD 2,139m if we exclude borrowings at Basslink. Net gearing also improves. With lower assets and borrowings, KIT’s net debt over total assets decreases to 22.7% from 30.3%.
Relative valuation
We think that the 3.125% IPG for the new 5-year SGD KIT bonds is fairly priced along the curve for Keppel Corp related entities (Figure 1). The new 5-year bonds provide the highest yield along the curve but this assumes that the KEPSP 3.800% 23Apr2027 Corp (SGD) and KPTTSP 2.850% 05Sep2024 Corp (SGD) are redeemed at their first call dates in April 2022 and March 2023 respectively.
Figure 1: Relative valuation among SGD fixed rate bonds using their indicative yields-to-worst
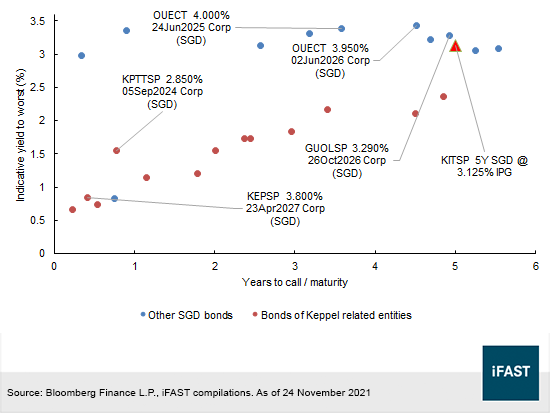
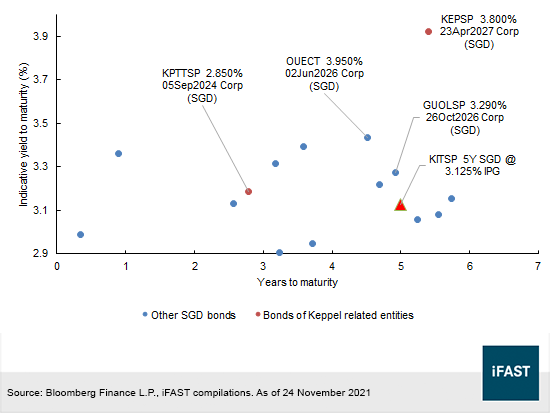
The 3.125% IPG would not be as attractive if Keppel Corp does not redeem the KEPSP 3.8% 2027’s in April next year as the latter would give a higher yield to maturity of 3.91%. If not redeemed, the KEPSP 3.8% 2027 notes will have a coupon step up to 4.20%, providing a step up of 108 basis points above the new issue’s initial price guidance. Apart from bonds issued by Keppel entities, there are other SGD alternatives that provide investors a higher yield.
Alternatives include the OUECT 3.950% 02Jun2026 Corp (SGD) (YTW: 3.43%), OUECT 4.000% 24Jun2025 Corp (SGD) (YTW: 3.39%) or the GUOLSP 3.290% 26Oct2026 Corp (SGD) (YTW: 3.27%). For more information on the GUOLSP 3.29% 2026’s, kindly refer to the article “GuocoLand launches new 5Y bond at 3.5% IPG”. Investors may also read “OUE Commercial REIT offers new 5-year SGD bonds at 4.15% IPG” for more details on the OUECT 3.95% 2026’s.
Figure 2: Relative valuation using indicative yields-to-maturity
Declaration: For or specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in KEPSP 2.900% Perpetual Corp (SGD), GUOLSP 3.290% 26Oct2026 Corp (SGD), OUECT 3.950% 02Jun2026 Corp (SGD) and OUESP 3.750% 17Apr2022 Corp (SGD). The analyst who produced this report is a unitholder of Keppel Infrastructure Trust.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!