Highlight
- Strong Revenue Visibility: Secured RM395 million in sales and with RM1.1 billion in unbilled sales, providing strong earnings visibility and supporting future cash flow generation.
- Backed by Sizeable Landbank: 3,918-acre landbank and the RM8.3 billion Kwasa Damansara township strengthen its long-term growth prospects, while its 13 ongoing projects (GDV: RM4.19 billion) provide a solid pipeline for future earnings
- Project Completions Temporarily Weighed on 1Q26 Earnings Amid Strong Development Pipeline: 1Q26 earnings were affected by lower revenue recognition following project completions. However, the Group maintains a strong ongoing development pipeline.
- Stable Credit Profile: While debt has slightly increase, resulting in a net gearing ratio of 39%, liquidity remain resilience with an interest coverage ratio of 5.0 times.
- Bond Issuance: LBS Bina issued 7-year bond offering indicate yield to maturity of 4.3%.
Company Overview
LBS Bina Group Berhad is one of Malaysia's listed established property developers, with a diversified portfolio spanning residential, commercial, industrial, and township developments. The Group focuses primarily on affordable and mid-market housing while gradually expanding into higher-value developments in strategic growth corridors.
Strong Revenue Visibility and Development Pipeline
As of 25 May 2026, the Group had recorded RM395 million in sales, with an additional RM302 million in bookings, providing healthy near-term revenue visibility. Sales momentum has been supported by strong demand for key developments, including Centrum Iris (Cameron Highlands), Alam Perdana Industrial Park (Selangor), and KITA Sejati (Cybersouth).
A key addition to LBS's development pipeline is the 192.32-acre premium residential project in Kwasa Damansara (PJ West), which carries an estimated gross development value (GDV) of RM8.30 billion. Scheduled for launch in 2027 with a 14-year development timeline, the project marks a strategic expansion into the higher-end residential segment, complementing the Group's traditional focus on affordable housing.
In addition, LBS had 13 ongoing development projects as at 31 December 2025, with a combined GDV of RM4.19 billion. Major active developments include Alam Perdana Industrial Park (GDV: RM1.08 billion) and Pangsapuri Saujana Indah in Johor (GDV: RM438 million), providing a solid pipeline for future earnings recognition.
As shown in Table 1, the Group’s extensive 3,918-acre landbank, primarily located across the Klang Valley, Johor, Pahang, and Perak, provides a strong foundation for long-term growth, while its RM1.1 billion in unbilled sales supports sustained earnings visibility and reinforces project delivery momentum over the medium to long term.
Table 1: LBS Bina Landbank Status
|
State / Region |
Remaining Landbank (Acres) |
Key Projects / Township |
|
Klang Valley |
894 |
KITA @ Cybersouth, LBS Alam Perdana, Kwasa Damansara |
|
Johor |
1,136 |
Bandar Putera Indah, Pangsapuri Saujana Indah |
|
Negeri Sembilan |
1,100 |
Includes the 43 MWp Solar Farm project in Senawang |
|
Pahang |
411 |
Cameron Centrum, Rimbawan (Genting Highlands) |
|
Perak |
371 |
Taman Kinding Flora |
|
Sabah |
6 |
- |
|
Source: LBS Bina, iFAST Compilation. Data as of 31 March 2026 |
||
Project Completions Temporarily Weighed on 1Q26 Revenue, While Development Pipeline Remains Strong
LBS Bina recorded a 9.9% YoY revenue decline in 1Q26 as of 31 March 2026, with revenue falling to RM296.5 million (Table 2). This decrease was primarily driven by the completion or near-completion of certain development projects in FY25 as of 31 December 205, which resulted in lower revenue recognition for the period.
Despite lower revenue recognition, we do not see this as a slowdown for LBS Bina’s real estate development business, as the Group maintains robust near-term visibility with RM1.1 billion in unbilled sales and demonstrates strong market demand, having secured RM395 million in sales and RM302 million in bookings as of 25 May 2026 and strong development pipeline as highlight above.
Table 2: LBS Bina Profitability Indicators
|
(RM Million) |
1Q25 |
1Q26 |
YoY |
|
Revenue |
329.2 |
296.5 |
-9.9% |
|
Operating profit |
36.5 |
24.3 |
-33.4% |
|
Operating profit Margin |
11.1% |
8.2% |
-26.0% |
|
Source: LBS Bina, iFAST Compilation. Data as of 31 March 2026 |
|||
Credit Metrics Remain Healthy Despite Slight Increase in Leverage
As shown in Table 3, LBS Bina's total debt increased marginally by 2.5%, from RM1.36 billion to RM1.40 billion. The increase was mainly attributable to significant cash outflows incurred during the 1Q26 to advance its development projects, including RM16.8 million for capital work-in-progress and RM16.5 million in deposits and consideration paid for the acquisition of development land and joint venture arrangements.
Consequently, the Group's net gearing ratio increased slightly to 38.9%, while net debt-to-total property assets rose to 32%. Nevertheless, as at 30 April 2026, LBS Bina maintained a healthy unbilled sales balance of RM1.1 billion, which is expected to support future operating cash flows and keep leverage at a manageable level.
Meanwhile, the cash-to-short-term debt ratio declined from 1.95 times to 1.60 times, primarily due to cash outflows associated with land acquisition and property development activities amounting to RM56.2 million. Interest coverage also weakened significantly from 8.4 times to 5.0 times, mainly due to lower revenue recognition as several projects approached completion during the period, resulting in lower operating earnings.
Meanwhile, the cash-to-short-term debt ratio declined from 1.95 times to 1.60 times, primarily due to cash outflows associated with land acquisition and property development activities amounting to RM56.2 million. Interest coverage also weakened significantly from 8.4 times to 5.0 times, mainly due to lower revenue recognition as several projects approached completion during the period, resulting in lower operating earnings.
Despite the decline, we believe LBS Bina Group Berhad continues to maintain a broadly adequate liquidity and debt-servicing buffer. As shown in Table 4, its credit metrics remain healthy relative to peers. The Group’s net gearing ratio of 38.9% and net debt-to-property assets ratio of 32.0% are still within a moderate range, compared with peers such as Avaland Berhad and Sunsuria Berhad, whose gearing levels are higher at approximately 49.3%.
In addition, LBS Bina’s interest coverage ratio of 5.0 times remains stronger than that of its peers, reflecting solid earnings capacity to meet interest obligations. Overall, while recent moderation in cash flow and coverage metrics suggests some near-term softness in operating performance, the Group’s balance sheet position remains relatively resilient within the sector, supported by prudent financial management.
Table 3: LBS Bina Key Credit Metrics
|
FY25 (Dec 25) |
1Q26 (Mar 26) |
|
|
Total Debt |
1,362.1 |
1396.7 |
|
Interest coverage ratio (times) |
8.36 |
5.00 |
|
Net gearing ratio (%) |
32.0% |
38.9% |
|
Net debt/total property assets ratio (%) |
26% |
32% |
|
Cash to short term debt (times) |
1.95 |
1.60 |
|
Source: LBS Bina, iFAST Compilation. Data as of 31 March 2026 |
||
Table 4: Peer Comparison
|
LBS Bina |
Sunsuria |
Avaland |
|
|
Interest coverage ratio (times) |
5.00 |
3.56 |
3.31 |
|
Net gearing ratio (%) |
38.9% |
49.3% |
36.3% |
|
Net debt/total property assets ratio (%) |
32% |
62% |
27% |
|
Source: LBS Bina, iFAST Compilation. Data as of 31 March 2026 |
|||
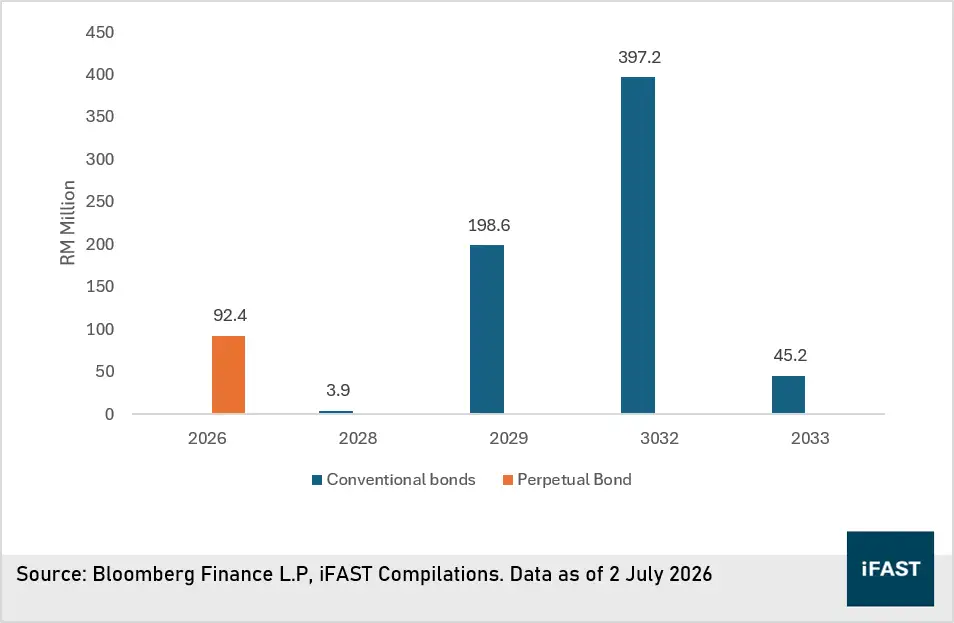
LBS Bina's debt maturity profile, as illustrated in Chart 1, is relatively front-loaded, with the largest maturity of approximately RM397 million falling due in 2032. Nevertheless, the Group maintains a strong liquidity position, supported by cash balances of RM550 million and RM1.1 billion in unbilled sales as at 1Q26, which are sufficient to fully cover its upcoming debt maturities. Furthermore, LBS Bina's gearing remains at a moderate level relative to its peers (Table 4) and is expected to stay within a manageable range, providing adequate financial flexibility to support its ongoing development pipeline and future growth.
Chart 1: LBS Bina’s Debt Maturity Profile
Recommendation
Overall, LBS Bina’s strong revenue visibility and solid development pipeline, together with its manageable leverage, underpin a stable credit outlook over the near to medium term.
LBS Bina is expected to return to the bond market in July 2026, subject to prevailing market conditions. The company intends to issue an unsecured 7-year bond with an indicative yield of approximately 4.32%, targeting an issuance size of around RM150 million. The proposed issuance unsecured bond is rated AA- by MARC with a Stable Outlook.
We view the proposed issuance as offering approximal yield pickup of 75bps over Malaysia Government Securities (MGS), supported by LBS Bina’s sizable landbank and strong development pipeline, which underpin its stable credit profile.
In addition, the existing LBSMK 6.850% Perpetual Corp (MYR) is scheduled for its first call option in July 2026. We view that LBS Bina is likely to exercise the call option, supported by its sizeable cash balance of RM550 million as at 31 March 2026 and its continued healthy financial position.
For existing holders of LBSMK 5.000% 23Jan2029 Corp (MYR) and LBSMK 4.810% 23Jan2032 Corp (MYR), we recommend maintaining current holdings, as the LBS Bina continues to demonstrate resilient operating fundamentals, healthy liquidity, and adequate debt servicing capacity.
Table 5: LBS Bina Bonds
|
Bond Name |
Year to Call/Year to Maturity |
Yield to Call/Yield to Maturity |
Issue Size (RM Million) |
|
LBSMK Jul2033 Corp (MYR)* |
-/7.1 |
-/4.3% |
150 |
|
0.01/- |
6.2%/11.9% |
93 |
|
|
-/2.6 |
-/3.7% |
200 |
|
|
-/5.6 |
-/4% |
400 |
|
|
* Investors should note that the final issuance yield may differ from the initial guidance, depending on market demand and pricing conditions at the time of issuance. Source: Bondsupermart, iFAST Compilation. Data as of 3 July 2026 |
|||
Declaration
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report holds a NIL position in the abovementioned securities.