Important Events
- On Tuesday, Bank Indonesia (“BI”) kept its key interest rates at a record low of 3.50%. The central bank planned to raise its reserve requirement ratio (“RRR”) for banks more aggressively in the future, with staggered hikes this year starting with 7.5% of reserves in July, followed by 9% from September onwards. BI Governor Warjiyo indicated that inflation will be slightly higher than the central bank’s target range of 2 – 4% this year, but still remains manageable following the fiscal package rolled out to help contain the recent increase in energy and food prices. BI kept its GDP forecast at 4.5% to 5.3% this year, after growing 5.01% in 1Q22 following the reopening of the economy.
- Elsewhere, the People’s Bank of China (“PBOC”) has pledged to increase credit issuances and financial support for key businesses and fields, such as micro, small and medium-sized enterprises, green development, scientific and technological innovation and other key sectors in a bid to stabilise the economy. China’s state council also rolled out more stimulus measures last week to cushion the negative impacts from the covid lockdowns. Notably, the stimulus package included CNY 140b in additional tax rebates, CNY 150b of loans to the civil aviation industry and CNY 300b of railway construction bonds to support its rural highway infrastructure projects.
- On Wednesday, the Reserve Bank of New Zealand (“RBNZ”) raised its official cash rate (“OCR”) by 50 basis points (“bps”) to 2.0%, marking its fifth straight interest rate hike as the central bank aims to reduce the impact of inflation on the economy. Going forward, the central bank projects that the OCR would increase to near 4.0% in the second half of 2023, and would remain there into 2024. RBNZ expects inflation to peak at 7.0% in the June quarter of this year, which is well above its targeted range of 1 – 3% as the central bank now looks to tighten its monetary policy much more aggressively than most expected.
- The Bank of Korea (“BOK”) hiked interest rates for the second consecutive time on Thursday, taking it 25 bps higher to 1.75%. Newly appointed BOK governor Rhee Chang-yong said that the central bank must focus on containing inflation, after revising the country’s inflation rate higher to 4.5% from its previous February forecast of 3.1%. Meanwhile, the central bank has also cut its 2022 GDP forecast from 3% to 2.7% as the economy continues to face headwinds from higher cost pressures and geopolitical tensions.
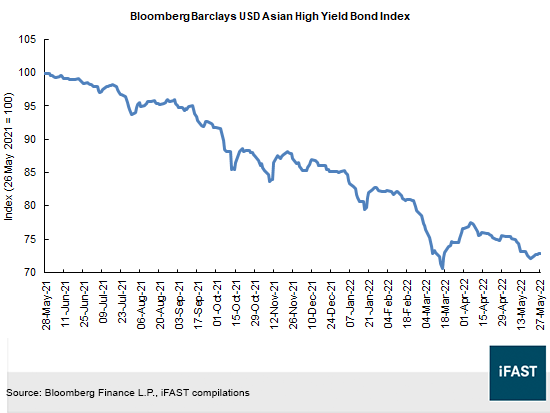
Asian High Yield Bond Index
- The Barclays USD Asia High Yield Bond Index decreased by 0.9% for the week ended 27 May 2022.
- Jinke Property Group said on Tuesday that it will be looking to extend the payment deadline on its CNY 1.25b onshore bond by 1 year as the covid-19 lockdowns and sluggish property sales continue to impact its cash flows and balance sheet position. Under the proposal, the developer will pay 10% of the principal immediately after the extension agreement, with another 5% respectively at the end of July and August. This means that the Group will pay off 20% of the total bond amount in 3 months, and then repay the remaining in subsequent quarters.
- On Friday, Chinese state-backed property developer Greenland Holdings announced that it is seeking to extend the repayment of its USD 488m 6.750% June 2022 bond by one year. The Group mentioned that it will seek approval from bondholders for the extension, where it will pay 10% of the principal amount and interests on the maturity date 25 June 2022, with the remaining amount being paid 1 year later in 2023.S&P Global Ratings downgraded the Group by 2 notches to "B-" with potential for further cuts in the future, as the developer continues to face uncertainty in terms of disposing its assets and generating sufficient internal resources to repay the offshore debt within the next 3 – 6 months. Property sales in April posted a 57% decline from a year ago, and the Group expects sales to fall significantly in May due to the recent spike in covid-19 cases and lockdown restrictions. The Group plans to sell CNY 50b – 70b of assets such as hotels and office towers to shore up its liquidity position.
Interest Rates and Currencies
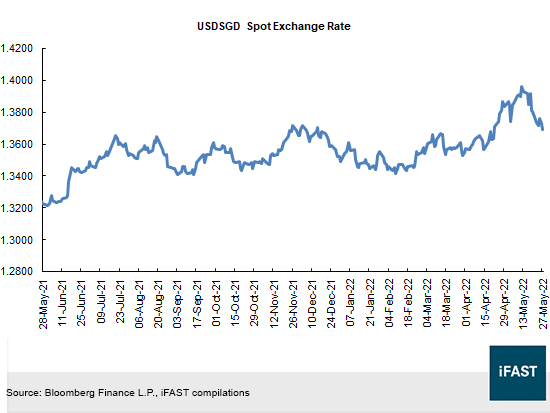
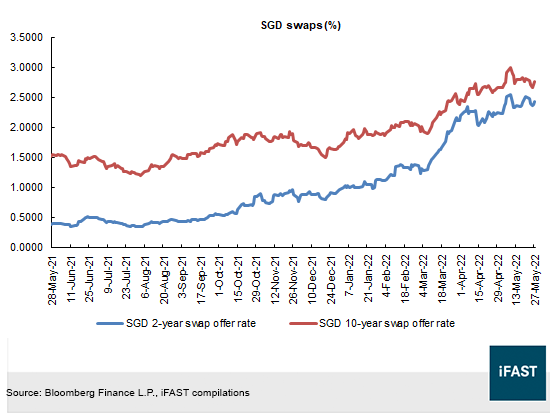
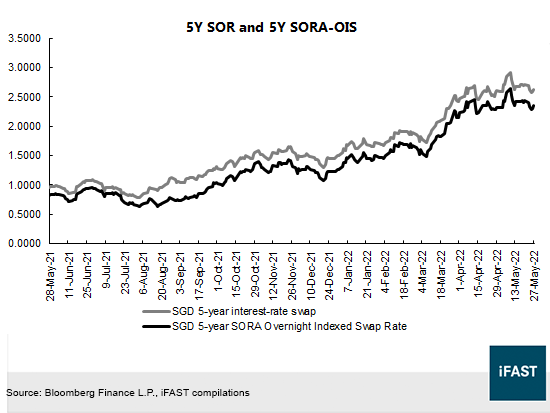
- The US dollar depreciated against the Singapore dollar last week with the USD/SGD currency pair ending at 1.369. The 2-year SGD Swap Offer Rate (“SOR”) decreased by 7 basis points (“bps”) to 2.440% while the 10-year SGD SOR decreased by 5 bps for the week to 2.763%. Meanwhile, the 5-year SOR decreased by 8 bps to 2.635% while the 5-year SORA-OIS decreased by 7 bps to 2.363%.
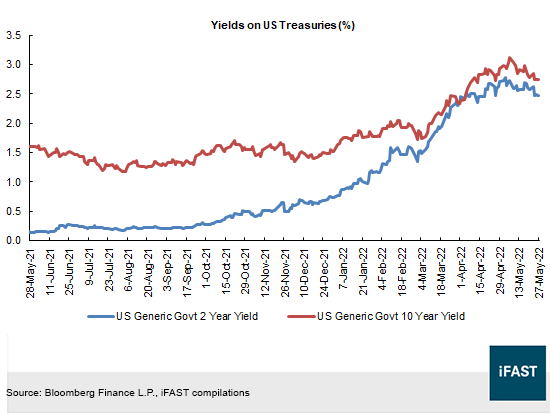
- Last week, the yield of 2-year US Treasuries (“UST”) decreased by 10 bps to 2.476% while the 10-year UST decreased 4 bps to 2.738%. US Treasury yield curve bull-steepened last week as key inflation metric showed possible signs of slowdown in rising consumer prices. The core personal consumption expenditures price index rose 4.9% year-on-year in April, which was in line with market expectations and slight deceleration from the previous month. Market was largely unsurprised by the May FOMC minutes, which showed the agreement among most FOMC members to increase interest rates by 50 bps at subsequent meetings.
Corporate Updates and New Issues
- On Tuesday, Keppel Telecommunications & Transportation Limited (“KT&T”) announced that it will be divesting its 51% stake in Indo-Trans Keppel Logistics Vietnam Co Ltd (“ITKL”) to In Do Trans Logistics Corporation for a cash consideration of ~SGD 8m. The proposed sale is expected to happen in the second quarter of this year, prior to the completion of the divestment of Keppel Logistics Pte Ltd.
- On Tuesday, Keppel Offshore & Marine Ltd (“Keppel O&M”) announced that it secured 2 rig charter contracts worth up to SGD 120m, including the options and modification works by Keppel O&M to prepare the rigs for the operations. The rigs will be provided to an established drilling company in the Middle East, starting from the fourth quarter this year, up to a period of 3 years with an option to extend for 1 additional year.
- On Wednesday, Moody’s affirmed Mapletree Commercial Trust’s (“MCT”) credit rating at Baa1 with a stable outlook. The credit rating agency concluded that MCT’s increased scale and diversification following the merger with Mapletree North Asia Commercial Trust (“MNACT”) will partially offset its higher leverage, which will likely improve over the next 2 years after the recovery of its key retail assets’ operating performances. Meanwhile, Moody’s will continue to review MNACT’s Baa3 rating for upgrade if MCT exhibits willingness to provide extraordinary support after the merger, where MNACT will operate as a sub-trust of MCT.
- Allocation results for Astrea 7 bonds were released on Thursday. Total subscription was more than USD 2b across all 3 classes compared to the USD 755m of bonds offered. The offer of SGD 526m of Class A-1 bonds was nearly 3x over-subscribed with SGD 877m received from retail investors. Meanwhile, Class B bonds was 1.3x over-subscribed with USD 126m received from applicants under its inaugural retail offer. The distribution of placement tranche was well-diversified across accredited investors (40%) and high-quality institutions (60%) such as asset managers, insurance companies, endowments and foundations.
- On Thursday, Wing Tai Holdings announced that its wholly-owned subsidiary, Winville Investment Pte. Ltd., has entered into a contract for the collective purchase of leasehold Lakeside Apartments for a total consideration of ~SGD 273.9m. The site spans 12,456.4 square meters with a plot ratio of 2.1 with well-established amenities such as shopping malls and community healthcare facilities nearby. The Group intends to redevelop the site into a residential development with over 300 units with unobstructed waterfront views of Jurong Lake Gardens.
- On Friday, Metro Holdings announced its FY22 results for the financial year ended 31 March 2022. Net profit after tax fell from SGD 37m in FY21 to SGD 23.7m, primarily due to an impairment loss of SGD 36.3m on co-investments with BentallGreenOak as a result of the challenges faced by the China property sector. Its retail division saw an improvement in net profit after tax from SGD 1.27m of losses in FY21 to SGD 3.84m following the easing of covid-19 restrictions. Despite the fall in net profit after tax, the Group still maintained a strong balance sheet with a net asset of SGD 1.6b. Net gearing ratio is estimated to be ~0.17x, while it also maintains a healthy liquidity position with a current ratio of ~4.1x.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!