Important Events
- On Wednesday, the Bank of Canada maintained its overnight rate at the effective lower bound of 0.25 percent while keeping Bank Rate at 0.5 percent and deposit rate at 0.25 percent. The bank’s quantitative easing (“QE”) program will also be maintained at a pace of CAD 2 billion per week. On Thursday, Tiff Macklem, the Governor of the Bank of Canada, released his remarks for Canada’s economic progress report and said that the central bank of Canada has been gradually reducing the pace of QE since late October and the state of economy recovery is moving closer to a state where QE is no longer necessary, subjected to economic developments. The governor restated that policy interest rate will remain at the lower bound until economic slack is absorbed and the country sustainably achieves their target of 2 percent inflation target. He has also stated that when the Bank of Canada decides to reduce the amount of monetary stimulus, it will first begin by raising the overnight rate. Further monetary policy decisions will depend on the strength of recovery and evolution of inflation.
- On Thursday, the Monetary Policy Committee of Bank Negara Malaysia decided to maintain the Overnight Policy Rate at 1.75 percent. They said that the imposition of nation-wide containment measures in Malaysia dampened the growth momentum for the Malaysian economy. However, the central bank of Malaysia states that moving forward, the easing of containment measures, progress of Malaysia’s vaccination programme and the continued expansion of global demand will support a certain level of growth in the economy going into 2022. However, risks remain tilted towards the downside including delays in the easing of containment measures due to new COVID-19 variants and a weaker-than-expected global growth recovery. Bank Negara Malaysia’s monetary policy continues to be accommodative and fiscal measures will continue to provide support to the economic activity in Malaysia.
- On Thursday, the European Central Bank (“ECB”) maintained interest rate on the main refinancing operations at 0 percent, interest rates on the marginal lending facility at 0.25 percent and the deposit facility at -0.50 percent. The ECB expects key interest rates to remain at their present or lower levels until inflation rate reaches 2 percent. Net purchases under the Asset Purchase Programme (“APP”) will continue at a monthly pace of EUR 20 billion and will continue as long as to support the accommodative impact of its policy rates. For the Pandemic Emergency Purchase Programme (“PEPP”), the ECB will continue net asset purchases with a total envelope of EUR 1,850 billion at least until the end of March 2022. Compared to the previous two quarters, the ECB assessed that net asset purchases can proceed at a moderately lower pace to maintain favourable financing conditions.
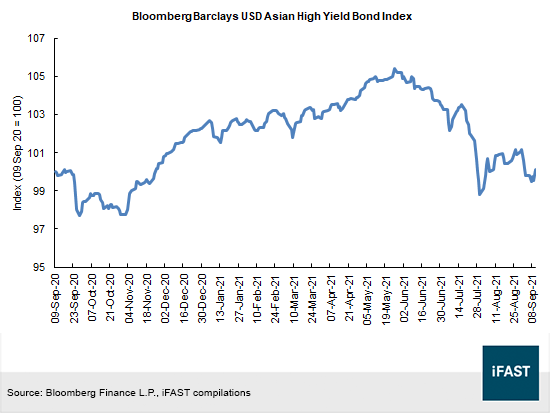
Asian High Yield Bond Index
- The Barclays USD Asia High Yield Bond Index gained 0.30% for the week ending 10 September 2021.
- On Thursday, Jiayuan International was upgraded by Fitch to ‘B+’ from ‘B’. Fitch upgraded Jiayuan International due to the company’s efforts on deleveraging and expansion via organic growth and asset acquisitions.
- On Friday, China Huarong Asset Management and China Huarong International were downgraded by S&P to ‘BBB’ from ‘BBB+’ and subsidiary Huarong Financial Leasing was lowered to ‘BBB-‘ from ‘BBB+’.
- On Friday, Evergrande's dollar bonds rebounded since the regulator, China’s Financial Stability and Development Committee signed off on its proposal to renegotiate payment deadlines with banks and other creditors.
Interest Rates and Currencies
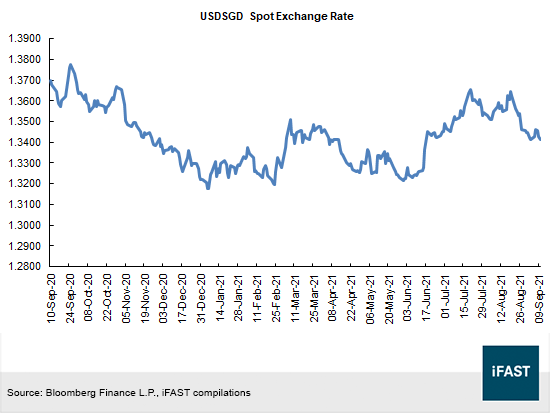
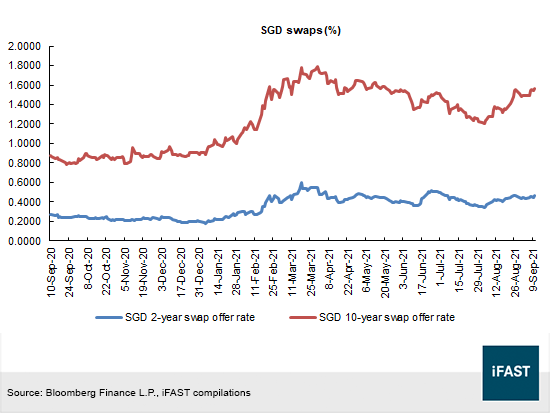
- The US dollar remained flat against the Singapore dollar last week with the USD/SGD currency pair at 1.3415. The 2-year SGD Swap Offer Rate (“SOR”) increased by 3 basis points (“bps”) to 0.4675% while the 10-year SGD SOR increased by 7 bps to 1.5613%.
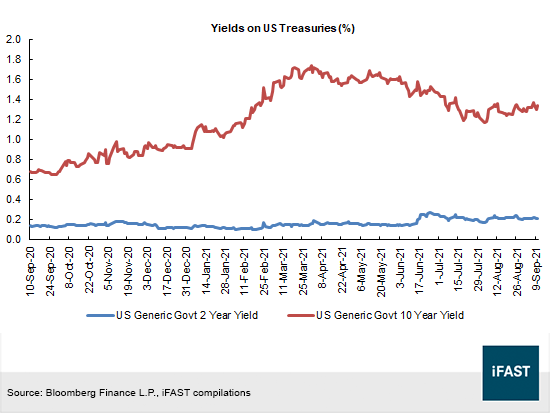
- The yield of 2-year US Treasuries (“UST”) increased by 1 bps to 0.2127% while the 10-year UST yield increased by 1bps to 1.3411%. US initial jobless claims for the week ending September 4 was at 310,000, representing a drop of 35,000 from the previous week. US Producer Price Index rose for the eight consecutive month as prices increased by 0.7% month-on-month in August.
Corporate Updates and New Issues
- On Monday, Starhill Global REIT (“SGREIT”) announced the launch of a 7-year SGD, unsubordinated and unsecured notes at an initial price guidance (“IPG”) of 2.35% under its SGD 2b Multicurrency Debt Issuance Programme dated 3 January 2020. Investors may read our view on the new issue here.
- Last Monday, the National Environment Agency raised SGD 1.6 billion through the issuance of the NEASP 1.670% 15Sep2031 Qsov (SGD) and NEASP 2.500% 15Sep2051 Qsov (SGD). The bonds are the largest SGD green bonds in 2021.
- DBS Group Holdings Ltd announced the launch of the DBSSP 1.194% 15Mar2027 Corp (USD) on Tuesday. With a credit rating of ‘Aa2’/’AA-’ by Moody’s/Fitch, the bonds were priced at an initial price guidance of CT5 + 65bps.
- On Tuesday, Keppel Corporation Limited (“Keppel”) proposed to issue SGD NC3 perpetual notes at an IPG of 3.00%. The notes are first callable on September 2024 and on each distribution payment date thereafter. The first reset date will be on September 2026 and if not redeemed, the notes will reset on September 2026 and every 5 years thereafter to the sum of the 5 year Singapore Overnight Rate Average Overnight Indexed Swaps (“SORA-OIS”) plus initial credit spread plus the step up margin of 100bps. Investors may read our view on the new issue here.
- On Wednesday, Oxley Holdings Limited. (“Oxley”) announced an invitation for the noteholders of the OHLSP 5.700% 31Jan2022 Corp (SGD) to sell a portion of their notes at 100 per cent. of the principal amount of the Notes, together with accrued and unpaid interest on the Notes from (and including) the last preceding interest payment date prior to the Settlement Date to (but excluding) the Settlement Date. Additionally, Oxley also proposed the re-opening of the OHLSP 6.900% 08Jul2024 Corp (SGD). The expiration date of the invitation to existing noteholders to sell is expected to be on 22 September 2021, 12pm while the launch and pricing date of the new notes will be expected to be on 23 September 2021. On a separate note, later in the week, Oxley informed that it has removed Oxley Mosaic Pte. Ltd. off its register.
- On Thursday, Singapore Press Holdings Limited (“SPH”) responded to questions ahead of its extraordinary general meeting (“EGM”) on 10 September 2021. SPH answered questions regarding the proposed restricting of the media business and the proposed scheme and privatisation by Keppel Corporation Limited. A day later, SPH released the results of the EGM and 97.55% of the shareholders voted in favour of the resolution to approve the proposed restructuring, while 97.46% of the shareholders voted in favour of the resolution to approve the proposed conversion and proposed adoption of a new constitution.
- On Friday, the manager of Keppel DC REIT announced that its wholly-owned subsidiary obtained a EUR 20m 5-year loan facility. Under the terms of the facility, a mandatory prepayment of the facility is required if the REIT manager ceases to be a subsidiary of Keppel Corporation Limited.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!