Following our previous 1Q27 Credit Update, Yinson Holdings Berhad has released its 2Q27 results, providing further insights into its financial and credit performance. This update reviews the key developments since our previous assessment.
Previous Article Update: Credit Update 1QFY27: Resilient Contracted Cash Flows Support Yinson's Credit Fundamentals | Bondsupermart
- Company Overview: Yinson is a publicly listed global energy infrastructure company with a market capitalisation of RM7.2 billion as of 2 November 2026. As of 2Q27 (July 2026), approximately 95% of its revenue is generated from its Offshore Production and Marine segment, primarily driven by its Engineering, Procurement, Construction, Installation and Commissioning (EPCIC) activities and Floating Production Storage and Offloading (FPSO) leasing business.
- Proposed Privatisation and Implications for Bondholders: Yinson's proposed privatisation by Yinson Legacy (Lim family-linked vehicle) and MISC, at an indicative offer price of RM2.35 per share, remains under discussion, with the deadline for a firm intention announcement extended to 30 November 2026. There's no impact to existing bonds, there's no impact to existing bonds, as there's no change of control clause/no acceleration clause to be triggered upon privatisation.
- Strong Contract Backlog Supporting Cash Flow: As of 2Q27, Yinson has secured a robust USD19.3 billion contracted revenue backlog from long-term charter contracts with remaining tenures of 20–25 years (Table 1), providing stable and recurring cash flows to support debt servicing and mitigate short-term liquidity risks.
- Robust Contractual Protection Against Early Termination: Yinson's charter contracts incorporate robust early termination compensation mechanisms, as demonstrated by FPSO Allan and PTSC Lam Son, where compensation received covered lost future revenue and, in the latter case, exceeded the outstanding project loan, providing protection against premature contract termination and supporting cash flow stability highlighted in previous article: Credit Update: Yinson Strong FPSO Growth with Capital Raise Amid Credit Strains | Bondsupermart
- Yinson Secures US$600 Million Additional Backlog: On 5 October 2026, Yinson secured an additional US$600 million (RM2.5 billion) in firm contract backlog through a Ghana FPSO upgrade and a four-year contract extension to 2036, strengthening long-term revenue visibility and supporting its US$19 billion order book.
Table 1: Yinson’s Robust Order Book
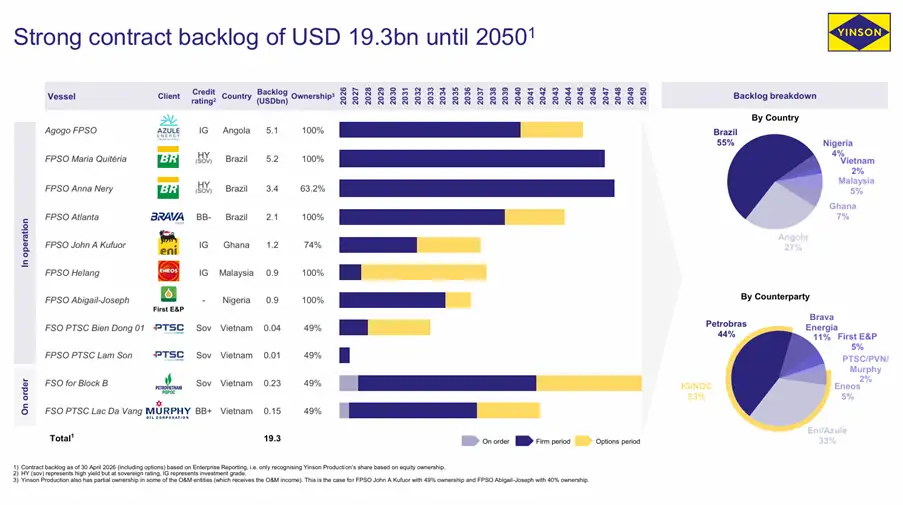
Source: Yinson Holdings Berhad, iFAST compilations. Data as of 30 June 2026.
- Transition to Operational Phase: In 2Q27, revenue declined 16.7% YoY to RM1.14 billion from RM1.36 billion, primarily due to the absence of EPCIC revenue following the completion of the Agogo FPSO and the commencement of its charter on 12 August 2025 (3QFY26). However, revenue increased 8.3% QoQ from RM1.05 billion in 1Q27 to RM1.14 billion in 2Q27, driven by annual charter rate escalations on the finance lease for FPSO Maria Quitéria and a higher number of operating days.
- Improving Operating Profit Margin: Despite lower revenue, the operating profit margin increased from 47% to 51% in 2Q27, mainly driven by contributions from the Agogo FPSO's operations, which transitioned from EPCIC to higher-margin FPSO leasing. This provides more stable recurring earnings through long-term charter contracts.
- Low Downtime Supports Earnings Stability: Yinson’s FPSO fleet maintains high operational reliability, with a 5-year average technical uptime of 99.6%, translating into minimal downtime and strong asset availability. This supports stable recurring leasing income under long-term charter contracts, while fleet commercial performance consistently remained above the initial target at 102.2% in 1QFY27, reflecting additional upside from performance-based incentives.
- Highly Leveraged with Low Liquidity, but Showing Moderate Improvement: Adjusted net gearing improved to 157% in 2QFY27 from 211% in FY26 (January 2026), while net debt-to-EBITDA decreased slightly to 5.2 times from 5.4 times, mainly due to the repayment of RM2.2 billion in loans and borrowings. However, interest coverage and cash-to-short-term debt remained relatively low at 1.5 times and 1.6 times, respectively, in 2QFY27. Nevertheless, Yinson’s strong order book, with an order book-to-net debt ratio of 5.5 times, provides support for its debt servicing capacity.
- FPSOs Remain Resilient: Despite oil price volatility, FPSO projects are typically sanctioned only after crude oil is ready to be extracted. Once production begins, operators generally continue extracting oil to maximise returns on their investments, supporting stable demand for FPSOs under long-term contracts.
- Upcoming Sukuk Maturity: We maintain a positive view on YNSMK 5.800% 07Dec2026 Corp (MYR) (Table 2), as we believe Yinson has sufficient capacity to redeem the sukuk, supported by its existing cash balance of RM4.2 billion as of 2QFY27.
- Overall: Yinson’s credit fundamentals remain supported by its strong contracted cash flows and sizeable order backlog, despite elevated leverage and relatively low liquidity. The transition towards the operational phase is improving earnings stability, while high FPSO uptime supports recurring cash flows. Investors may consider holding Yinson’s bonds, supported by its resilient contracted cash flows and improving credit fundamentals, although leverage remains a key credit risk.
- Recommendation: New investors may consider YNSMK 5.000% 12Dec2030 Corp (MYR), which offers a yield to maturity (YTM) of 5.0%, with a minimum initial and subsequent investment amount of RM250,000.
Table 2: Yinson’s Existing Bonds
|
Bond |
Years to next call/ Maturity |
Yield to next call/ Maturity |
Outstanding Amount (RM million) |
Credit Rating (RAM) |
|
-/ 1M |
-/4.8% |
1,000 |
A1 |
|
|
1Y/- |
5.0%/7.7% |
250 |
A3 |
|
|
1Y 1M/- |
5.0%/7.8% |
110 |
A3 |
|
|
2Y 4M/- |
5.3%/8.0% |
640 |
A3 |
|
|
-/4Y 1M |
-/5.0% |
425 |
A1 |
|
|
-/6Y 1M |
-/5.2% |
750 |
A1 |
|
|
Source: Bondsupermart, iFAST compilation. Data as of 30 October 2026 |
||||