-
SATS’ Food Solutions and Gateway Services segments are expected to emerge stronger from the recovery of international air travel.
We appreciate the Group’s plans to expand its non-travel related businesses to support and diversify its revenue stream despite the expected pick-up of the aviation sector.
-
Despite increased borrowings during the pandemic, SATS still maintains a strong credit profile with a low net debt-to-equity ratio of 0.03x as of 30 September 2021
-
Its liquidity position remains strong with cash and short-term deposits more than sufficient to cover its total current liabilities.
-
The SATSSP 2.880% 31Mar2025 Corp (SGD) is currently yielding at ~3.15% with 2.9 years left to maturity, which provides a short duration option with comparable yields relative to recent bond issues by other Temasek linked entities.
-
We think that the 2025 bond also offers an attractive alternative to comparable bonds of Singapore Airlines Group if investors are looking for a reopening trade.
Company Background
Founded in 1972, SATS Ltd (“SATS”) is Asia’s leading provider of gateway services and food solutions with the largest market share of Changi Airport’s food catering and ground handling services. The Group is located in over 55 locations and 13 countries across Asia Pacific, Middle East and the UK as of 2021.
The Group mainly operates through 2 segments: 1) Food Solutions and 2) Gateway Services. Its Food Solutions segment includes aviation, commercial and institutional catering, food production and distribution, as well as linen and laundry. SATS Food Solutions business has also ventured into other industries such as hospitality, healthcare and logistics in order to diversify its non-travel related revenue streams amidst the global pandemic. Meanwhile, its Gateway Services segment provides a wide array of services such as air cargo, low-cost carrier handling, cruise terminal services, as well as passenger and security services.
Besides having ~80% market share of Changi Airport’s catering and ground handling business, SATS also has a strong presence at a number of regional hub airports including Japan, Malaysia, Hong Kong, India and Taiwan, mostly through its subsidiaries and associates/joint ventures with domestic partners. Nonetheless, Singapore still remains as the Group’s main revenue driver, contributing 85.8% of consolidated revenues for the six months ended 30 September 2021 (“1H FY21/22”), followed by Japan (6.5%) and Others (7.6%).
Financial Highlights
For 1H FY21/22, total revenue increased by 29.3% year-on-year (“YoY”) on the back of growth in cargo, non-travel food and security services. The Group also managed to reverse an operating loss position of SGD 36m in 1H FY20/21 to achieve an operating profit of SGD 4m in 1H FY21/22 despite the rise in group expenditures. Its share of results from associates and joint ventures also improved notably from a loss of SGD 44.2m to a profit of SGD 0.9m, as the gradual recovery from the Covid-19 pandemic has led to an improvement in most of its aviation related associates and joint ventures.
Figure 1: Total Revenue Breakdown for First Six Months Ended 30 September
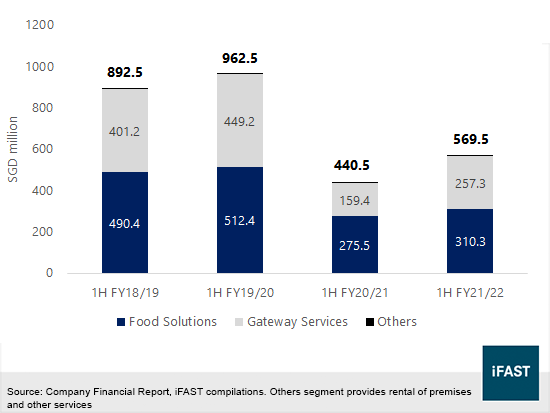
Food Solutions revenue increased 12.6% YoY despite the lower aviation growth, as SATS mainly expanded its non-travel food services including integrated protein supply chains, SATS brand products and tiered production to diversify its revenue stream. For the six months ended 30 September 2021, SATS’ non-travel food services largely dominated ~71% of this segment’s revenue. The Group has also been extending its Food Solutions footprint globally by distributing an expanded portfolio of food services and products in key overseas markets. For 1H FY21/22, Food Solutions takes up ~54.5% of total revenue, and going forward, SATS hopes to grow its Food Solutions segment to ~60% of total revenue by FY25.
Meanwhile, its Gateway Services revenue improved substantially by 61.4% YoY for 1H FY21/22, driven by stable cargo growth, resumption of ship calls, increased flights and security services. Among its Gateway Services segment, ~34% of revenue is driven by ground handling services, while cargo and security services also take up a similar revenue proportion of 32% and 28% respectively. Operating profit for this segment improved by SGD 29.5m from a year ago, while its share of results from associates and joint ventures also turned positive as international travel improved due to the easing of border restrictions.
Business Outlook
Operating segments to benefit from the recovery of international air travel
The Singapore government recently announced that fully vaccinated travelers will be able to enter Singapore without having to quarantine or take on-arrival covid tests from April, marking a major step forward in reopening its borders. For the three months ended 31 December 2021, SATS’ Gateway Services segment has already shown encouraging signs of recovery, as total flights handled for the Group was 30k (+109.8% quarter-on-quarter) while total passengers handled was 3.6m (+300% quarter-on-quarter). With a further easing of border restrictions, we can expect passenger traffic to improve further as a result of renewed travel demand.
Based on recent operating statistics from Singapore Airlines Group (“SIA”), passenger capacity has already reached 51% of pre-covid levels in March, and it expects passenger capacity to improve even further to ~61% by May this year. Notably, passenger volume at Changi Airport also more than doubled in April from the previous month, approaching 40% of pre-covid levels. With a dominant market share of Changi Airport’s inflight catering and gateway services as well as a strong presence at regional hub airports, we believe that the air travel recovery will benefit both of its Food Solutions and Gateway Services segment moving forward.
Air cargo remains a bright spot for Gateway Services as eCommerce grows
eCommerce demand has surged during the pandemic and will remain robust going forward as consumers shift towards convenient online shopping while brick-and-mortar stores in some countries will remain shut as a result of stringent restrictions. SATS’ digitalized cargo facilities in 10 countries across APAC and the Middle East offer strategic airside locations that will help position its air cargo segment to capture the eCommerce growth.
The Group has also been actively pursuing eCommerce opportunities through its joint ventures. For instance, one of its JVs, Beijing CAH SATS Aviation Services, has secured contracts with China’s top 2 domestic freighter service providers for eCommerce and express deliveries. Meanwhile, the Group also bought an additional 16.4% stake in its cargo associate, Asia Airfreight Terminal Co. Ltd (“AAT”) last year, making it a subsidiary post-acquisition in hopes of boosting its cross-border eCommerce logistics business in the Greater Bay area. As such, we believe that SATS’ recent acquisition and deepened relationships with major eCommerce players will continue to be accretive towards its air cargo business.
Non-travel related businesses continue to provide support and diversification
For 1H FY21/22, non-travel related revenue grew by 24.8% YoY to SGD 265.6m, contributing to ~46.6% of total revenues for the period. We expect its non-travel market segments to remain as a source of support and diversification for its operating revenue for the next few years as the aviation sector gradually normalizes. Based on estimates from the International Air Transport Association (“IATA”), overall air passenger will fully reach its pre-covid levels in 2024, and the Group expects non-travel segments to continue contributing ~35% of total revenues by 2025 despite the projected full recovery of the aviation sector.
Going forward, SATS will look to expand its non-travel related businesses with recent investments in central kitchens and new corporate venture models such as FoodFlix and Twyst. FoodFlix is a brand accelerator program that allows SATS to partner with local hawkers and F&B brands to enrich its Food Solutions segment and product offerings. Meanwhile, Twyst is a new F&B concept that serves freshly cooked options from its chef’s signatures menu and customizable food offerings for consumers. Therefore, SATS hopes to scale its innovation capabilities and develop local ventures through continued capital investments over the next few years to grow its non-travel related revenue streams.
Credit Discussion
Table 1: Credit metrics comparison as at 30 September 2021
|
Company |
Current Ratio |
Net Gearing |
LTM EBITDA Coverage |
Total Debt/Total Asset |
Net Debt/LTM EBITDA |
|
SATS Ltd |
2.59 |
0.03 |
10.03 |
24.85% |
0.32 |
|
Singapore Airlines |
2.72 |
0.12 |
2.03 |
33.96% |
4.10 |
|
Changi Airport Group* |
1.56 |
0.19 |
0.56 |
19.34% |
7.46 |
|
Source: Company Financial Reports, iFAST estimates *As at 31 March 2021 |
|||||
In terms of SATS’ credit profile, the Group still maintains a strong financial position despite the pandemic headwinds. As of 2021, SATS is 40% owned by Temasek Holdings. We have selected SIA and Changi Airport Group for its peer comparison, because these are government linked entities and they will likely have similar benefits from the recovery of international travel and expansion of the Vaccinated Travel Lanes (“VTL”).
Among the 3 companies, SATS has the lowest net gearing ratio while its interest servicing ability is also the strongest with the highest EBITDA coverage ratio. We attribute this largely to the resilience of its operating segments, as SATS managed to diversify its revenue streams towards non-travel food services such as bakehouses and central kitchens and cater them towards local institutions such as hospitals and government agencies. Meanwhile, SIA and Changi Airport Group still largely depend on international air travel for their source of income.
As at 30 September 2021, SATS has SGD 685.5m of cash and short-term deposits, which is more than sufficient to cover its short-term loans of SGD 55.1m and current lease liabilities of SGD 18.5m. We appreciate its conservative and prudent approach in terms of managing its liquidity, as it has shored up its cash position during the pandemic and has long maintained a healthy cash-to-short-term borrowings ratio even before the pandemic.
The Group also has SGD 545.1m of available short-term loan facilities from revolving credit facilities from commercial banks as at 31 March 2021. As such, SATS has a strong liquidity position to meet its short-term liabilities. Despite the increase in borrowings during the pandemic, SATS still maintains a manageable gross debt-to-equity ratio of 0.47x as at 30 September 2021 (31 March 2021: 0.56x), while net debt-to-equity ratio (after deducting cash and short-term deposits) stood at ~0.03x. While its healthy EBITDA coverage ratio is strongly supported by government grants and reliefs, we can expect the air travel recovery to offset the decline in government support moving forward.
Relative Valuation
Table 2: Relative Valuation of Comparable Bonds
|
Bond |
Issue Date |
Maturity Date |
Remaining Years to Maturity |
Ask YTM |
|
SIASP 3.160% 25Oct2023 Corp (SGD) |
25Oct2018 |
25Oct2023 |
1.47 |
2.72% |
|
SIASP 3.030% 28Mar2024 Corp (SGD) |
28Mar2019 |
28Mar2024 |
1.89 |
2.75% |
|
SIASP 3.750% 08Apr2024 Corp (SGD) |
08Apr2014 |
08Apr2024 |
1.92 |
2.83% |
|
SATSSP 2.880% 31Mar2025 Corp (SGD) |
31Mar2020 |
31Mar2025 |
2.90 |
3.15% |
|
SIASP 3.035% 11Apr2025 Corp (SGD) |
11 Apr 2017 |
11 Apr 2025 |
2.93 |
3.05% |
|
Source: Bloomberg Finance L.P., iFAST compilations. Figures as at 5 May 2022 |
||||
In terms of relative valuation, we think that the SATSSP 2.880% 31Mar2025 Corp (SGD) is more attractive than other comparable bonds of SIA and Changi Airport Group. As at 5 May 2022, the 2025 bond is yielding at ~3.15% with approximately 2.9 years left to maturity, thus, offering investors with a short duration and stable income option to consider.
Referring to Table 2, if we were to compare the SATSSP 2.880% 31Mar2025 Corp (SGD) to other short duration bonds of 3 years or less in terms of their time to maturity, we find that the 2025 bond offers the highest yield compared to other SIA bonds with roughly 32 to 43 basis points (“bps”) of yield pickup over SIA’s 2023 and 2024 notes. It is also worth noting that SATS has a slightly stronger credit profile compared to SIA as at 30 September 2021 (Table 1), largely due to its operational resilience as a result of the Group’s diversification towards non-travel businesses and lower dependence on international air travel.
Other Temasek linked entities such as Singapore Post Limited (~22% Temasek deemed ownership through Singtel), CapitaLand Investments Limited (~52% Temasek ownership) and Ascendas REIT (~21% Temasek ownership) recently priced bonds that are trading at similar yields compared to the SATSSP 2.880% bond despite having a longer remaining tenor. Notably, the SPOST 3.230% 29Mar2027 Corp (SGD), CLIVSG 3.330% 12Apr2027 Corp (SGD) and AREIT 3.468% 19Apr2029 Corp (SGD) are yielding approximately 3.18%, 3.25% and 3.35% respectively as at 5 May 2022. Hence, the SATSSP 2.880% bond offers comparable yields to recent issues by Temasek linked companies despite having a shorter time to maturity.
Conclusion
Following the recovery of aviation businesses, SATS’ travel revenue is expected to improve further from the reopening of borders and easing of travel restrictions. Despite that, SATS is still looking to expand its non-travel business segments through capital investments so as to diversify its revenue base moving forward. The Group maintains a strong credit profile in terms of its liquidity, leverage and interest coverage based on its 1H FY21/22 results. The SATSSP 2.880% 31Mar2025 Corp (SGD) offers investors with a decent yield of ~3.15% with ~2.9 years left to maturity, and we think it is more attractive relative to other comparable bonds and recent issues priced by Temasek linked entities. Hence, investors who are looking for short duration and stable income options may consider the SATSSP 2.880% 31Mar2025 Corp (SGD).
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!