Important Events
The Monetary Authority of Singapore (“MAS”) has recently announced it will reopen its existing 50-Year Green SGS (Infrastructure) Bonds (“50y SGS”), at a final price guidance (“FPG”) of 3.04%. The 50y SGS also has a fixed coupon of 3.00% p.a., payable semi-annually (1 Feb and 1 Aug each year) in arrears.
This 50y SGS was issued by the Government of Singapore, which has the highest issuer rating at Moody’s (Aaa), S&P (AAA), and Fitch (AAA). Its inaugural launch was held last year, and it matures on 1 August 2072, giving it a remaining tenor of just under 49 years. The total offering size will be between SGD 2.3b and SGD 2.8b, with an issue date of 4 September 2023. The proceeds of the 50y SGS will be used to finance expenditures in support of the Singapore Green Plan 2030, including the Jurong Region Line and Cross Island Line (which are upcoming electric rail systems in Singapore).
This reopening gives investors another opportunity to purchase the 2072 Green SGS after its initial launch last year. The FPG of 3.04% is just slightly higher than the latest yield on the existing 50y SGS already trading on the SGX (about 3.00%) (Chart 1).
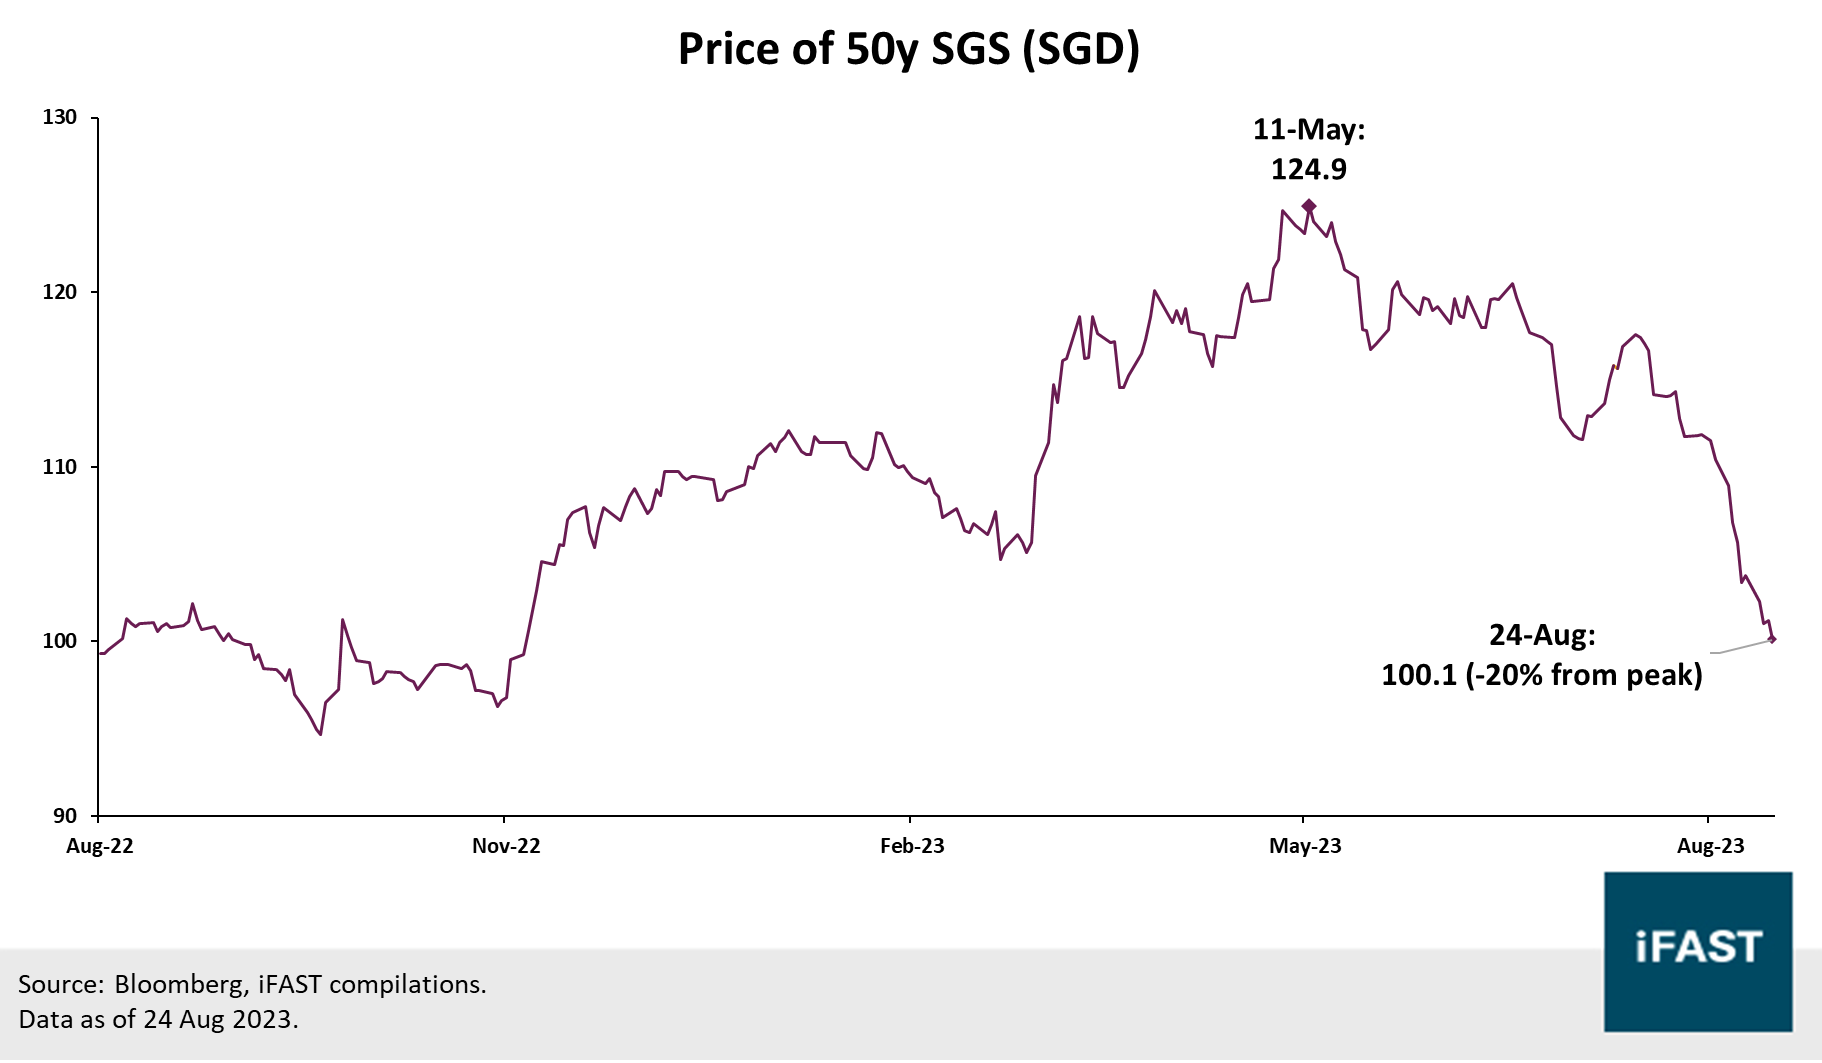
We note that this 50y SGS has a very long maturity and consequently duration (its modified duration is at about 25.5 years), which has contributed to the considerable movement in prices in the 1 year since it was initially issued (Chart 2). We observe that the bond price recently hit a peak of about SGD 125 in mid-May this year, though the bond price has subsequently fallen about -20% from this peak so far, now trading at just above par (SGD 100.1). This means that the 50y SGS now looks considerably more attractively priced now compared to a few months ago.
Investors should be mindful of the effects of the broader interest rate environment when considering this bond. Its relatively long duration of 25.5 years means that broad decreases in interest rates and yields could result in bond prices heading higher, but similarly broad increases in interest rates and yields could result in further sharp declines in these 50y SGS prices.
We nonetheless highlight these bonds are of extremely low risk. The top credit rating enjoyed by the Singapore Government is a rare feat achieved by other sovereigns, and it is no wonder that they are considered to be of very strong credit-worthiness. This means that investors looking for a regular income stream can relatively confidently expect to receive the 3.00% p.a. coupon, with a very low risk of default over the next 50 years.
Overall, we think that these 50y SGS could be of interest to investors looking for an extremely low-risk investment, which comes with a regular income stream through its 3.00% p.a. coupon. However, we reiterate that these bonds come with much higher duration risks compared to shorter-tenor bonds by the Singapore Government (e.g. SG T-Bills), and investors should be willing to withstand the increased price volatility that comes with these bonds. We think these bonds may therefore be most suitable for investors with a very long-term horizon.
Chart 1: Yields of 50y SGS have climbed recently to 3.00%
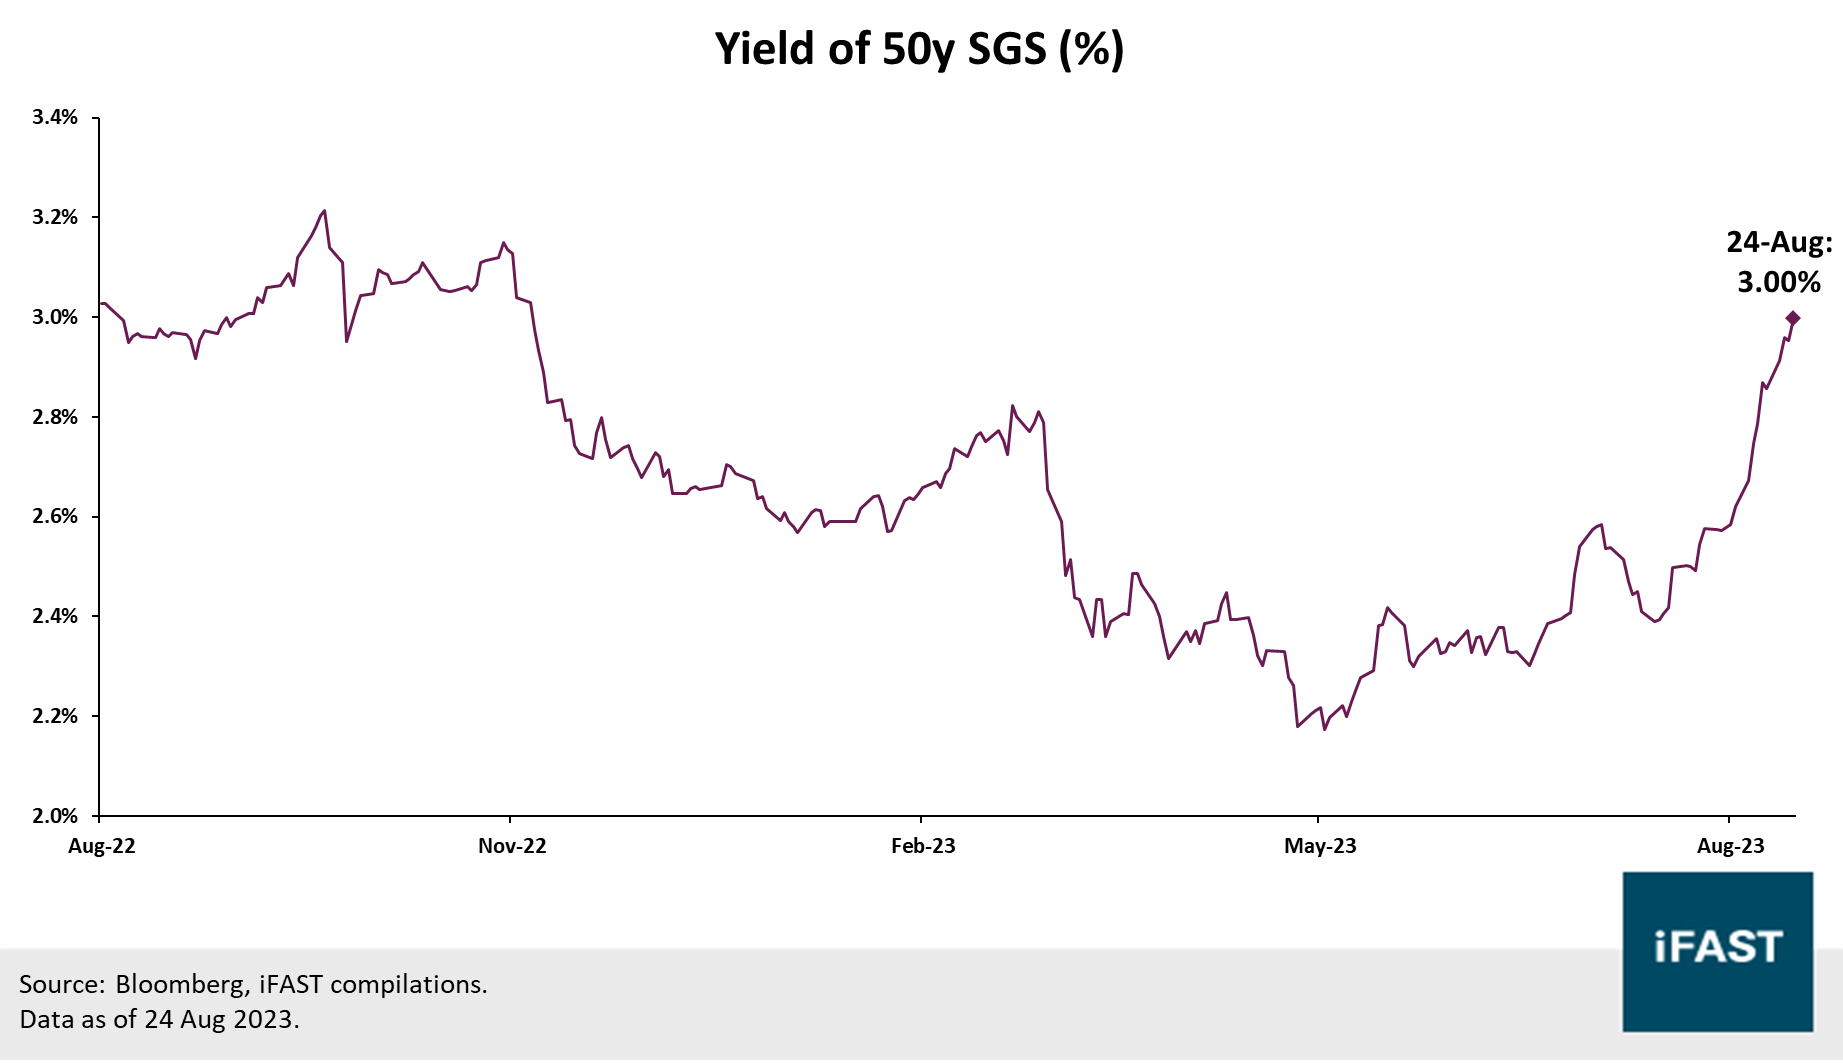
Chart 2: Prices of 50y SGS have fallen alongside the increase in yields, by about 20%
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!