Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
- NagaCorp suffered a total loss of USD 77.23m in 1H21 due to Cambodia’s lockdown.
- We expect earnings to rebound as Cambodia eases restrictions by October and potentially allow vaccinated tourists into the country.
- The group also has sufficient liquidity to tide through the lockdown in 3Q21.
- At a YTM of 7% and same credit rating (‘B1’) as its peers, the 2024 bonds look attractive.
Since our previous article on NagaCorp Ltd. (“Naga”), its 2024 bond has fallen by about 2.35% in price. The company also released its 1H21 results, making a loss of USD 77.23m due to Cambodia’s lockdown. However, domestic and overseas restrictions are likely to ease soon, which is good news for Naga.
(Previous article: Consider investing in the only hotel-casino in Phnom Penh)
1H21 operating results
Naga performed roughly in line as our worst-case projections with operating losses at USD 43.86m for the six months ended 30 Jun 2021 (“1H21”). After deducting for finance costs and income tax, total loss for the period totalled to USD 77.23m. Cash and cash equivalents decreased to USD 253.16m. However, this does not include for the 2020 dividend payment of USD 81.68m, which was paid in July 2021. After including for the dividend payment, cash balances will decline to USD 171.49m.
We expect revenue to improve in 4Q21 as Cambodia’s Ministry of Tourism (“MOT”) is expected to revive international tourism then by inviting fully vaccinated international visitors from low-risk countries to visit Cambodia. However, the company will continue to suffer losses as the suspension of certain business activities, including casinos, was extended until 23 September. Table 1 shows our forecast for operating results in 2H21.
Table 1: Earnings estimates for 2H21
|
USD ‘000 |
|
|
2H21 Profit from operations |
63000 |
|
Losses from stoppage of operations from July - September |
-23760 |
|
2H21 Financing costs |
-15000 |
|
2H21 Tax expenses |
-12000 |
|
Profit for 2H21 |
12240 |
|
Profit for the year |
-64990 |
Source: Company, iFAST estimates
Liquidity profile
Naga’s liquidity profile is adequate as its only debt is from the NAGACL 7.950% 06Jul2024 Corp (USD) bonds which expires in July 2024 with an outstanding amount of USD 550m. It should not have any problems meeting its trade payables too, as it has a sufficient cash position and revenues from its account payables.
After deducting for 2020 dividends and shortfall in trade payables, cash balance will decrease to about ~USD 130m. As they do not have large sums of maturing liabilities or debt, their liquidity seems ample. The cash balances may be used for unforeseen circumstances regarding their construction of Naga 3 and the casino in Vladivostok, Russia.
Table 2: Naga’s 1H21 current assets and liabilities
|
USD ‘000 |
|
|
Current assets |
|
|
Trade and other receivables |
105015 |
|
Restricted bank balance, fixed deposits and other funds |
22213 |
|
Cash and cash equivalents |
253163 |
|
Consumables |
2285 |
|
Total current assets |
382676 |
|
Current liabilities |
|
|
Trade and other payables |
146752 |
|
Dividend payable |
81677 |
|
Contract liabilities |
8577 |
|
Lease liabilities |
9807 |
|
Current tax liability |
10347 |
|
Total current liabilities |
257160 |
Relative valuation
In our article in June 2021, we compared Naga to MGM China, Genting Malaysia, Studio City and Wynn Macau, and now, Naga has also suffered the same fate as them. However, its credit ratios remained stellar although adjusted EBIT/interest expense fell to 0.81x for 1H21.
Naga recorded intangible assets of USD 66.56m as at 30 June 2021 (31 December 2020: USD 67.91m). The company calculated this asset as the the casino license premium and the extended exclusivity of a casino license for the period to the end of 2045 with cost of USD 123m and accumulated amortisation of USD 56.45m.
Table 3: Credit ratios of casino operators (as of June 2021 unless stated otherwise)
|
Total debt/ total assets |
Net debt/ |
Net debt/ equity |
|
|
NagaCorp Ltd* |
~23.5% |
~18.4% |
~26.7% |
|
Wynn Macau Ltd^ |
95.8% |
93.3% |
|
|
Studio City Finance Ltd |
61.9% |
54.6% |
141.6% |
|
MGM China Holdings Ltd |
79.6% |
77.6% |
621.3% |
|
Genting Malaysia Bhd |
45.5% |
34.8% |
66.2% |
Source: Bloomberg Finance L.P., iFAST compilations
* Naga’s numbers based on our forecasts for 2H21.
^Based on 2020 numbers.
Figure 1: Ask yield to maturity for bonds of casino operators
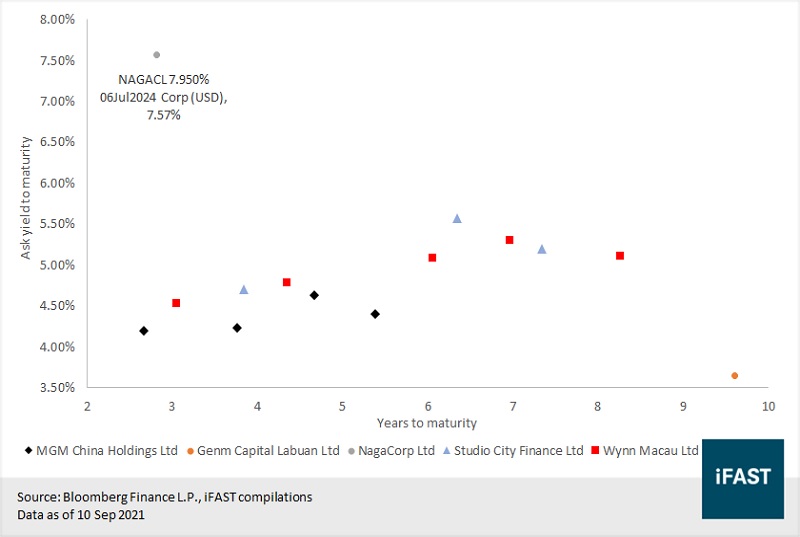
Despite Naga’s high yields, it has the same credit ratings (‘B1’) by Moody’s as the WYNMAC 4.875% 01Oct2024 Corp (USD) and the STCITY 6.000% 15Jul2025 Corp (USD).
A possible reason why Naga bonds have much higher yields could be a lack of deep capital markets in Cambodia. The Cambodian government does not have any instruments for domestic or international borrowings from the capital market, and instead relies on concessional loans for financing new debt. However, the government is currently working on its ability to issue bonds in Cambodian and foreign currency locally or abroad.
Furthermore, Naga is the only company in Cambodia that has publicly-listed USD debt. Thus, the lack of instruments to price its risks efficiently may have led to higher yields for Naga bonds. Naga’s revenues are also already based in USD, thus removing the currency risk a typical company in Cambodia would face.
Although Naga’s bond prices have fallen, we remain positive on their bonds. Additionally, according to Naga, 99.22% of Phnom Penh’s adult population are fully vaccinated. Thus, there is a high chance that NagaWorld will be re-opening soon. Together with the plan to re-open the economy to vaccinated visitors, Naga’s revenue has a high chance of rebounding strongly in 2H21.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!