Highlights:
-
Anton Oilfield Services is an oilfield services company, providing drilling technology, completion products and technology, downhole technology and drilling tool services in the PRC, Iraq, Africa and Southeast Asia, etc. However, the turbulence in the Middle East should not have a significant impact on Anton.
The oilfield services industry is the beneficiary of high oil prices. The oilfield service industry is poised for a performance explosion, with oilfield service orders turning into massive cash inflows. The solvency of oilfield services companies is increasing sharply.
Anton’s operating and cash flow performances are decent. The increase in orders and strong cash flows are the fundamentals of debt repayment. The company intends to spin-off and list its subsidiary, T-ALL Inspection Group, in China's onshore market, which is the potential liquidity source of Anton. The company could repay all the debts with its one-year cash flow, also considering its cash position. Its leverage level is low, with strong repayment ability.
Investors could consider Anton’s January 2025 bond, ANTOIL 8.750% 26Jan2025 Corp (USD), with a net yield to maturity of around 21% and a potential total return of up to 24%. The Anton bond is probably the only choice for an ultra-high yield with a manageable credit risk in the oil and gas sector.
About a year ago, we published an article talking about the credit profile of Anton Oilfield Services ("Anton" hereafter) and pointed out its 2025 bond could be a high yield opportunity. Now, the bond price has increased to over 40% from a year ago, with a total return of more than 50% if counting the coupon received in the year. Is the bond still a good investment opportunity?
In this article, we follow up on Anton’s operating and credit conditions, as well as the investment value of the bond. As for the oil and gas industry outlook, investors could refer to our views, Unravelling the Investment Logics of Oil Bonds, in the early this year. Most of the investment theses still hold true today.
(In this article, “Oil Companies” refers to the oil producers and “Oilfield Services Companies” refers to companies providing exploration and drilling services to oil companies)
Turbulence in the Middle East Should Not Have Significant Impact on Anton's Financials
Anton Oilfield Services is an oilfield services company, providing drilling technology, completion products and technology, downhole technology and drilling tool services in different markets, including the PRC, Iraq, Africa and Southeast Asia, etc. The major customers are oil producers (oil companies), including the Chinese stated-owned companies, CNOOC and PetroChina, and Basra Oil Company, an Iraqi stated-owned enterprise.
The counterparty risk should be low since Anton’s clients are medium and large oil companies, rather than individuals or retail customers. The client base is more stable.
During the War in Iraq (from 2014 onwards), Anton continued to operate normally and generate revenues from the Iraq market. Given that the oil industry is very significant to the Iraqi government (with the revenues from the oil industry accounting for around 85% of its fiscal expenditure), the Iraqi government is willing to put more resources in this industry, including protecting the interests of its business partners and ensuring the oil exploration is not affected by the war.
The recent Israeli-Hamas war (or Israeli-Palestinian conflict) should have limited impact on Anton's operations. The war situation does not extend beyond the two countries and neither of them is an oil production country. Even if the war extends to Iran and involve other neighboring countries like Iraq, the Iraqi government will still need to extract oil through state-owned enterprises, so Anton could be able to continue to provide services and generate revenue. Therefore, we believe that the turbulence in the Middle East should not have significant impact on Anton's financials.
Oilfield Services Companies are Beneficiaries under High Oil Price Environment; Poised for Performance Explosion
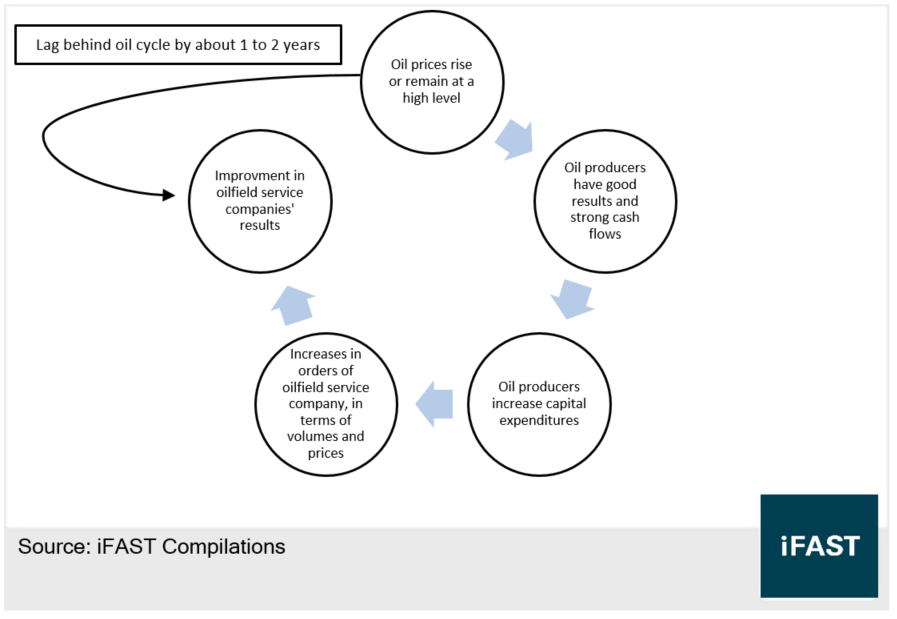
As shown in Chart 1, oilfield services industry usually lags behind the uptrend oil cycle by around one to two years. The oilfield services industry is the mid-to-late stage beneficiary of the high oil price cycle.
Chart 1: Relationship between Oil Price, Oil Producers and Oilfield Service Companies
Since July 2021, WTI oil prices are above $70, a high level, for a while. The current WTI oil prices are even up to $85. There is no significant evidence showing the upward trend of oil cycle could reverse in the short term.
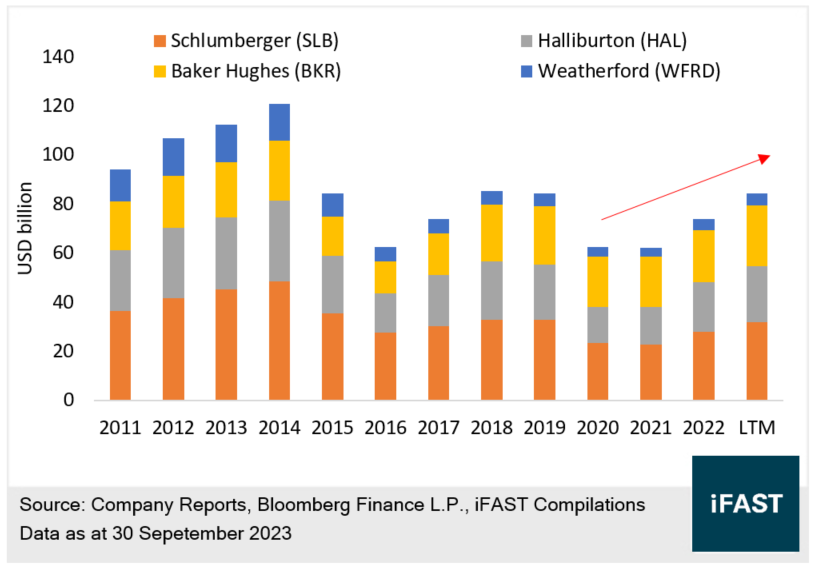
Meanwhile, the oilfield services industry is gradually recovering. As can be seen in Chart 2, the total revenues of the world's four largest oilfield services companies (with a total market share of more than 50%) gradually recovered from the bottom and were back to 2019 levels. As the order books of oilfield services companies continuously increase, and the oil companies gradually but restrainedly increase their capital expenditures, we believe that the revenues of oilfield services companies should have moderate growth in the short- to medium-term. The oilfield services companies are the indirect beneficiaries of the high oil price environment.
Chart 2: Revenues of the Four Largest Oilfield Services Companies
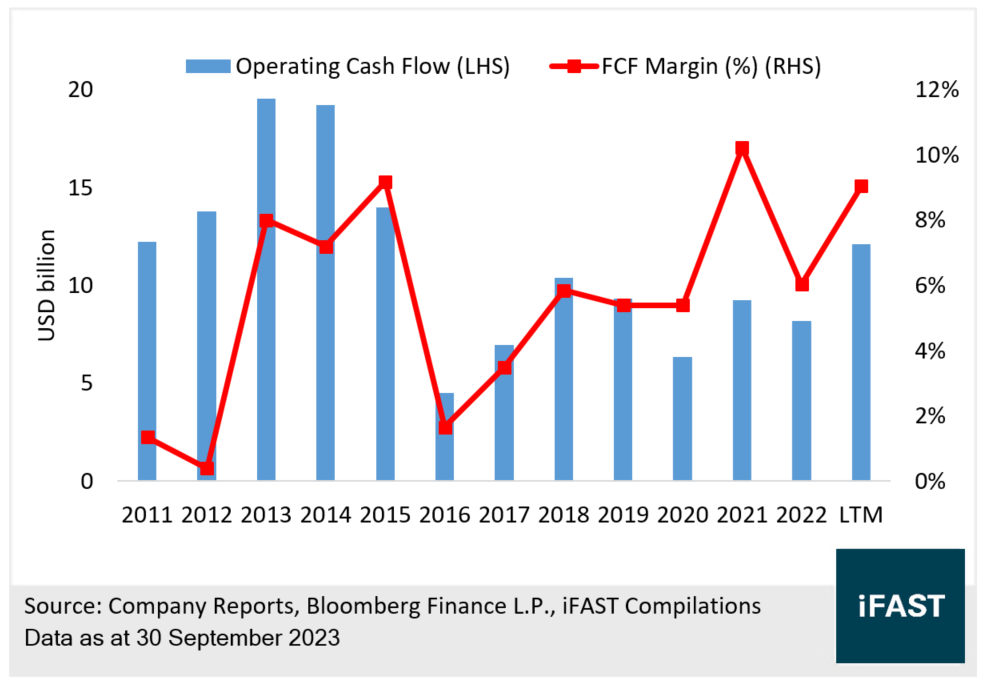
As shown in Chart 3, the operating cash flows of the four largest oilfield services companies increased to the level of over USD 10 billion, which is the highest since 2016. Meanwhile, the free cash flow margin (free cash flow / total revenues) reached a high level of 9%, which is comparable to that of the 2012 to 2014 cycle of high oil prices (and the corresponding cycle of the oilfield services industry is from 2013 to 2015). The cash flow performance of the oilfield services companies improved significantly, and is expected to even break through the high level of many years ago going forward.
Chart 3: Operating Cash Flows and Free Cash Flow Margin of the Four Largest Oilfield Services Companies
For now, the oil sector still has the potential to enter a super-cycle (generally defined as high prices + long period of time). We are optimistic that oil prices will stay higher for at least a longer period of time (see "Idea of the Week: Unravelling the Investment Logics of Oil Bonds" for more on this). Since the oil cycle does not come to an end, it is very likely that the oilfield services sector will not come to an end, given its nature of lagging behind. Therefore, we believe that the oilfield service industry is poised for a performance explosion, with oilfield service orders turning into massive cash inflows. The solvency of oilfield services companies is increasing sharply.
Decent Operating Performance with Explosive Future Performance
As shown in Chart 4, in the first three quarters of this year, Anton Oilfield Services’s new order increased by 22% YoY to RMB 4.3 billion. The order backlog increased to around RMB 10 billion, which is the historically high level. The operating performance is decent.
Chart 4: Anton Oilfield Services’s New Orders and Order Backlogs
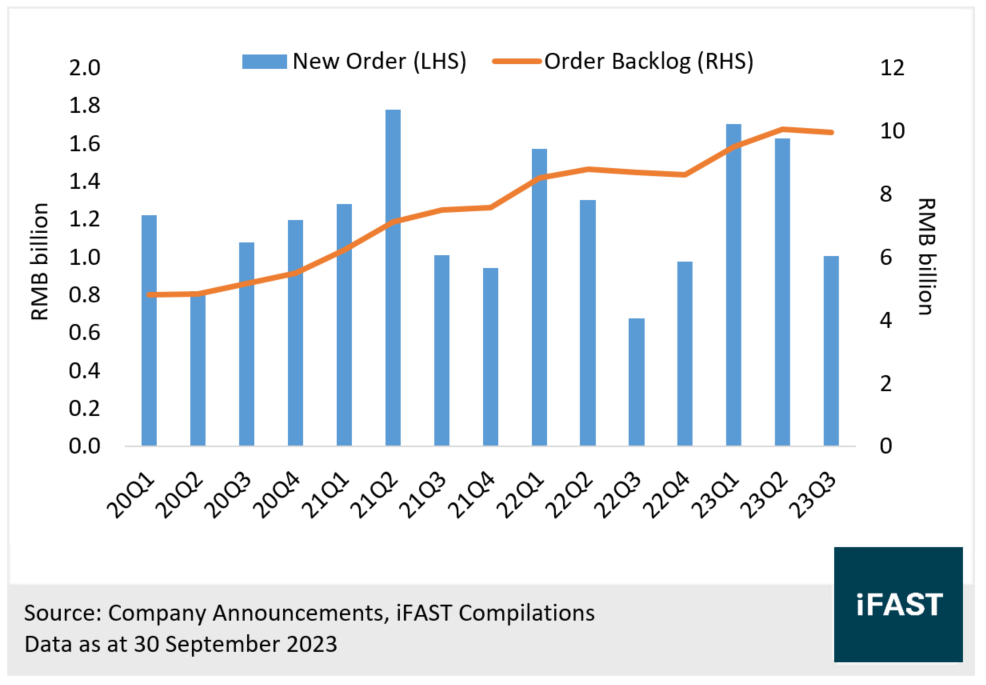
In particular, the order growth was mainly driven by new orders from the Iraq market (new orders from Iraq increased by approximately 88% YoY to RMB 1.7 billion). As the local government recognized the quality and technology of Anton's oilfield-related services, coupled with years of good cooperation records, Anton succeeded in securing a number of large orders in the first quarter and the second quarter.
These orders in hand will gradually be converted into revenue and profit for Anton, which will provide a greater visibility of cash flows. Therefore we can expect Anton's future performance to be explosive.
Strong Cash Flow Performances are Largely Enhancing Debt Repayment Ability
Due to an increase in orders and strong liquidity of oil companies, in recent years, Anton’s cash flow performances were strong. For example, the company recorded operating cash flows of RMB 1.32 billion and free cash flow of RMB 0.75 billion during 2022 and the first half 2023 (in a total of 1.5 years). These cash flows are the fundamentals of debt repayment.
Chart 5: Anton’s Operating Cash Flow and Free Cash Flow
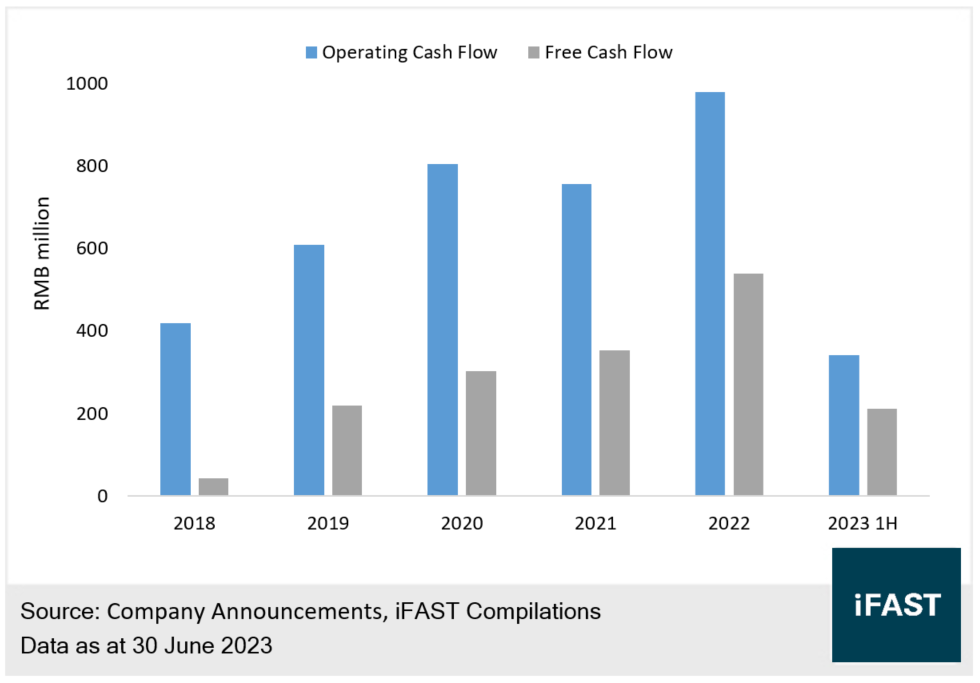
We believe that the strong cash flow performance will be continued. While it might not be able to maintain a high growth under the high-base effect, its debt repayment ability would be largely enhanced, given that the company maintains this level of cash flows in the next 1.5 years (around RMB 300 million to RMB 400 million each year). Then, the company could be able to repay the January 2025 USD bond (principal amount of around USD 117 million, equivalent to around RMB 856 million).
Besides, Anton intends to spin-off and list its subsidiary, T-ALL Inspection Group, in China's onshore market. In March 2022, the company sought strategic investors to inject a capital of RMB 55.1 million and subscribe around 4% equity ownership of T-ALL Inspection Group Co. (representing T-ALL Inspection Group Co.’s valuation of around RMB 1.36 billion). The company’s equity ownership on T-ALL Inspection Group Co. was reduced to 81.3%. This could replenish the company’s short-term liquidity.
Anton aims to listing T-ALL Inspection Group Co. by the end of 2025. If the company successfully completes the spilt-off and the listing of T-ALL Inspection Group, then it could recycle capital over RMB 200 million. In addition, the T-ALL Inspection Group’s shares have a higher liquidity. These become the potential liquidity source of Anton.
With Strong Repayment Ability, Investors could Consider the January 2025 Bond
As shown in Table 1, as of the end of 2023, Anton’s total debt was only RMB 2.28 billion. The leverage level kept decreasing, such as a net gearing ratio decreased to 16.9% and net debt to free cash flow further dropped to 1.0 times. It means the company could repay all the debts by one-year free cash flow and the cash position. The leverage level is low.
About the debt structure, Anton’s debt consists of 38% in 2025 USD bond, 5% in unsecured bank loans and the remaining 56% in secured bank loans. Its debt structure is simple. We expect most of its bank loans can be refinanced continuously. Currently, the company has to deal with the incoming January 2025 USD bond, with a principal amount of around USD 117 million (equivalent to RMB 856 million).
Along with Anton’s rich cash level and the large increase in order backlogs, we estimate that the company could generate around RMB 600 million in free cash flow from the second half year of 2023 to the end of 2024, when the bond is matured, the company could take advantage of its internal resources (including the cash and free cash flow) to repay the 2025 bond. Its repayment ability is strong.
Table 1: Anton’s Credit Indicators
|
Dec 20 |
Dec 21 |
Dec 22 |
Jun 23 |
|
|
Total Cash (RMB billion) |
1.33 |
1.59 |
1.21 |
1.69 |
|
- Restricted Cash (RMB billion) |
0.45 |
0.41 |
0.48 |
0.53 |
|
- Non-restricted Cash (RMB billion) |
0.88 |
1.17 |
0.73 |
1.17 |
|
Total Debt (RMB billion) |
2.93 |
2.94 |
2.07 |
2.28 |
|
Net Gearing Ratio (%) |
57.6% |
47.9% |
26.1% |
16.9% |
|
Net Debt to Free Cash Flow (times) |
5.3x |
3.8x |
1.6x |
1.0x |
|
Cash To Short-term Debt |
1.4x |
0.8x |
1.0x |
1.2x |
|
Cash Interest Coverage Ratio (times) |
2.5x |
4.3x |
4.6x |
4.9x |
|
Source: Company’s Reports, iFAST Compilations Data as of 30 June 2023 |
||||
Therefore, investors could consider the January 2025 bond, ANTOIL 8.750% 26Jan2025 Corp (USD), with a yield to maturity of around 21% and a potential total return of up to 24%.
Under the high oil price environment, the bond yields of almost all oil companies with strong solvency have significantly declined. Thus, the Anton bond is probably the only choice for an ultra-high yield with a manageable credit risk in the oil and gas sector.
Related Risks
Anton relies on a small number of customers in terms of the revenue stream. It means the company has a high risk of customer concentration. The company’s largest customers are CNPC and Sinopec, with the top five customers accounting for around 70% of revenues. If any of these customers decide to terminate the company’s services, or if these customers have significant financial issues, these could have a large impact on the company’s revenues.
Investors should be also aware of recession risk. It could reduce the oil demand, given the shrinking global consumption and sluggish economic activities. These might lead to a decline in oil prices and reduce the capital expenditure plans of oil producers, resulting in fewer new orders and less revenues for Anton.
A significant portion of the company's business is located in Iraq, which accounts for around 30% to 40% of the company’s revenues. It carries a certain degree of emerging market risk. The political situation in Iraq may be more volatile, and the economic and business environment is not as stable as in mainstream countries around the world.
Investors have to pay attention to the repurchase agreement committed to those strategic investors. If the spin-off of T-ALL Inspection Group Co. fails, Anton needs to repurchase the shares held by the strategic investors at the cost of the strategic investors’ capital plus difference. It is similar to the company borrowing a loan from a strategic investor at a 10% interest rate, implying that the failure of the spin-off may affect the liquidity of the company.
Conclusion
Anton Oilfield Services is an oilfield services company, providing drilling technology, completion products and technology, downhole technology and drilling tool services in the PRC, Iraq, Africa and Southeast Asia, etc. However, the turbulence in the Middle East should not have a significant impact on Anton.
The oilfield services industry is the beneficiary of high oil prices. The oilfield service industry is poised for a performance explosion, with oilfield service orders turning into massive cash inflows. The solvency of oilfield services companies is increasing sharply.
Anton’s operating and cash flow performances are decent. The increase in orders and strong cash flows are the fundamentals of debt repayment. The company intends to spin-off and list its subsidiary, T-ALL Inspection Group, in China's onshore market, which is the potential liquidity source of Anton. The company could repay all the debts by one-year free cash flow and the cash position. The leverage level is low, with strong repayment ability.
Investors could consider Anton’s January 2025 bond, ANTOIL 8.750% 26Jan2025 Corp (USD), with a net yield to maturity of around 21% and a potential total return of up to 24%. The Anton bond is probably the only choice for an ultra-high yield with a manageable credit risk in the oil and gas sector.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.t holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!